A network taking shape across the Indian Ocean corridor
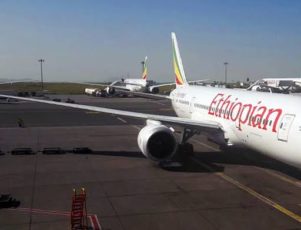
Addis Ababa’s Bole International Airport has become the clearest emblem of this shift. Ethiopian Airlines, sub-Saharan Africa’s largest carrier by network reach, operates direct services to Dubai, Abu Dhabi, Jeddah and Riyadh, and carried more than ten million passengers annually in the years before the pandemic, according to the airline’s published performance data. Its recovery since 2021 has been brisk, and its Gulf routes rank among the most commercially significant in its network.
On the Gulf side, Emirates operates services to more than twenty African destinations, a figure confirmed by the carrier’s own route maps. Flydubai, its low-cost affiliate, has added secondary African cities, extending connectivity to markets that full-service carriers previously bypassed. Qatar Airways has historically maintained services to at least a dozen African cities, with East and West Africa both featuring prominently in its expansion plans. Collectively, these networks have materially changed the direct travel options available from Kigali, Harare or Zanzibar over the course of a decade.
The corridor is not uniform. East Africa’s connection to the Gulf is the most developed, built on decades of labor migration and trade flows linked to GCC states. West Africa has historically relied on European hubs, but carriers like Air Senegal, alongside Gulf entrants such as Flydubai and Air Arabia, are beginning to alter this balance. North Africa occupies a distinct position: Cairo serves simultaneously as an African and an Arab hub, while Morocco’s growing aviation sector has attracted Gulf investor attention alongside expanded direct services.
RwandAir illustrates the ambition of smaller African carriers in this space. By positioning Kigali as a continental transit hub with Gulf-facing routes, the airline has secured partnerships and codeshares that amplify its network well beyond what its home market alone could sustain. Air Senegal is pursuing a comparable logic from West Africa.
Cargo as a driver of Africa-Gulf corridor growth
Passenger numbers tend to dominate aviation headlines, but freight is an equally significant driver of corridor expansion. East Africa’s fresh flower and vegetable export economy depends almost entirely on reliable air freight, with Kenyan roses destined for Gulf retailers transiting through Nairobi’s Jomo Kenyatta International Airport on daily schedules. Ethiopian Airlines Cargo, one of the continent’s largest freight operators, has expanded its dedicated freighter capacity precisely to serve these high-value, time-sensitive flows.
The pandemic years reinforced cargo’s centrality in an unexpected way. When passenger planes were grounded, airlines discovered that dedicating freighters to medical supplies and essential goods on Africa-Gulf routes was both operationally necessary and commercially viable. That experience accelerated investment in cold-chain logistics, cargo terminal upgrades and direct freight partnerships. Gulf logistics operators, including those connected to Abu Dhabi’s and Dubai’s free-zone ecosystems, have since entered anchor agreements with African airport operators to handle growing volumes.
The direction of flow is not one-sided. Pharmaceuticals and manufactured goods moving from Gulf distribution hubs into African consumer markets are also reshaping cargo patterns. As African e-commerce platforms scale and regional supply chains tighten, demand for reliable direct air freight between Gulf distribution centers and African capitals is forecast to increase further, according to IATA’s regional aviation outlook for Africa.
Open skies policy and the regulatory gap
The commercial dynamism of this corridor exists in tension with regulatory fragmentation. Africa’s Single African Air Transport Market, known as SAATM, was launched under African Union auspices in 2018 to liberalize intra-African air travel and strengthen the continent’s competitive position. Progress has been uneven: as of recent AU assessments, fewer than forty of the fifty-five member states had formally acceded to the agreement, and practical implementation of open-skies provisions has lagged considerably behind the initial timetable.
Bilateral air service agreements between African states and Gulf counterparts add a further layer of complexity. Traffic rights and flight frequencies remain subject to negotiation, sometimes reflecting protections for national carriers rather than the interests of consumers or exporters. Where these constraints have eased, route expansion has followed quickly. Rwanda’s relatively liberal aviation policy has helped Kigali attract Gulf-facing services disproportionate to its population size, a lesson that other governments are now studying carefully.
Visa regimes compound the friction. For Gulf-based business travelers seeking to access multiple African markets in a single trip, the patchwork of visa-on-arrival policies and traditional embassy requirements remains a genuine barrier. Several African governments have simplified entry procedures in recent years, but continent-wide harmonization remains a medium-term aspiration rather than a present reality.
The stakes extend beyond traveler convenience. Aviation connectivity functions as infrastructure: it underpins deal-making and supports export-dependent industries from floriculture to pharmaceutical distribution. Investment flows between Africa and the Gulf are, in part, shaped by how accessible cities are to one another. Civil aviation authorities that push for open-skies provisions alongside airport investment are positioning their countries as genuine nodes in a reconfiguring South-South economic geography.
The commercial momentum behind this corridor is reflected in every new route launch and cargo terminal agreement. Whether institutional reform can move at the pace that airlines, exporters and investors now require is the question pressing hardest on policymakers at both ends of the route.