Politics
Category

African and Arab climate negotiators push for a new carbon finance order

Comments (0) Featured, Politics

African Union and Arab League delegates at a climate finance multilateral session

A shared stake in rewriting the rules

For years, climate finance negotiations operated on a familiar transfer logic: wealthy nations would mobilize capital for developing countries to adapt to climate impacts and pursue lower-emissions development paths. The reality proved more complicated. The gap between pledged and delivered climate finance has been a persistent source of friction, with the African Development Bank estimating that the continent alone requires more than $1.3 trillion in climate-related investments annually by 2030, against a fraction of that currently flowing from multilateral and bilateral sources.

What has shifted in recent years is the nature of the African and Middle Eastern response. Rather than limiting themselves to calls for more capital, delegations from both regions are now intervening on the architecture of climate finance itself: how carbon markets are structured, what standards govern carbon credit quality, how loss-and-damage funds are capitalized and distributed, and how concessional lending is designed so as not to compound the debt burdens of climate-vulnerable states. This shift from quantity to quality represents a genuine strategic evolution.

The African Union’s Climate Change and Resilient Development Strategy and the Arab League‘s growing engagement at multilateral climate forums have provided institutional platforms for this repositioning. Regional bodies are increasingly working to coordinate negotiating positions before major sessions, so that African and Middle Eastern representatives arrive with a coherent agenda rather than fragmented national interests that external parties can address bilaterally and piecemeal.

From recipients to rule-setters: the carbon market debate

Nowhere is this shift more apparent than in the debate over international carbon markets, particularly under Article 6 of the Paris Agreement. African and Middle Eastern countries collectively hold a disproportionate share of global renewable energy potential, carbon sink capacity in forests and coastal ecosystems, and the critical minerals underpinning the global clean energy supply chain. This resource base gives them both a material stake in and a legitimate claim to influence how carbon credits are certified, priced and retired.

Concerns about the integrity of early voluntary carbon market projects, many of which delivered questionable emissions reductions, have pushed African and Middle Eastern negotiators to advocate for stronger verification standards. They have also sought a larger share of carbon revenues directed toward host communities and national development priorities, rather than allowing those revenues to function primarily as compliance tools for corporations based elsewhere. Institutions including the African Development Bank and the Arab Monetary Fund have backed calls for multilateral mechanisms that channel carbon proceeds into industrial diversification and green infrastructure.

Local climate-technology firms are increasingly part of this advocacy ecosystem. Startups developing satellite-based measurement, reporting and verification tools, as well as platforms aggregating smallholder carbon projects, are feeding data directly into national negotiating positions. By improving the credibility of African and Middle Eastern carbon projects, these companies expand the revenues available to host governments and communities, closing the loop between local innovation and global rule-setting in a way that rarely makes international headlines.

Capital flows, sovereignty and what comes next

The stakes extend well beyond the negotiating room. If African and Middle Eastern states succeed in shaping more favorable terms in carbon markets and climate finance facilities, the outcome could be substantially larger capital flows into clean energy, adaptation infrastructure and climate-smart agriculture. The African Development Bank has identified green and sustainability-linked bond issuances as one vehicle for mobilizing this capital at scale. Several African sovereigns have already issued such instruments, testing the appetite of international investors for debt tied to verifiable climate outcomes. Proceeds from some of these bonds have been earmarked for renewable energy projects and adaptation measures, demonstrating that the instrument can carry both financial and developmental logic.

For Gulf states pursuing large-scale solar capacity and green hydrogen development, the ability to shape carbon finance tools fitted to their specific transition contexts matters both economically and strategically. These countries are simultaneously managing hydrocarbon revenues and building post-oil industrial bases, while positioning themselves as hubs for global climate finance. Their priorities do not always align perfectly with those of Sub-Saharan African economies, but on the central question of securing Global South leverage over donor-country conditionalities, there is meaningful common ground.

The coming months will test how durable this coordination can be. Preparatory ministerial meetings ahead of major climate summits are the concrete moments where Africa and the Middle East can present joint positions and, where possible, unified language. Debt treatment for climate-vulnerable states, the operationalization of Article 6 carbon markets, and the design of the loss-and-damage fund all remain contested terrain. The deeper question, for investors and observers alike, is whether these regions can translate shared strategic interests into rules that direct real capital toward local actors: a smallholder farmer monetizing a carbon sink in Uganda or a climate-tech startup in Cairo building MRV tools, rather than simply registering symbolic gains in formal declarations.
Read more

How African and MENA Leaders Are Rewriting the Rules of Global Finance

Comments (0) Politics

For much of the past three decades, African finance ministers arrived at IMF and World Bank annual meetings primarily with requests. That posture is changing. A growing number of African and Middle Eastern states now enter these forums with joint communiqués, technical papers and coalition strategies designed to shape, rather than merely respond to, the rules governing global capital flows.

This shift has clear institutional roots. The African Union coordinates common positions on financial governance ahead of major multilateral meetings, while the African Development Bank (AfDB) provides the analytical backbone for the argument that Africa’s sovereign borrowing costs do not reflect the actual creditworthiness of African states. The disparity between perceived risk and real default history has driven up the cost of borrowing for governments seeking to finance infrastructure and energy projects, restricting fiscal space precisely where spending needs are greatest.

The numbers make the case. According to AfDB data, several African countries now spend more than 20 percent of government revenue on external debt servicing. For some, the share approaches 40 percent. Those figures translate into deferred health facilities and stalled electricity projects. Agricultural support programs are among the first line items cut when debt servicing crowds out other spending, affecting tens of millions of people across the continent.

The Climate Finance Gap and MENA’s Energy Dilemma

Climate finance is a second front where Africa and the Middle East have found common purpose, even if the logic differs on each side. African states, particularly in sub-Saharan and East Africa, contribute a negligible share of global greenhouse gas emissions but carry a disproportionate share of climate-related economic losses, through droughts, flooding, coastal erosion and disruptions to food systems. Their demand, articulated at successive COP negotiations and UN high-level weeks, is that the global climate finance architecture consistently underdelivers.

The AfDB has estimated that Africa needs approximately 250 billion dollars per year in climate finance by 2030. Actual flows remain far below that level, with a significant portion arriving as loans rather than grants, adding to the very debt burden that African governments are simultaneously trying to reduce. The gap is embedded not only in total volume but in the design of multilateral funds and the complexity of accreditation processes that smaller national institutions struggle to navigate.

Middle Eastern states occupy a distinct but related position. Gulf economies are channeling hundreds of billions of dollars into renewable energy, green hydrogen and digital infrastructure as part of their diversification strategies. Their concern is that ESG standards and green finance frameworks, largely shaped in Europe, do not recognize the scale or pace of these transitions, making it harder to access international green capital on competitive terms. Saudi Arabia, the UAE and Qatar have each made this argument explicitly at recent climate and finance forums.

What connects both positions is a shared critique: financial rules not designed with African development trajectories or Gulf transition timelines in mind are now constraining governments responsible for some of the world’s fastest-growing populations and most strategically positioned energy resources.

From Advocacy to Architecture

The shift from grievance to governance proposal is visible in the specific reform demands that African and Middle Eastern leaders are advancing. African finance ministers, coordinating through the African Union and the G24 group of developing-country finance officials, have pushed for expanded IMF Special Drawing Rights allocations to low-income and climate-vulnerable countries. They have also backed the inclusion of climate-resilient debt clauses in sovereign bonds, a mechanism that would automatically suspend debt payments when a country suffers a major climate event, removing the difficult choice between servicing creditors and rebuilding after a cyclone or drought.

On multilateral development banks, the case centers on capital increases that preserve concessional lending windows and reduce financing costs for African governments. The G20 Common Framework for debt restructuring, launched in 2020, has drawn consistent criticism for its slow implementation. Ethiopian officials, among others, have called publicly for a faster process capable of keeping up with the number of countries in acute fiscal distress.

Gulf sovereign wealth funds introduce a different variable into this equation. Collectively managing assets estimated in the trillions of dollars, they are positioned to act as co-investors alongside multilateral institutions in African energy and infrastructure projects, potentially reducing the risk premiums that raise borrowing costs for the continent. Several co-investment platforms linking African and Gulf sovereign funds have been announced over the past two years. Translating those frameworks into projects at the scale and speed both regions require remains the central implementation challenge.

Whether the G7 shareholders of the Bretton Woods institutions will move beyond acknowledging these demands to incorporating them into binding governance changes is the open question. What is no longer in doubt is that Africa and the Middle East are arriving at these negotiations with more preparation, more data and more coordinated institutional strategy than at any previous moment in the postwar financial order. The architecture they are pushing to reshape was built without them at the table; the current generation of leaders intends that the next version will not be.

Photo : economist.com

Read more

Red Sea Crisis Reshapes African & Gulf Logistics

Comments (0) Featured, Politics

East African container port with cargo vessels at berth

The Red Sea corridor carries a substantial share of global container traffic between Asia, Europe and the Middle East. Since late 2023, security concerns around the Bab el-Mandeb strait have compelled carriers to divert vessels southward, with ripple effects extending far beyond the strait itself. Industry estimates suggest that rerouting around the Cape of Good Hope adds roughly two weeks to transit times and hundreds of thousands of dollars in additional fuel costs per voyage. Those costs translate into higher freight rates and steeper insurance premiums, ultimately squeezing food prices and industrial supply chains in economies along both coasts.

For ports in East Africa and the Gulf, the disruption has been simultaneously a pressure and a strategic opening. Facilities at Mombasa, Dar es Salaam and Djibouti have seen significant shifts in call patterns and cargo volumes as carriers reorganize their networks. Gulf hubs, particularly in the UAE, have had to adapt scheduling and warehousing capacity to accommodate new routing configurations. The question is no longer whether ports can absorb the shock. It is which ones can turn the reconfiguration into lasting competitive advantage.

The scale of the rerouting has been considerable. According to shipping analytics firms cited by Reuters, the share of Asia-Europe container traffic bypassing the Red Sea rose sharply from 2024, with several major liner operators suspending Red Sea transits indefinitely. That volume has to go somewhere, and the ports best positioned to capture it are those already investing in capacity and digital readiness.

How African and Gulf Port Operators Are Adapting

What distinguishes this period from previous disruptions is the pace at which port authorities and logistics firms across Africa and the Middle East have moved to innovate rather than simply react. Port management teams in East Africa have accelerated the digitalization of customs clearance, reducing dwell times and improving berth utilization to handle unpredictable call patterns. Several facilities have also expanded hinterland connectivity, investing in inland container depots and rail links to reduce congestion when vessel surges arrive.

In the Gulf, logistics operators have drawn on existing digital infrastructure to offer dynamic routing and cargo tracking services now in higher demand precisely because of the uncertainty that diversions introduce. Dubai’s position as a transshipment hub has given it particular flexibility: its port authority has adjusted scheduling windows and storage allocations to accommodate carriers rethinking their network designs. Saudi facilities at Jeddah and Dammam have similarly moved to enhance throughput capacity and speed up customs processing.

Logistics technology firms based in Nairobi, Lagos and Dubai are seeing growing interest in their products. Route optimization platforms and real-time cargo visibility tools have found new clients among freight forwarders and importers navigating cost and timeline uncertainty, according to reporting by Disrupt Africa and Wamda covering the regional startup space. This demand has accelerated both product development and fundraising for several of these companies, reinforcing a broader trend of logistics tech maturation across the Africa-Middle East corridor.

Insurance and trade finance present another dimension of the story. Maritime insurance premiums for Red Sea transit rose sharply after disruptions intensified, prompting some African traders to explore alternative risk-sharing arrangements. Regional development finance providers, including the African Development Bank, have examined how to support smaller traders most exposed to freight cost volatility, with some analysts calling for dedicated liquidity facilities linked to route disruption events. Carriers, meanwhile, have split between adding security surcharges and absorbing rerouting costs to retain long-term commercial relationships with African ports.

Long-Term Implications for the Africa-Middle East Corridor

The medium-term implications extend well beyond shipping timetables. African ports that adapt successfully stand to consolidate their roles as regional gateways and transshipment centers. The African Development Bank has argued in its infrastructure publications that port modernization can catalyze broader industrial growth by reducing logistics costs for manufacturers and agribusinesses. A sustained increase in traffic through East African facilities could therefore accelerate investment in adjacent activities such as cold chain logistics, warehousing and light processing.

For Gulf port operators, the disruptions have reinforced the strategic value of their geographic position as connectivity nodes between Asia, Africa and Europe. State-backed operators in the UAE and Saudi Arabia have used the period to deepen partnerships with African port authorities, including concession agreements and technical assistance arrangements that extend Gulf logistics expertise into Africa’s growing markets. These partnerships, when structured equitably, combine Gulf capital with African market access in ways that benefit both sides.

What the Red Sea episode has demonstrated is that the Africa-Middle East maritime corridor is not a passive conduit for global trade. It is a space where port executives, logistics entrepreneurs and trade finance professionals are actively shaping new patterns of connectivity. The disruption has accelerated cross-regional cooperation that calmer periods might have left unresolved, and the infrastructure investments now underway are unlikely to be reversed when the geopolitical situation eventually shifts.

Ports that have used the interval to build digital capacity, diversify their service offerings and lock in new commercial relationships are likely to emerge better positioned regardless of which route ultimately dominates global container flows. The Cape of Good Hope detour may prove temporary; the competitive reshaping of the Africa-Middle East logistics landscape is not.

Read more

Gulf Capital Goes Green in Africa

Comments (0) Featured, Politics

African climate startup founders at a Gulf investment forum in Dubai

The adaptation finance gap at the heart of African development

Africa’s climate paradox is well documented, but its economic consequences remain underestimated outside the region. The continent produces less than 4 percent of global greenhouse gas emissions, according to the Intergovernmental Panel on Climate Change, yet it absorbs a disproportionate share of climate-related costs. Drought patterns in the Horn of Africa and recurrent flooding across West and Central Africa translate into direct losses in agricultural output and eroded infrastructure investment. The African Development Bank (AfDB) has estimated that Africa requires roughly $1.3 trillion in climate finance between 2020 and 2030, or about $130 billion annually, to adequately address adaptation and mitigation combined. Actual flows remain far below that figure.

This gap has defined African negotiating positions at successive UN climate conferences. Delegations at COP27 in Sharm el-Sheikh and COP28 in Dubai consistently argued that existing mechanisms favour mitigation over adaptation and that pledges from wealthier nations have not materialized on schedule. The loss-and-damage fund agreed at COP27 represents a partial response, but its initial capitalization is limited relative to need. For many African governments and innovators, the political conclusion is clear: depending solely on traditional development finance channels is not sufficient.

Gulf capital and African climate needs: a convergence under way

Gulf states, driven by large-scale economic diversification programs, are redirecting sovereign wealth toward sectors with long-term returns. Climate-relevant infrastructure and technology increasingly fit that profile. Saudi Arabia’s Public Investment Fund, which manages assets exceeding $700 billion, has stated public commitments to sustainability and clean energy. Abu Dhabi’s Mubadala Investment Company and ADQ have pursued Africa-facing strategies in infrastructure and food security, two areas directly intersected by climate risk. The Abu Dhabi Fund for Development, a bilateral development institution, has financed adaptation-related agricultural and water projects across the continent.

The UAE’s hosting of COP28 in Dubai in December 2023 added institutional weight to this orientation. The conference produced a pledge of $30 billion for the ALTÉRRA climate fund, anchored in Abu Dhabi, with a stated aim of mobilizing up to $250 billion in global climate finance by 2030. A portion of ALTÉRRA’s mandate explicitly targets investments in climate solutions in emerging markets, Africa included. While full deployment depends on deal flow and institutional capacity, the fund’s creation is a concrete new vehicle through which Gulf resources could reach African climate innovators, rather than simply circulating within established Northern finance networks.

The African side is not passive. The AfDB and the Global Center on Adaptation jointly launched the Africa Adaptation Acceleration Program, targeting $25 billion by 2025. Startups working in climate-smart agriculture and off-grid renewable energy have grown across hubs in Nairobi and Lagos. Several are not executing donor-funded pilots but building revenue-generating businesses that need growth capital, not grants.

What South-South finance means in practice

The convergence of Gulf capital and African adaptation demand does not happen automatically. It requires institutional intermediaries and governance frameworks attuned to local conditions, as well as tools to bridge very different expectations about risk and return.

Blended finance structures, in which a development institution de-risks an initial tranche to attract private capital, have become a standard tool in this space. Gulf and African development banks are collaborating on such facilities in agriculture and water infrastructure. Co-investment between Gulf family offices and African venture funds is also growing in agritech and climate data services, driven partly by diaspora networks connecting the two regions. Dubai and Abu Dhabi, which have attracted a significant number of African startup founders and executives, serve as informal nodes where relationships form before they become formal transactions.

The logic of this South-South axis differs from that of traditional Western climate donors. Gulf investors are commercial actors with explicit return expectations, which means African climate startups must demonstrate revenue models and scalability rather than simply qualifying under humanitarian criteria. That pressure can sharpen business thinking. It also risks sidelining adaptation projects whose returns are social and systemic rather than directly financial, a tension that African policymakers and regional institutions will need to manage deliberately.

Building durable structures for Africa-Gulf climate finance

The Africa-Gulf climate finance relationship is still being structured, and several governance questions remain open. How will African governments and civil society shape the allocation of Gulf-backed climate capital? What norms will govern procurement and local employment? How will technology transfer be structured so that domestic private sectors capture lasting economic value?

These questions carry particular weight given the scale of sovereign assets involved. African regional institutions, from the AfDB to bodies under the African Union’s development agenda, have a role in setting frameworks that maximize local benefit. Without that architecture, even substantial capital flows can pass through without building the adaptation capacity the continent needs.

For African climate innovators, the opportunity is tangible. The combination of Gulf capital and growing diaspora networks creates a genuine opening that did not exist a decade ago. Whether it consolidates into a durable South-South finance axis or remains a series of disconnected deals will depend on the institutional bridges that African and Gulf stakeholders are prepared to build together, and on who holds the pen when those frameworks are written.

Read more

From Rabat to Pretoria: How African Leaders Are Responding to the 2026 Iran War

Comments (0) Politics

The recent escalation known as the 2026 Iran War, involving Iran and several countries of the Arabian Peninsula, has prompted a wide range of reactions from African leaders. Governments across the continent have responded with statements reflecting their diplomatic priorities, strategic alliances, and concerns about the broader consequences of the conflict.

Support for Gulf States

Several African governments have openly expressed solidarity with Arab countries in the Gulf following Iranian strikes targeting states in the region.

Morocco strongly condemned the attacks and reaffirmed its support for what it described as “brotherly Arab states.” King Mohammed VI reportedly communicated with leaders from the United Arab Emirates, Qatar, Bahrain and Saudi Arabia to reiterate Morocco’s support for their sovereignty and security. Morocco’s reaction reflects its long-standing diplomatic and economic ties with Gulf monarchies.

Algeria also surprised some observers by aligning itself with the Gulf countries despite historically maintaining relatively cordial relations with Iran. Algerian authorities condemned attacks against the sovereignty of Arab states and emphasized the need to preserve regional stability.

Calls for Restraint and Mediation

Other African leaders have taken a more cautious diplomatic approach, emphasizing dialogue rather than alignment.

South African President Cyril Ramaphosa called for restraint and respect for international law while warning that a prolonged conflict could destabilize global supply chains and energy markets. South Africa also indicated that it could support mediation efforts if the parties involved requested it. This position is consistent with Pretoria’s broader foreign policy, which traditionally favors diplomacy and negotiated solutions.

Similarly, leaders in several African countries have encouraged all sides to avoid further escalation and to prioritize diplomatic negotiations.

The African Union’s Position

At the continental level, the African Union also reacted to the escalation. The organization condemned attacks against the sovereignty of Gulf states while simultaneously urging all parties to de-escalate tensions.

The African Union stressed the importance of dialogue and international cooperation to prevent the conflict from spreading further across the region and affecting global stability.

Economic Concerns Across the Continent

Beyond diplomatic positioning, African leaders are increasingly worried about the economic consequences of the conflict.

Many African economies depend heavily on imported energy and international shipping routes. Rising tensions in the Middle East could lead to higher oil prices and disruptions in maritime trade, particularly if key routes such as the Strait of Hormuz are affected.

South Africa has already warned that instability in the region could place additional pressure on African supply chains and increase inflation in several economies.

A Continent Navigating Complex Diplomacy

The responses from African leaders illustrate the continent’s complex diplomatic positioning in global conflicts. While some governments have clearly sided with Gulf partners, others prefer neutrality and mediation.

Despite these differences, most African leaders share a common concern: prolonged instability in the Middle East could have far-reaching geopolitical and economic consequences for Africa and the wider world.

Read more

The Elite of Mboa” offers a witty political simulation rooted in African realities

Comments (0) Featured, Politics

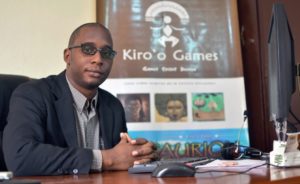
In the heart of Yaoundé, Cameroon, a video game studio is gaining international recognition for its bold and original storytelling. Kiro’o Games, founded in 2012 by Olivier Madiba, has made it its mission to place African stories at the center of the gaming world. With its latest release, “The Elite of Mboa” (also known as Le Responsable), the studio delivers a humorous, strategic take on political life in a fictional African country—blending gameplay with social critique.

Kiro’o Games, short for Kiroho Maono (meaning “spiritual vision” in Swahili), is the first video game studio in Central Africa. Since its creation, the studio has trained and employed a team of young developers and artists, most of them local. It operates with a clear goal: to break away from Western-dominated narratives and build a game universe that reflects the realities and imagination of the African continent.

In 2015, Kiro’o Games launched its first title, “Aurion: Legacy of the Kori-Odan,” an action RPG inspired by African mythology. The game received international praise for its originality and world-building. To fund its development, the studio raised over 300,000 dollars through a mix of crowdfunding and international angel investors—an unprecedented achievement for a startup in the region.

“The Elite of Mboa”: A Game of Choices, Corruption, and Comedy

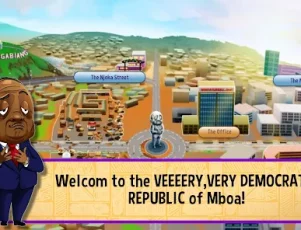
“The Elite of Mboa,” released in 2020, is a satirical simulation game set in the fictional republic of Mboa. Players take on the role of a young graduate who lands a job in the Ministry of Paperwork and must navigate the complexities of public service, family obligations, and career ambitions. The game offers multiple storylines depending on the player’s choices, including whether to act with integrity or fall into corruption.

Players manage a character’s resources, organize public events, dodge internal audits, and interact with a colorful cast of coworkers and politicians. The design of the game draws heavily on the social and political culture of Central Africa, using local humor, real-world inspired scenarios, and expressive dialogue. It is available in both English and French and is compatible with PC and Android platforms.

As of 2024, “The Elite of Mboa” has been downloaded more than 60,000 times and is receiving increasing attention from educators and NGOs who see it as a tool for sparking conversations about governance, ethics, and civic responsibility in Africa. The game is also being adapted for mobile and console, and Kiro’o Games is actively working on expanding its reach.

Alongside game development, the studio has launched Kiro’o Rebuntu, a mentorship and funding platform designed to support young African entrepreneurs in the digital and creative industries.

By mixing satire with thoughtful gameplay, Kiro’o Games continues to prove that Africa not only has unique stories to tell but also the creative power and technical skill to share them with the world.

Photos : premortem.games –

Read more

Ghana’s President-elect Mahama’s Plans and Challenges

Comments (0) Politics

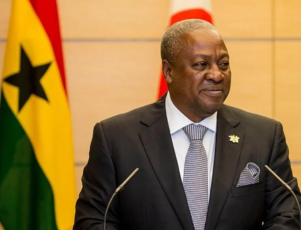
John Dramani Mahama, a prominent Ghanaian politician, has been declared President-elect following the December 7, 2024, general elections. Securing 56.55% of the vote, Mahama, representing the National Democratic Congress (NDC), achieved a decisive victory over Vice President Mahamudu Bawumia of the New Patriotic Party (NPP), who garnered 41.61%.

Born on November 29, 1958, in Damongo, Mahama’s political journey is marked by significant milestones. He previously served as President from 2012 to 2017, ascending from the Vice Presidency after the untimely demise of President John Atta Mills. His tenure was characterized by infrastructural development and efforts to diversify Ghana’s economy.

In his acceptance speech, Mahama emphasized a commitment to national unity and economic revitalization, stating, “This is a new beginning for Ghana.” He acknowledged the challenges ahead and pledged to work tirelessly to rebuild the nation.

The Ghana’s first female Vice President

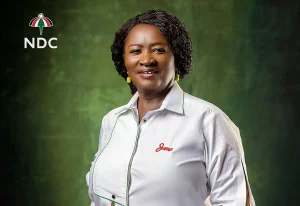
A notable aspect of Mahama’s victory is the election of his running mate, Professor Jane Naana Opoku-Agyemang, who will become Ghana’s first female Vice President. This historic achievement has been lauded as a progressive step towards gender inclusivity in Ghanaian politics.

Professor Jane Naana Opoku-Agyemang

Professor Jane Naana Opoku-Agyemang

Mahama’s campaign resonated with voters amid economic challenges, including high inflation and a cost-of-living crisis. He has expressed intentions to renegotiate Ghana’s $3 billion bailout deal with the International Monetary Fund (IMF) to address wasteful state spending and enhance the energy sector. Mahama stated, “We’re bound by it but… it should be possible to make some adjustments to suit reality.”

Additionally, Mahama has pledged to reform the cocoa sector, a vital component of Ghana’s economy. He criticized the current structure where the state-run regulator, COCOBOD, competes with farmers for profits. Mahama proposes restructuring COCOBOD to act solely as a regulator and quality controller, allowing farmers to receive payments directly. He hinted at potential private sector involvement to improve efficiency and boost production.

Addressing corruption is also a priority for the President-elect. Mahama has constituted an anti-corruption team, chaired by Member of Parliament Samuel Okudzeto Ablakwa, to tackle suspected graft and recover misappropriated assets. This initiative underscores his commitment to transparency and accountability in governance.

Mahama’s return to power reflects a broader trend in West Africa, where economic dissatisfaction has led to the resurgence of former leaders. His victory is seen as a mandate to address pressing economic issues and restore confidence in Ghana’s democratic institutions.

As he prepares to assume office on January 7, 2025, Mahama faces the formidable task of steering Ghana through economic recovery, implementing structural reforms, and fostering national cohesion. His leadership will be pivotal in navigating the complexities of governance and meeting the aspirations of the Ghanaian people.

Photos : al24news.com and happyghana.com

Read more

Oman Vision 2040 and Its Ambitious AI Programme to Drive the Digital Economy

Comments (0) Politics

Oman Vision 2040 is a strategic plan that sets a roadmap for the country’s socio-economic development over the next two decades. Launched to diversify Oman’s economy and reduce its reliance on oil revenue, the vision encompasses reforms in various sectors, including healthcare, education, environment, and technology. At its core, Oman Vision 2040 focuses on transforming the nation into a knowledge-based economy by promoting sustainable development, human capital growth, and digital transformation.

Unveiling the Ambitious AI Programme

In alignment with Vision 2040, Oman recently launched an ambitious Artificial Intelligence (AI) programme, designed to accelerate digital transformation and position the country as a competitive player in the global digital economy. This initiative emphasizes the adoption of advanced technologies, particularly AI, across government sectors, industries, and services. The AI programme, unveiled by Oman’s Ministry of Transport, Communications, and Information Technology, aims to incorporate AI into daily operations, drive innovation, and optimize services in healthcare, education, logistics, and energy.
The AI initiative also focuses on local talent development. Oman is investing in education and training programmes to build a skilled workforce capable of supporting AI research and development, thus fostering an environment that encourages digital literacy and technical expertise. This investment aims to create job opportunities in high-tech sectors and prepare Oman’s workforce for a data-driven future.

Driving Digital Transformation and the Digital Economy

Through the AI programme, Oman seeks to stimulate growth in its digital economy. By enhancing productivity, enabling automation, and facilitating data-driven decision-making, the country aims to increase its economic competitiveness. This will be achieved by fostering AI adoption in various industries, allowing businesses to innovate and improve efficiencies. Key initiatives include digitizing government services, which are expected to streamline processes, increase accessibility, and improve the quality of public services.

In addition to boosting the digital economy, Oman’s AI programme targets the development of robust AI infrastructure, such as high-performance computing capabilities and data centers, to support the vast processing needs of AI technologies. The government also plans to encourage partnerships with international tech companies and research institutions, fostering an ecosystem of collaboration and knowledge exchange that will further accelerate AI integration across Oman.

Challenges and Opportunities

While Oman’s Vision 2040 and the AI programme set an ambitious course, challenges remain. Building AI capabilities requires substantial investment in infrastructure, education, and regulatory frameworks. Oman will need to ensure cybersecurity measures and data privacy protections to build trust in AI systems among its citizens and international partners.

However, these challenges present opportunities as well. The AI programme has the potential to position Oman as a tech leader in the Middle East, drawing foreign investments, fostering innovation, and creating a model for AI-driven growth. By harnessing AI responsibly and ensuring inclusivity in digital advancements, Oman can achieve substantial socio-economic benefits.

Oman’s Vision 2040, coupled with the new AI programme, illustrates the nation’s commitment to digital transformation and sustainable economic growth. This initiative is expected to empower local talent, foster innovation, and modernize key sectors. With careful planning, strategic investments, and a focus on building an inclusive digital society, Oman is positioning itself to be a leader in the digital economy and a competitive player on the global stage by 2040.

Photos : omtilak.net – iskanco.com

Read more

Algeria: A “Start-Up Nation” with Global Aspirations

Comments (0) Politics

Algeria, traditionally known for its rich history and vast natural resources, is increasingly being recognized as a burgeoning “start-up nation.” This North African country, with a young and tech-savvy population, is making strides towards establishing itself as a hub for innovation and entrepreneurship, aiming to leave a significant footprint on the global digital economy.

The Current Landscape

Algeria’s start-up ecosystem is still in its nascent stages, yet it shows immense promise. The government, realizing the potential of digital transformation, has been instrumental in fostering a conducive environment for start-ups. Initiatives like the National Startup Fund, established to finance innovative projects, and the implementation of the “Start-up Act,” which provides legal and financial support to young entrepreneurs, are pivotal in this journey.

The country’s youthful demographic is a key asset. With over 70% of the population under the age of 30, Algeria boasts a large, dynamic workforce eager to embrace new technologies and innovation. This demographic dividend, combined with increasing internet penetration and mobile usage, sets the stage for a thriving digital economy.

Innovative Projects and Sectors

Algerian start-ups are making waves across various sectors. In tech, there are burgeoning developments in AI, fintech, e-commerce, and renewable energy technologies. Notable examples include TemTem, a successful ride-hailing app, and Djazair Ta3mal, an online platform helping Algerians enhance their employability.

The agricultural sector, integral to the Algerian economy, is also seeing a digital overhaul. Start-ups are leveraging technology to improve agricultural productivity and sustainability, addressing challenges such as water scarcity and food security.

The Future Outlook

The future looks bright for Algeria’s “start-up nation” vision. The government’s increasing focus on digitization and economic diversification, away from oil dependency, signals a commitment to nurturing the start-up ecosystem. Moreover, the growing interest from international investors and venture capitalists in African tech start-ups could bode well for Algeria.

Advantages and Opportunities

Algeria’s strategic location as a gateway between Africa and Europe, combined with its large, young, and increasingly well-educated workforce, presents significant advantages. The country’s rich cultural heritage and diverse landscapes also offer untapped potential in sectors like tourism and cultural industries.

Furthermore, the government’s push towards enhancing digital infrastructure and the gradual shift in societal attitudes towards entrepreneurship are creating a fertile ground for innovation and business growth.

Challenges and Problems

However, the journey is not without its challenges. Bureaucracy, regulatory hurdles, and limited access to funding remain significant obstacles for many start-ups. Additionally, while the government has shown support, more consistent policies and effective implementation are needed to sustain long-term growth.

The education system, though improving, still needs to align more closely with the evolving demands of the digital economy. Bridging the skills gap and fostering a culture of innovation and critical thinking is crucial for the sustainable development of the start-up ecosystem.

Not Just a Dream but an Evolving Reality

Algeria’s aspirations to become a “start-up nation” reflect a bold and forward-thinking approach to economic development. While there are challenges to overcome, the country’s advantages, such as its young population, strategic location, and evolving digital landscape, provide a strong foundation for growth. With continued government support, international collaboration, and an emphasis on education and skills development, Algeria is well-positioned to realize its aspirations on the global stage. The nation’s journey towards becoming a hub of innovation and entrepreneurship is not just a dream but an evolving reality, paving the way for a vibrant and diversified economy.

Photos : israelvalley.com / jeuneafrique.com

Read more

Germany looks to Africa as energy crisis looms in Europe

Comments (0) Featured, Politics

With a sixth round of EU sanctions against Russian oil, Europe is looking to leave Russian gas behind for good. Germany is already looking at alternatives in Africa but ramping up production will not be a small task, with infrastructure challenges and increasing preference towards renewable energy over fossil fuels.

Europe looks to Africa as an alternative to Russia

With Russia ostracized in the wake of its invasion of Ukraine, and a sixth round of EU sanctions targeting Russian oil recently implemented, many countries in Europe are looking to leave Russian gas, oil, and coal behind for good. But cutting the use of Russian gas by 60% before the end of 2022 may come with a nasty side-effect – a lack of energy – especially over the winter where demand in Europe increases. Germany is already looking for alternatives in Africa, with the continent’s oil and gas reserves being an important topic at the June 2022 German-Africa Energy Forum in Hamburg. In 2020, African oil made up nearly 9% of global exports, with over 327 million metric tonnes produced on the continent. But ramping up production and getting it to Europe will not be an easy task, with infrastructure challenges and the zeitgeist in Europe moving towards renewable energy over fossil fuels.

Lack of investment at home raises questions for export

The first major barrier for gas exports to Germany is the lack of infrastructure. Energy development projects are capital-intensive and generally require private-public partnerships. Sultan Wali, Ethiopia’s energy minister said that “African governments cannot carry out these projects alone.” Ndiarka Mbodji, the French-Senegalese founder of Berlin-based Kowry Energy echoed this, saying, “They need financial support from Germany and other rich western countries. Africa holds the key to resolving Europe’s energy crisis. And if we look at Africa’s resources, for example gas, you cannot underestimate its importance.”
Despite such a positive outlook for Africa to fulfill Germany’s gas demands, half of the continent’s population lacks access to clean energy, with many households dependent on burning biomass for energy. Moreover, some 900 million Africans lack access to clean cooking solutions, and on top of this, South Africa is in the midst of its own energy crisis. Load shedding is now a daily occurrence, and the situation is predicted to worsen despite the country holding significant natural gas potential. There will no doubt be those who question whether the continent can afford to export gas when it could be put to good use domestically.

Africa must act quickly to profit

Many German companies are keen to help finance African initiatives that produce hydrogen and natural gas for export to Europe, and African nations are keen to power up using gas. Because natural gas, which is mainly produced in Algeria, Nigeria, and Egypt, creates fewer carbon emissions than other fossil fuels like oil and coal it is seen as a ‘transitional fuel.’ Mbodji says that gas should not be overlooked, stating, “you can see at the moment, with the Ukraine war that we are going through, that there is a need to diversify the source of energy. And if we look at the resource that Africa has in terms of, for example, gas, which is a source of transition, we can see its importance in Africa.” 

The International Energy Agency (IEA) produced its Africa Energy Outlook for 2022, published on 20th June, where it said that Africa could be in a position to export some 30 billion cubic meters (bcm) to Europe by the end of the decade. If all of Africa’s natural gas discoveries are turned into production, Executive Director Fatih Birol has stated that it could make an additional 90 bcm per year by 2030, with around two-thirds of this going towards domestic needs and the rest for export.

But the IEA has said that Africa must act quickly if it is to profit from these vast reserves of natural gas. Europe will only want Africa’s gas until it can shift towards lower carbon technology, something that is being increasingly championed with ever more lofty net-zero promises being made by politicians.

Renewable energy also ramps up exports

There is another energy source that could be exported – solar. Taking advantage of the huge potential for solar energy near the Sahara Desert, a massive undersea power cable is coming to Europe from Egypt. The GREGY intersection, going from Northern Egypt and into Attica, Greece, brings 3,000 megawatts of clean solar power to Europe. At the same time, the Xlinks Morocco-UK power project will connect Alverdiscott, Devon, with a solar site in Morocco, providing enough power to supply seven million homes by 2030.

There isn’t enough African gas available right now to save Germany from an energy shortage this winter, and with Europe pushing for cleaner energy, by the time production has increased to a suitable level it may already be too late to capitalize on Africa’s reserves.


Photos : dw.com – logupdateafrica.com – foreignpolicy.com

Read more