Africa
Tag Archive

East Africa’s fintech corridors: from Gulf remittances to regional payment hubs

Comments (0) Non classé

From Nairobi to Dubai: the anatomy of a new financial corridor

For years, the story of East African fintech was largely domestic. M-Pesa launched in Kenya in 2007 and within a decade had transformed how Kenyans transferred money and accessed basic financial services, without crossing a single border. That domestic focus made sense: mobile money was solving an acute local problem, connecting an unbanked majority to essential services.

The focus is shifting. A new generation of fintech companies in Kenya, Rwanda and, more cautiously, Ethiopia is building cross-border payment infrastructure that connects East African users directly to exchange houses and digital wallets in Gulf Cooperation Council states. The push is driven by a clear economic reality: GCC countries host an estimated 2.5 million migrant workers from East Africa, and the money they send home is a critical pillar of household income.

According to World Bank data, Kenya received approximately $4.1 billion in remittances in 2023, making it one of the top remittance recipients on the continent. Ethiopia’s inbound transfers have exceeded $5 billion in recent years. The challenge is cost: the World Bank’s Remittance Prices Worldwide database shows that sending $200 to sub-Saharan Africa still costs an average of around 8 percent of the transaction value, nearly double the United Nations Sustainable Development Goal target of 3 percent. For a migrant worker in Riyadh or Dubai, that gap is felt every month.

A regulatory race to attract corridor business in East Africa

Rwanda has positioned itself most deliberately as a fintech hub for cross-border services. The National Bank of Rwanda operates a regulatory sandbox that allows companies to test interoperable payment products before full licensing, reducing the time and cost of compliance. This framework has attracted startups building East Africa–Gulf corridors and enabled partnerships with regional card networks and Gulf exchange houses, according to Disrupt Africa, which tracks startup activity across the continent.

Kenya’s Central Bank has progressively expanded its frameworks for licensed payment service providers, and partnerships between Kenyan platforms and Gulf-based fintech players have multiplied. Integrations with UAE-based digital wallets and Saudi exchange networks now allow users to send and receive funds in near-real time, compared with the multi-day processing that traditional bank transfers require.

Ethiopia represents the newest frontier. After decades of a tightly controlled financial sector, Addis Ababa has begun opening banking and payment services to private actors. A 2023 directive allowing foreign investors to hold minority stakes in Ethiopian banks was a significant regulatory step, one that fintech observers noted as an opening for diaspora-oriented payment services, given the size of Ethiopia’s Gulf-based diaspora. According to Disrupt Africa’s annual fintech reports, East Africa consistently attracts among the highest shares of fintech venture funding on the continent, with corridor-focused companies drawing backing from Gulf family offices, regional venture funds and development finance institutions.

Beyond the transaction: regional and continental implications

The expansion of these payment corridors carries consequences well beyond individual transfers. For families in Nairobi, Kigali or Addis Ababa who depend on Gulf remittances, lower fees and faster settlement mean more disposable income and greater financial predictability month to month. Central banks benefit as well: when transfers flow through regulated digital platforms rather than informal channels, monetary authorities gain clearer visibility into foreign currency flows, an advantage for monetary policy management.

There is a larger strategic picture. The African Continental Free Trade Area has set ambitious targets for intra-African trade, and seamless cross-border payments are a prerequisite for reaching them. Fintech corridors between East Africa and the Gulf can function as proving grounds for the interoperability standards that pan-African payment systems will eventually need. Each cross-border integration negotiated today, whether with a Saudi exchange house or a UAE neobank, produces the technical and legal templates that can later be adapted to African-to-African corridors.

Product managers in Nairobi consult with compliance officers in Abu Dhabi. Founders in Kigali pitch to sovereign fund analysts in Riyadh while adapting interfaces for Arabic-speaking users. These relationships, built deal by deal and license by license, form the connective tissue of a genuinely regional financial market.

The road ahead is not without friction. Liquidity management across multiple jurisdictions, combined with the patchwork of Know Your Customer requirements in both regions, creates ongoing compliance costs that weigh more heavily on smaller players. Currency volatility adds another layer of risk. Cross-border instant payment rails remain more aspiration than standard, despite progress by systems such as PAPSS in West and Central Africa and Buna in the Arab world.

For East Africa’s fintech founders, the direction is clear. The Gulf is both a source of diaspora capital and a live market for digital financial services. Building reliable bridges between these two realities, one corridor at a time, is becoming the defining strategic bet of this next phase of African fintech. Whether the region can sustain this momentum will depend as much on regulatory coordination between African and Gulf authorities as on the technology itself.
Read more

Africa Meets the Gulf: A New Powerhouse for Climate Infrastructure

Comments (0) Business

A continent-wide financing gap that redefined the opportunity

Africa’s infrastructure needs have long outpaced available capital. According to the African Development Bank (AfDB), the continent faces an annual infrastructure financing gap estimated at between 68 billion and 108 billion US dollars, depending on the methodology and sectors included. The range reflects the breadth of the shortfall: energy generation and transmission, roads and rail, water treatment, healthcare facilities and digital connectivity all figure into the calculation. No single funding source can bridge it.

For years, the dominant narrative framed this gap as a problem for Western donors and multilateral lenders to address. That framing is now giving way to something more complex. A new generation of African sovereign wealth funds has emerged as serious institutional investors, capable of negotiating with Gulf-based counterparts on increasingly equal terms. What is taking shape is a cross-regional co-investment architecture, still young but structurally significant, in which African and Middle Eastern state-backed funds act as co-principals rather than passive recipients.

Nigeria’s Sovereign Investment Authority (NSIA), Morocco’s Ithmar Capital, Egypt’s sovereign fund and regional infrastructure platforms like Africa50 have each built track records in project finance over the past decade. On the Gulf side, Saudi Arabia’s Public Investment Fund (PIF), Abu Dhabi’s Mubadala and ADQ, and Qatar Investment Authority (QIA) have all signaled Africa as a strategic diversification target, with mandates to deploy capital at scale beyond their home markets. The deals being structured between these institutions are becoming more sophisticated with each investment cycle.

How the Afro-Gulf co-investment model works in practice

The architecture of these partnerships typically involves several layers. A framework agreement between two funds establishes shared investment priorities and due diligence protocols. A co-investment vehicle or special purpose platform is then created to pool capital for a defined set of projects, often in a specific sector or geographic corridor. Each partner contributes equity, with debt raised from development finance institutions or commercial lenders alongside. This structure allows African funds to leverage Gulf capital while retaining meaningful roles in project governance and local execution.

Africa50, the pan-African infrastructure platform backed by African states and the AfDB, has been central to this model. It has financed projects spanning power generation, road networks and digital infrastructure across multiple African countries, in several cases alongside Gulf co-investors. Its design as an African-led institution is deliberate: deals are structured to direct procurement and operational contracts toward local firms where possible, and governance arrangements keep African decision-makers at the table from origination through completion.

Gulf funds see the long-term fundamentals in African infrastructure as compelling. Population growth, urbanization rates and rising domestic consumption create sustained demand for exactly the assets these funds want to hold: power plants, water utilities and logistics hubs. Combined with the diversification imperative facing fund managers in Riyadh, Abu Dhabi or Doha as their own economies reduce their hydrocarbon dependency, Africa’s infrastructure landscape represents both a growth bet and a portfolio hedge. Saudi Arabia’s PIF has articulated an explicit Africa strategy, as has Mubadala, whose investments on the continent span fintech and infrastructure.

The deals themselves cover considerable ground. Renewable energy parks in West and East Africa have attracted co-financing from Gulf vehicles alongside national development banks. Transport projects in North Africa have drawn in both Egyptian and Emirati capital. Hospital public-private partnerships in francophone Africa have featured Gulf equity alongside Moroccan and multilateral financing. The common thread is that African sovereign funds are increasingly originating and structuring transactions rather than simply co-signing deals designed elsewhere.

Climate resilience as the new investment thesis

The more recent shift in this co-investment landscape has been the explicit integration of climate criteria into infrastructure deal-making. This matters for two distinct reasons. First, international capital increasingly demands it: development finance institutions, European pension funds and Gulf sovereign co-investors all apply environmental and social governance screens that reward climate-resilient design and penalize assets that ignore long-term physical risk. Second, African and Middle Eastern governments have come to recognize that infrastructure built without climate adaptation provisions is simply bad economics, given the exposure of coastal cities, river basins and agricultural zones to worsening weather patterns.

The practical effects are visible in how projects are designed. Solar-plus-storage configurations are replacing diesel backup in power projects. Water treatment plants are engineered to handle more variable rainfall. Transmission networks in climate-exposed corridors are built with redundancy and adaptive capacity. These are not cosmetic additions; they alter capital costs, risk profiles and long-term operational viability. Sovereign funds, which typically have no obligation to return capital within a fixed fund lifecycle, are particularly well-suited to absorbing these upfront costs against decades-long asset returns.

For African governments, the central question is whether Gulf capital and sovereign fund co-investments will translate into local economic value. Discussions at the African Union level and within national investment frameworks increasingly focus on local content requirements, skill transfer provisions and procurement rules that direct infrastructure spending toward African firms. The ambition, articulated in AfDB strategy documents and national development plans from Senegal to Kenya, is that infrastructure finance should function as an industrial policy instrument, not simply as a vehicle for deploying sovereign assets.

The road ahead for Afro-Gulf infrastructure capital

The co-investment corridor being built between African and Gulf sovereign institutions is still in a formative phase, but its structural logic is durable. As long as Africa’s infrastructure gap persists, the appetite of Gulf funds for geographic diversification continues, and climate criteria reshape investment decisions across global markets, this partnership model will keep evolving. The key variable is whether deal structures will deepen local capacity and ownership over successive investment cycles, or settle into patterns that keep African funds as minority partners in externally driven capital deployments. That question will be answered not in communiqués but in the specific terms that sovereign executives negotiate in the years ahead.

Read more

Gulf investors anchor Morocco’s $35 billion green hydrogen drive

Comments (0) Business

ACWA Power Khalladi wind farm turbines, northern Morocco

The ‘Morocco Offer’: A State-Led Bet on Clean Energy Export

Morocco has been developing a national green hydrogen strategy since 2021, positioning the kingdom as a future exporter of hydrogen derivatives to European markets. The strategy rests on the country’s considerable solar and wind resources: according to the International Renewable Energy Agency (IRENA), Morocco is on course to achieve the third lowest green hydrogen production costs in the world by 2050, with projected costs ranging between roughly $0.7 and $1.4 per kilogram, placing it alongside a handful of resource-rich nations in the most competitive tier.

The centrepiece of that strategy is what Rabat calls the ‘Morocco Offer,’ a state-led initiative launched in 2024 to channel large-scale foreign investment into hydrogen production and derivative industries, offering preferential access to public land and associated infrastructure. In March 2025, Prime Minister Aziz Akhannouch chaired a steering committee that selected five investor groups for six specific projects, together valued at approximately $32 to $35 billion, according to AGBI and Morocco World News. The selected projects target production of green ammonia, e-fuels and clean steel, all within the kingdom’s southern provinces.

By February 2026, the programme moved from project selection to concrete land commitments. On 5 February, Akhannouch met in Rabat with representatives of all five investor groups to sign preliminary land reservation agreements. Each project gained access to up to 30,000 hectares, according to Ecofin Agency, enabling consortia to formally launch feasibility studies and move into active development.

Gulf Energy Companies Make Their Commitments Concrete

Two of the five selected investor groups carry direct Gulf capital, and their participation illustrates how the programme has become a practical Africa-Gulf energy partnership.

TAQA Morocco,  a subsidiary of Abu Dhabi National Energy Company, joined forces with Spain’s Moeve in a consortium focused on green ammonia and industrial e-fuels. Under the arrangement, TAQA Morocco is responsible for renewable energy generation underpinning the project, while Moeve leads e-fuels production and marketing. In its initial phase, the consortium expects to produce around 100,000 tonnes of hydrogen per year, converting that output into approximately 560,000 tonnes of green ammonia for both domestic use and export, according to a Moeve press release issued in February 2026.

Saudi Arabia’s ACWA Power entered the programme with its ‘Green Pearl’ project. The company is not a newcomer to Morocco: its total investments in the kingdom’s renewable energy sector already stand at close to $3 billion, making it one of the country’s largest foreign energy investors. As of late June 2026, ACWA Power’s management in Morocco confirmed to Asharq Business that the company is actively seeking to expand into green hydrogen, seawater desalination and energy storage, per Morocco World News. That statement, made during a visit to its Khalladi wind farm, signals a deepening commercial relationship rather than a one-off transaction.

The logic driving Gulf participation is strategic as well as financial. Saudi Arabia and the UAE are both diversifying their portfolios into clean-energy value chains expected to define the post-oil economy. Morocco, positioned at the western edge of North Africa with Atlantic deep-water ports and close proximity to European markets, offers geography well suited to that ambition. For Gulf energy majors, co-developing projects in Morocco is also a way to secure off-take relationships and supply chain positions before competitors do.

Local Stakes and the Industrialisation Imperative

The scale of the programme raises a question that runs through nearly every large infrastructure initiative on the continent: who captures the value?

Morocco’s government has framed the ‘Morocco Offer’ as more than an export platform. The kingdom’s hydrogen strategy envisions a domestic market of 4 terawatt hours alongside an export market of 10 TWh by 2030, requiring the construction of 6 gigawatts of new renewable capacity, as outlined by the Green Hydrogen Organisation. That production base is intended to feed domestic industries: green ammonia substituting for costly fertiliser imports, and clean hydrogen eventually feeding emerging steelmaking capacity. Morocco’s target of reaching 52% renewable electricity by 2030 adds domestic demand that reduces the risk of projects becoming purely export-oriented enclaves.

The feasibility study phase now under way will be critical in determining whether local industrialisation ambitions are written into binding contractual terms, including local content requirements, workforce development obligations and technology transfer commitments. Morocco’s Ministry of Energy Transition, led by Leïla Benali, has consistently stressed these conditions in parliamentary statements, though the detailed terms of individual project agreements remain commercially confidential.

The timeline is also demanding. Most projects target first exports by the late 2020s or early 2030s, coinciding with when the European Union’s hydrogen import strategy is expected to generate significant commercial pull. For Gulf investors experienced in financing long-horizon energy infrastructure in complex regulatory environments, such timelines are familiar terrain. For Morocco, the stakes reach further: the programme’s credibility as a global investment destination depends on whether the first projects are delivered on schedule and on the terms originally promised to investors and citizens alike.

What has changed in 2026 is that ambitions long confined to policy documents have been backed by signed land agreements, launched feasibility studies and companies committing capital on the record. ACWA Power’s latest signal of expanded ambitions in Morocco suggests that the Africa-Gulf green hydrogen axis is moving beyond the era of strategic announcements into one of practical implementation.

Read more

African and MENA startups build language-first AI to close the digital access gap

Comments (0) Politics

Most large language models are trained on data that skews heavily toward English. Research on widely used training corpora, including CommonCrawl, has documented that English alone accounts for roughly half of all source text, with fewer than ten languages making up the bulk of the remainder. Africa’s approximately 2,000 languages and the Arab world’s dozens of spoken dialects together represent a marginal fraction of that data, leaving hundreds of millions of users poorly served by AI systems now embedded in banking apps, healthcare platforms, public services and content moderation pipelines.

The practical consequences are concrete. A customer service chatbot in Nairobi that struggles with Sheng (the Swahili-English hybrid widely spoken across the city) fails to retain users and depresses digital adoption. In Northern Nigeria, content moderation tools with no understanding of Hausa idioms routinely miss harmful material circulating on major platforms. These are not edge cases: the populations affected number in the hundreds of millions across the continent and in MENA.

A new generation of language-first AI ventures

African and MENA entrepreneurs have identified this structural gap as both a business opportunity and, for many founders, a matter of equity. Among the most recognized initiatives is Masakhane, a pan-African research collective founded in 2019 that has mobilized hundreds of researchers across the continent to build open-source natural language processing datasets and models for African languages. Its outputs have been adopted by academic institutions and commercial developers in more than 30 countries, according to the organization’s published contributor data.

Lelapa AI, a Johannesburg-based startup, has pushed further into the commercial market. The company develops large language model applications specifically tuned to Southern and East African languages, targeting enterprise clients in financial services and telecommunications. In a 2023 interview with Disrupt Africa, founder Pelonomi Moiloa described the company’s approach as “culturally grounded AI,” assembled not by scraping random internet text but through direct collaboration with language communities.

In North Africa and the Gulf, the challenge takes a different shape. Modern Standard Arabic is widely written but rarely spoken in daily life in the same register across the Arab world: a Moroccan and a Yemeni user share a script but may communicate in mutually unintelligible dialects. The Mohammed bin Zayed University of Artificial Intelligence (MBZUAI) in Abu Dhabi has made multi-dialectal Arabic modelling a research priority and has extended that work to African Arabic-speaking communities in Sudan, Somalia and Mauritania, creating an analytical bridge between the two regions.

Cross-regional capital opening new pathways

The financial landscape has shifted alongside the technical one. Gulf-based cloud providers and venture funds have started treating African AI startups as strategic portfolio bets. Abu Dhabi’s G42 announced partnerships with African institutions in 2023 and 2024 to extend cloud infrastructure for AI research, reducing the compute barrier that had constrained startups working on data-intensive language model training.

Funding volumes in African AI remain modest by global standards but are accelerating. Partech’s 2023 Africa Tech Venture Capital report identified AI and machine learning as one of the fastest-growing subsectors in African tech investment, with activity concentrated in South Africa, Nigeria, Egypt and Kenya. Magnitt’s MENA data shows comparable growth from 2021 to 2023, with natural language processing and voice recognition consistently appearing among funded product categories.

The cross-regional dynamic is commercially relevant in ways that are not always visible. A startup that builds strong tools for Swahili and Hausa can, with targeted adaptation, address the Swahili-Arabic code-switching common in coastal East Africa, or the Hausa-Arabic bilingualism widespread in Northern Nigeria and Niger. Gulf-based investors experienced with the difficulties of Arabic dialect diversity increasingly recognize that African language AI founders are solving structurally analogous problems with transferable methods.

Language data governance and the long-term stakes

Language AI raises governance questions that extend well beyond any individual product launch. Training a model on community language data requires decisions about who owns that data, who benefits commercially from its use, and how cultural misrepresentations are identified and corrected. Kenya and South Africa have both updated data protection legislation in recent years, drawing on GDPR principles adapted to local contexts. How these frameworks apply to AI training data, particularly for languages spoken across multiple jurisdictions, remains legally unsettled.

Within the Masakhane community and at the African Union’s Digital Transformation Strategy secretariat, advocates have called for policy frameworks that treat language data as cultural heritage rather than purely as a commercial input. Their argument is structural: as AI tools become embedded in credit scoring, public service delivery and content moderation, the languages those tools understand will determine who participates fully in the digital economy.

African and MENA startups building language-first AI are working on questions that extend into data governance and cultural representation. Decisions about which languages AI systems understand will directly affect digital access for hundreds of millions of users, from credit scoring to public service delivery. Whether they secure the capital, regulatory frameworks and institutional partnerships needed to scale remains a question that investors, governments and multilateral bodies across both regions are beginning to address.

Read more

Africa and the Gulf Are Redrawing the Global Tourism Map

Comments (0) Business, Featured

For most of the past two decades, the Africa-Gulf aviation relationship was largely a story of stopovers. Dubai, Doha and Abu Dhabi became indispensable hubs for passengers transiting between African cities and European or Asian destinations, with Gulf carriers building formidable networks across the continent. Emirates serves more than 20 African countries; Qatar Airways operates routes to over 30 African destinations. But the character of these flows is changing. Increasingly, African travelers and Gulf visitors make direct bilateral trips for purposes beyond transit: business, leisure, medical care or family visits within diaspora communities.

This shift reflects structural changes on both sides. Gulf states, particularly Saudi Arabia and the UAE, have invested heavily in domestic tourism infrastructure as part of broader economic transformation programs. Saudi Vision 2030 set an explicit target of attracting 150 million visitors annually by 2030, a figure cited by the Saudi Tourism Authority, and African source markets represent a largely untapped opportunity. The UAE has long drawn West and East African business communities to Dubai, and that foundation is now being extended to leisure and hospitality. On the African side, tourism ministers from Kenya to Morocco have recognized that Gulf visitors, who tend to record higher per-capita spending than many other source markets, merit deliberate policy attention.

Visa Reform and Route Openings as Strategic Moves

The clearest expression of this strategic intent is the wave of visa liberalization that has advanced across the continent. Kenya’s decision to abolish visa requirements for all nationalities, implemented in January 2024, is among the most sweeping examples. The Kenyan government framed the move as an explicit economic measure, anticipating higher tourist volumes and increased business travel. Rwanda’s policy of visa-free entry for all African nationals, in place since 2018, has contributed to positioning Kigali as a preferred conference and business travel destination, supported by investment in convention infrastructure and direct international services.

Airline route decisions track closely alongside these policy shifts. Low-cost Gulf carriers, including flydubai and Air Arabia, have extended their African footprints to cities beyond the established hubs of Lagos, Nairobi and Johannesburg. New or expanded services to Accra, Dar es Salaam, Kigali and other secondary cities reduce travel time and cost, broadening the pool of potential travelers in both directions. Ethiopian Airlines, Africa’s largest carrier by revenue and network, has simultaneously reinforced its Gulf services, using Addis Ababa as a competing hub. The result is a route map with more options and greater downward pressure on fares.

Gulf-based hospitality investment reinforces the same momentum. Regional sovereign wealth funds and hotel groups have gradually increased their exposure to African markets, from high-end lodges in East Africa to business hotels in North African capitals. Abu Dhabi’s ADQ holding company has built a portfolio of investments across African infrastructure and services, signaling a pattern that other Gulf vehicles are beginning to follow in the hospitality and real estate segments.

Local Entrepreneurs Navigate Opportunity and Concentration Risk

Behind the policy announcements and airline route maps, a more granular story is developing at the level of individual businesses and communities. African tour operators, hotel managers, restaurateurs and event organizers who serve international visitors are recalibrating their offerings to Gulf traveler habits, including language, dietary requirements and seasonal preferences. In Marrakech, Nairobi and Kigali, hospitality entrepreneurs report a measurable increase in Gulf visitors over the past two years and are adapting accordingly.

For local actors, the opportunity carries tangible economic weight. Tourism is a labor-intensive sector with documented multiplier effects across accommodation, food service, transport and cultural activities. The United Nations World Tourism Organization consistently ranks African tourism as one of the continent’s most accessible paths to foreign exchange earnings and formal employment. According to UNWTO data, Africa welcomed approximately 70 million international arrivals in 2019 before the pandemic disrupted travel; recovery has been uneven since then but generally stronger in markets that have combined visa liberalization with proactive marketing to new source countries.

The risks deserve clear-eyed attention. A high degree of dependence on a narrow set of source markets exposes destinations to volatility: a geopolitical rupture, a currency shift or a health crisis can rapidly suppress arrivals from a single country. African tourism boards and destination management organizations are increasingly aware of this, and many pursue multi-corridor strategies that treat Gulf visitor growth as a complement to intra-African and European demand rather than a replacement. Environmental sustainability and equitable benefit distribution remain live concerns, particularly in ecologically sensitive areas or wherever large hospitality investments bypass local ownership structures.

The Africa-Gulf Corridor at an Inflection Point

The Africa-Gulf tourism corridor is at an early but accelerating stage of development. Policy conditions are improving, aviation infrastructure is widening, and investment flows are beginning to reflect a genuinely bilateral logic rather than a one-way transit relationship. Whether these gains translate into broad-based economic benefit will depend on decisions made at national and local level: how governments reinvest tourism revenues and whether local businesses can position themselves to capture a meaningful share of visitor spending beyond the large hospitality groups. The potential of the corridor is real; its returns remain a matter of deliberate choice.

Read more

Africa–Gulf: The New Payment Corridors Transforming Remittances

Comments (0) Business

Mobile money transfer app on smartphone, Nairobi, Kenya

For the millions of African workers employed across Gulf Cooperation Council states, the act of sending money home is a routine but costly exercise. According to the World Bank’s Remittance Prices Worldwide database, the average cost of sending 200 dollars from a Gulf country to sub-Saharan Africa has consistently exceeded 7 percent of the transaction value, more than double the 3 percent target set under the UN Sustainable Development Goals. For a domestic worker in Riyadh or a construction technician in Dubai, those fees translate directly into less money reaching a family in Nairobi, Accra, or Lagos.

That cost structure is now under sustained pressure. Over the past several years, a growing cohort of African fintech firms and Gulf-based digital payment platforms have begun constructing interoperable rails that bypass the slow, expensive correspondent banking chains which have long dominated these corridors. The result is a structurally significant reconfiguration of how Africa and the Middle East exchange value, driven not by multilateral mandate but by the commercial logic of founders and regulators on both sides of the corridor.

Mobile money meets Gulf financial modernization

Africa’s mobile money infrastructure is one of the more consequential financial developments of the past two decades. In Kenya, Tanzania, and Ghana, adult population penetration rates for mobile money wallets have surpassed 70 percent in some markets, according to the GSMA’s annual State of the Industry reports. Transaction volumes have grown at double-digit rates year-on-year across multiple markets. This domestic digitalization created an ecosystem capable of receiving international flows cheaply and near-instantly, provided the sending side could connect to it.

The Gulf has, in parallel, been modernizing its own financial infrastructure. Central banks in Saudi Arabia, the UAE, Bahrain, and Qatar have invested in real-time gross settlement systems and open banking frameworks that lower barriers for fintech entrants. Some Gulf central banks have reported more than 100 percent growth in contactless and instant transfer volumes within single-year periods. The combination of Africa’s mobile-first depth and the Gulf’s regulatory ambition creates the structural conditions for cross-border interoperability.

The operational mechanism is typically an API-based connection linking an African mobile wallet to a Gulf bank account or digital wallet. When an African fintech secures a payment license in a Gulf jurisdiction, it can offer customers the ability to load a wallet in dirhams or riyals and push funds to a mobile money account in Kenyan shillings or Ghanaian cedis within minutes. Several pan-African payment companies have pursued precisely this licensing strategy, seeking regulatory approval in the UAE and Saudi Arabia to serve large African diaspora communities. Gulf-based neobanks, meanwhile, have begun targeting African workers as a core customer segment, given the volume and regularity of their outbound transfers.

Beyond remittances: SME trade and strategic autonomy

The significance of this infrastructure extends well beyond personal remittances. African small and medium enterprises importing goods from Gulf trading hubs, particularly from Dubai’s re-export markets, have historically relied on international wire transfers that can take several days to settle and carry fees that erode already thin margins. Digital payment rails enabling near-instant settlement change the economics of cross-border trade in concrete ways. The African Development Bank has repeatedly emphasized the importance of payment efficiency in enabling intra-regional and South-South commerce, noting persistent gaps that formal banking has been slow to fill.

There is also a geopolitical dimension that analysts are beginning to discuss. Historically, remittance routes between the Gulf and Africa have run through Western correspondent banks or global money transfer operators, which have held considerable pricing power and data visibility over these flows. As African and Gulf actors build their own rails, they gain operational autonomy over fees and routing decisions. This represents a gradual diversification of the financial connective tissue linking the two regions, with African and Gulf actors exercising greater agency than before.

The Islamic Development Bank and the Arab-Africa Trade Bridges program have signaled interest in formalizing such corridors further, linking payment infrastructure to trade finance and development objectives. Regulatory coordination between Gulf and African central banks, while still at an early stage, is beginning to surface as a topic in bilateral and multilateral financial diplomacy.

A corridor still under construction

The buildout of Africa-Gulf digital payment infrastructure remains a work in progress. Regulatory fragmentation across Africa’s 54 jurisdictions means that a license secured in Nigeria does not automatically confer access in Senegal or Ethiopia. Currency volatility in several African markets adds foreign exchange risk that technology alone cannot absorb. Consumer trust in new digital products, particularly among older or less digitally literate migrant workers, requires sustained investment in agent networks and customer education.

None of these obstacles is insurmountable. The trajectory of the sector, measured in licensing milestones and expanding transaction volumes, points clearly toward continued integration. What distinguishes this moment is that the architects of these corridors are not waiting for a global institution to hand them a blueprint. African fintech founders expanding into Gulf markets, Gulf payment operators targeting African diasporas and regulators in both regions adjusting their frameworks are collectively building a financial layer that serves hundreds of millions of people in ways the legacy system never prioritized.

Read more

How African and MENA Leaders Are Rewriting the Rules of Global Finance

Comments (0) Politics

For much of the past three decades, African finance ministers arrived at IMF and World Bank annual meetings primarily with requests. That posture is changing. A growing number of African and Middle Eastern states now enter these forums with joint communiqués, technical papers and coalition strategies designed to shape, rather than merely respond to, the rules governing global capital flows.

This shift has clear institutional roots. The African Union coordinates common positions on financial governance ahead of major multilateral meetings, while the African Development Bank (AfDB) provides the analytical backbone for the argument that Africa’s sovereign borrowing costs do not reflect the actual creditworthiness of African states. The disparity between perceived risk and real default history has driven up the cost of borrowing for governments seeking to finance infrastructure and energy projects, restricting fiscal space precisely where spending needs are greatest.

The numbers make the case. According to AfDB data, several African countries now spend more than 20 percent of government revenue on external debt servicing. For some, the share approaches 40 percent. Those figures translate into deferred health facilities and stalled electricity projects. Agricultural support programs are among the first line items cut when debt servicing crowds out other spending, affecting tens of millions of people across the continent.

The Climate Finance Gap and MENA’s Energy Dilemma

Climate finance is a second front where Africa and the Middle East have found common purpose, even if the logic differs on each side. African states, particularly in sub-Saharan and East Africa, contribute a negligible share of global greenhouse gas emissions but carry a disproportionate share of climate-related economic losses, through droughts, flooding, coastal erosion and disruptions to food systems. Their demand, articulated at successive COP negotiations and UN high-level weeks, is that the global climate finance architecture consistently underdelivers.

The AfDB has estimated that Africa needs approximately 250 billion dollars per year in climate finance by 2030. Actual flows remain far below that level, with a significant portion arriving as loans rather than grants, adding to the very debt burden that African governments are simultaneously trying to reduce. The gap is embedded not only in total volume but in the design of multilateral funds and the complexity of accreditation processes that smaller national institutions struggle to navigate.

Middle Eastern states occupy a distinct but related position. Gulf economies are channeling hundreds of billions of dollars into renewable energy, green hydrogen and digital infrastructure as part of their diversification strategies. Their concern is that ESG standards and green finance frameworks, largely shaped in Europe, do not recognize the scale or pace of these transitions, making it harder to access international green capital on competitive terms. Saudi Arabia, the UAE and Qatar have each made this argument explicitly at recent climate and finance forums.

What connects both positions is a shared critique: financial rules not designed with African development trajectories or Gulf transition timelines in mind are now constraining governments responsible for some of the world’s fastest-growing populations and most strategically positioned energy resources.

From Advocacy to Architecture

The shift from grievance to governance proposal is visible in the specific reform demands that African and Middle Eastern leaders are advancing. African finance ministers, coordinating through the African Union and the G24 group of developing-country finance officials, have pushed for expanded IMF Special Drawing Rights allocations to low-income and climate-vulnerable countries. They have also backed the inclusion of climate-resilient debt clauses in sovereign bonds, a mechanism that would automatically suspend debt payments when a country suffers a major climate event, removing the difficult choice between servicing creditors and rebuilding after a cyclone or drought.

On multilateral development banks, the case centers on capital increases that preserve concessional lending windows and reduce financing costs for African governments. The G20 Common Framework for debt restructuring, launched in 2020, has drawn consistent criticism for its slow implementation. Ethiopian officials, among others, have called publicly for a faster process capable of keeping up with the number of countries in acute fiscal distress.

Gulf sovereign wealth funds introduce a different variable into this equation. Collectively managing assets estimated in the trillions of dollars, they are positioned to act as co-investors alongside multilateral institutions in African energy and infrastructure projects, potentially reducing the risk premiums that raise borrowing costs for the continent. Several co-investment platforms linking African and Gulf sovereign funds have been announced over the past two years. Translating those frameworks into projects at the scale and speed both regions require remains the central implementation challenge.

Whether the G7 shareholders of the Bretton Woods institutions will move beyond acknowledging these demands to incorporating them into binding governance changes is the open question. What is no longer in doubt is that Africa and the Middle East are arriving at these negotiations with more preparation, more data and more coordinated institutional strategy than at any previous moment in the postwar financial order. The architecture they are pushing to reshape was built without them at the table; the current generation of leaders intends that the next version will not be.

Photo : economist.com

Read more

Gulf sovereign funds move into African critical minerals

Comments (0) Business

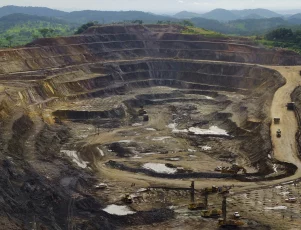
Open-pit copper mine in Zambia's Copperbelt region, southern Africa

In January 2023, Saudi Arabia’s Public Investment Fund (PIF) and national mining company Ma’aden launched Manara Minerals, a joint venture designed to acquire stakes in mining assets worldwide. Africa was named a priority region from the outset, reflecting the continent’s commanding position in several minerals considered critical for the energy transition. The Democratic Republic of Congo alone accounts for roughly 70 percent of global cobalt production, according to US Geological Survey data, while the DRC and Zambia together form one of the world’s largest copper belts. Zimbabwe, Namibia and Guinea hold significant lithium, rare earth and bauxite reserves respectively.

Manara’s creation was not an isolated signal. Emirati sovereign wealth funds, including Mubadala Investment Company and ADQ, have also earmarked capital for African resource sectors over the past several years. The logic is direct: as electric vehicle sales and renewable energy storage scale up globally, demand for cobalt, lithium, nickel and copper is projected to multiply significantly over the coming decade, according to the International Energy Agency’s Critical Minerals Market Review. Gulf states, which built sovereign wealth funds on hydrocarbon revenues, are positioning themselves as indispensable nodes in the new energy supply chain even as oil’s relative centrality shifts.

The scale of the opportunity on the African side is substantial. Africa is estimated to hold around 30 percent of global mineral reserves relevant to battery production when cobalt, manganese and other inputs are combined, per African Development Bank analysis. Gulf capital entering this space therefore meets a continent whose resource endowment is increasingly acknowledged as a strategic geopolitical asset, not merely a raw commodity source.

African governments push back: from extraction to processing

African policymakers have made clear they do not intend to repeat earlier extractive patterns. Zambia and the Democratic Republic of Congo signed a memorandum in 2023 to collaborate on building an electric vehicle battery value chain, targeting local production of precursor chemicals and battery cells. Under this framework, both countries sought investors willing to fund smelting, refining and manufacturing capacity inside their borders, rather than simply shipping unprocessed ore concentrate abroad.

This posture reflects a wider continental debate about beneficiation. The African Union’s Agenda 2063 and the African Continental Free Trade Area both explicitly support industrialization goals that tie resource extraction to downstream manufacturing. Several African governments have moved from rhetoric to concrete policy instruments: export restrictions on raw ores, licensing conditions and fiscal incentives have been deployed to steer investment toward processing facilities. For Gulf investors, this means that securing access to African minerals now requires negotiating over where value is created, not just who extracts it.

How Gulf entities respond to this insistence will shape the quality of Africa-Gulf mineral partnerships. Some have expressed willingness to co-fund refining infrastructure, which would align with African industrial ambitions. Others have focused primarily on equity stakes in upstream operations. African mining ministers and trade negotiators have made it clear that partnerships offering only extraction rights will encounter tougher political conditions than those bringing processing investment and technology transfer.

A competitive field, with African actors asserting leverage

Gulf investment in African minerals does not unfold in isolation. Chinese firms and state entities have built deep relationships across African mining sectors over the past two decades, funding infrastructure and acquiring concessions from the DRC to Guinea. Western governments have also stepped up engagement: the US Minerals Security Partnership and the European Union’s Critical Raw Materials Act both seek to diversify supply chains away from dominant single sources, with Africa as a key partner.

African leaders have shown increasing willingness to use this competitive environment as leverage. The 2023 BRICS expansion, which brought Egypt, Ethiopia, Saudi Arabia and the UAE into the bloc at the Johannesburg summit, created a shared forum where African and Middle Eastern states can align on global economic governance questions, including trade rules for critical minerals. The practical ability to play different investors against each other is still developing, but the intention is clearly articulated by a growing number of African finance and mining officials.

For Gulf states, building durable partnerships in African mining requires more than capital deployment. It requires long-term presence, technical co-investment and a political relationship that survives government changes and commodity price cycles. Saudi Arabia’s PIF and the Manara vehicle face this test as they move from initial deal exploration to actual project development. The quality of these early partnerships will shape how African governments and publics perceive Gulf actors in the sector for years to come.

The trajectory of Africa-Gulf critical minerals cooperation is ultimately an industrial policy story more than a finance story. Whether African cobalt, lithium and copper end up processed locally or exported raw, whether Gulf capital helps build battery factories in Lusaka or Kinshasa or simply adds another layer of foreign ownership to existing mines: these choices will determine how much of the energy transition’s economic value is captured on the continent. As Manara Minerals and comparable vehicles move from exploration to execution over the next few years, they will provide the clearest test yet of whether Gulf-Africa mineral partnerships can deliver on the industrial ambitions both sides have publicly articulated.

Read more

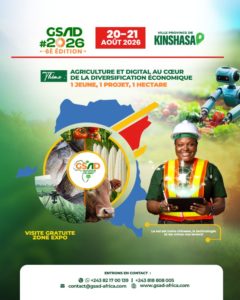
Kinshasa to host a major GSAD Africa session in August 2026

Comments (0) Business, Featured

Africa’s agricultural sector is undergoing a profound transformation. Digital tools, innovative startups and new investment models are changing how farmers produce, manage and sell their crops. In this context, the Grand Salon de l’Agribusiness et du Digital en Afrique (GSAD Africa) has become a key platform bringing together the actors shaping the future of agriculture on the continent.

The next major session will take place 20–21 August 2026 in Kinshasa, Democratic Republic of Congo. This edition is expected to attract a wide range of participants from across Africa and beyond, including entrepreneurs, farmers, agribusiness companies, investors, policymakers, researchers and technology experts.

Kinshasa, one of Africa’s largest cities and an important economic hub in Central Africa, provides a strategic location for discussions on agricultural development and digital transformation. The event aims to highlight the opportunities offered by technology to improve agricultural productivity, strengthen food security and develop competitive agricultural value chains.

The GSAD Africa sessions are known for their strong focus on collaboration. By bringing together public institutions, private companies and startups, the event creates a space where ideas, partnerships and investment opportunities can emerge. Young innovators developing AgriTech solutions will have the opportunity to present their projects alongside established agribusiness leaders.
International organizations, development institutions and financial actors are also expected to participate, reflecting the growing global interest in African agriculture as a sector with enormous economic potential.

A dynamic program for innovation, startups and investment

Over two days, the Kinshasa edition of GSAD Africa will feature a rich and dynamic program designed to encourage dialogue and collaboration.

The event will include conferences and roundtable discussions focused on major themes shaping the future of agriculture. Topics are expected to include digital platforms for agricultural markets, the role of artificial intelligence and satellite data in crop monitoring, climate-resilient agriculture, and innovative financing models for farmers and agricultural entrepreneurs.

Another highlight of the program will be the startup and innovation sessions. These sessions will showcase young African entrepreneurs developing technological solutions for agriculture, from mobile applications providing market information to digital tools for farm management, traceability and logistics.

Pitch sessions will give startups the opportunity to present their projects to investors, accelerators and potential partners. For many early-stage companies, this type of exposure can be crucial for securing funding and building strategic collaborations.

The exhibition space will also allow companies and organizations to present new agricultural technologies, digital services and innovative equipment. Participants will be able to discover tools designed to improve productivity, reduce post-harvest losses and strengthen agricultural supply chains.

Networking will play a central role throughout the event. Informal meetings, business sessions and collaborative workshops will help participants connect, exchange ideas and explore potential partnerships.

How to participate

Participation in the GSAD Africa Kinshasa session (20–21 August 2026) is open to entrepreneurs, investors, farmers, researchers, students and professionals interested in agribusiness and digital innovation.

Registration details, partnership opportunities and program updates are available through the official GSAD Africa platform and event organizers. Early registration is recommended, as the event is expected to attract a large number of participants from across the African agribusiness ecosystem.

With its focus on innovation, entrepreneurship and investment, the Kinshasa session of GSAD Africa promises to be one of the key gatherings for anyone interested in the future of agriculture on the continent.

Photos : facebook.com/GSAD2024

Read more

A New Instant Payment Corridor Links Africa and Gulf

Comments (0) Business, Featured

The price of sending money home

Each month, millions of African workers across the Gulf complete a familiar ritual: queuing at exchange bureaus or tapping through remittance apps to send a portion of their wages back to families in Lagos, Nairobi, Accra or Addis Ababa. The financial cost of that ritual remains stubbornly high. According to World Bank data, the average fee for sending 200 US dollars to sub-Saharan Africa consistently exceeds 8 percent, nearly double the 3 percent target set by the United Nations Sustainable Development Goals. Across remittance flows that exceed 50 billion US dollars annually into the sub-Saharan region, that gap translates into billions drained from household budgets every year.

The problem is structural. Africa’s payment landscape is fragmented across dozens of national currencies, incompatible settlement systems and correspondent banking chains that add cost and delay at each link. Small traders importing goods from Dubai or Jeddah face the same friction: converting currencies, navigating trade finance and absorbing fees that erode already thin margins. For many businesses, the informal dollar becomes the default, keeping large swathes of cross-border commerce invisible to regulators and inaccessible to formal credit.

PAPSS and the push for regional infrastructure

A coordinated response has been taking shape since 2022, centered on the Pan-African Payment and Settlement System (PAPSS), an initiative backed by the African Export-Import Bank (Afreximbank) and designed to support the African Continental Free Trade Area (AfCFTA). PAPSS enables cross-border transactions to settle in local African currencies without routing payments through correspondent banks in New York or London, compressing settlement times from days to seconds. By 2024, the system had moved beyond its initial West African pilot, with central banks across multiple regions signing on as settlement agents, per Afreximbank’s official communications.

On the Gulf side, regulators in the UAE, Saudi Arabia and Bahrain have simultaneously opened their fintech markets. Saudi Arabia’s BUNA system, operated by the Arab Monetary Fund, is specifically designed to facilitate Arab and cross-regional currency transfers, offering a potential integration point for African payment corridors. The UAE’s open banking framework and the Central Bank of the UAE’s payment infrastructure modernization program have further lowered barriers for African fintechs seeking access to one of the world’s largest concentrations of African diaspora workers. These two sets of infrastructure, advancing on parallel tracks, create the technical conditions for a durable Afro-Gulf payments corridor.

Startups building the rails

Between the regional platforms, a cohort of African fintech companies is constructing the actual commercial rails. Nigerian, Kenyan, Ghanaian and Egyptian startups have built remittance and business-to-business payment products that allow users to transact across the Red Sea corridor via mobile wallets, bank accounts or prepaid cards. Their competitive pitch rests on speed (near-instant delivery versus one to three banking days), lower fees (targeting two to four percent versus the incumbent eight-plus percent) and last-mile reach through mobile money agents in towns that bank branches do not serve.

African fintech funding stood at roughly 2 to 4 billion US dollars annually in the 2022 to 2024 period, according to data compiled by Disrupt Africa, with payments platforms consistently claiming the largest share of that capital. Gulf investors have participated in several of the larger funding rounds, drawn by both financial return potential and strategic access to fast-growing consumer markets. The African Development Bank estimates Africa’s infrastructure financing gap at around 100 billion US dollars per year across sectors; digital financial infrastructure is increasingly treated as part of that gap rather than a secondary consideration.

Regulatory coordination: the corridor’s remaining bottleneck

Despite the momentum, one structural obstacle stands out. Differing capital controls, know-your-customer requirements, anti-money-laundering standards and foreign-exchange restrictions mean that a fintech authorized in Dubai is not automatically permitted to collect or disburse funds in Lagos or Nairobi. Each corridor requires bilateral engagement between central banks, creating a negotiation overhead that larger incumbents absorb far more easily than early-stage startups.

Conversations at multilateral forums, including sessions held on the sidelines of African Development Bank annual meetings and Gulf fintech summits, have begun to address this friction, with proposals for mutual recognition agreements between central banks and regulatory sandboxes covering cross-border products. Progress is gradual. The political logic, however, is clear: African and Gulf states both gain from formalizing payment corridors that currently operate partly in the shadow economy.

From migrant remittances to trade finance

The longer-term prize extends well beyond migrant remittances. African small and medium enterprises that import from Gulf free zones or export agricultural and manufactured goods into Gulf retail markets need affordable, fast settlement and trade finance tools. If PAPSS and its Gulf-side counterparts extend their reach into trade payments, the effect on intra-South commerce could be substantial. The World Bank has estimated that reducing trade costs across Africa by even a modest margin would add tens of billions of dollars in annual trade value under AfCFTA.

The architecture for an Afro-Gulf instant payments corridor is no longer hypothetical. The infrastructure exists in outline, the regulatory conversations are underway, and private capital is flowing into the startups that will carry the traffic. Whether the corridor scales to its potential will depend on whether central banks on both sides of the Red Sea choose to prioritize interoperability, and whether African fintech founders receive the sustained backing they need to outlast the negotiations.

Read more