Featured
Category

Gulf Investors Bet on African Agritech for Food Security

Comments (0) Agriculture, Featured

Gulf states have long understood that food is a strategic vulnerability. The UAE imports more than 80 percent of its caloric needs, according to figures cited under the country’s National Food Security Strategy. Saudi Arabia, whose non-renewable groundwater reserves are being rapidly depleted, has set explicit targets under Vision 2030 to reduce domestic agricultural water use and diversify international food supply chains. Qatar and Kuwait face structurally similar constraints. For all of them, the question is not whether to depend on imports, but how to make those imports more resilient and, over time, anchored in durable investment positions.

For much of the past two decades, the dominant Gulf response to this challenge was land. Sovereign funds and state-backed companies secured long-term leases on agricultural territory in Sudan, Ethiopia, Tanzania and elsewhere in Africa, directing production toward Gulf markets. Those arrangements generated sustained controversy in host countries, where critics argued that local food sovereignty was being traded for foreign capital with limited technology transfer or smallholder benefit. Several deals collapsed under political pressure. The model was not discredited outright, but it had clearly run up against its limits.

The pivot now underway is toward a different kind of partnership: investing in the technology layer that sits between African farmers and global markets.

African Agritech at the Center of a New Corridor

African agritech has grown substantially as a sector over the past five years. According to research compiled by Disrupt Africa, the number of agritech startups operating on the continent has increased year on year, with East and West Africa accounting for the largest share of activity. These companies range from input marketplaces and satellite-based advisory services to cold-chain logistics networks connecting smallholders to urban buyers. The problems they address are well-documented: the Food and Agriculture Organization estimates that post-harvest losses in many African markets reach 30 to 40 percent of total production, driven by poor storage infrastructure and fragmented supply chains, compounded by limited access to credit.

Kenya’s Apollo Agriculture, which uses satellite imagery and machine learning to extend bundled credit, fertiliser and crop insurance to smallholders, raised a $40 million Series B round in 2022, attracting investors drawn to both its financial model and its measurable impact on farm productivity. Twiga Foods, also Kenya-based, has built a digital marketplace and cold chain connecting smallholder producers to retailers in Nairobi, cutting out multiple layers of intermediaries. In Ghana, Complete Farmer operates a managed farming model that links vetted international buyers directly to local producers through a digital platform. Egypt has developed a cluster of agritech firms focused on water-efficient precision irrigation and controlled-environment agriculture, technologies with direct relevance to Gulf buyers managing their own water-constrained food systems.

It is in this landscape that Gulf capital is finding a new rationale. Abu Dhabi’s ADQ, one of the emirate’s sovereign wealth funds with an explicit mandate around food and agriculture, has positioned itself as an active investor in global food supply chain assets. Its interest in African agritech aligns with a broader UAE strategy of building stakes in companies that can eventually channel produce into Gulf supply chains while generating commercial returns. Saudi Arabia’s Public Investment Fund has similarly expanded its food sector portfolio, with international agricultural partnerships a growing component. These are not philanthropic gestures. They reflect a calculated recalibration of how Gulf states manage food system risk.

What the Corridor Means for Farmers and Policymakers

The emergence of this corridor raises questions that go beyond deal flow. The most important is who captures value, and on what terms. When Gulf capital backs an African agritech platform, benefits can flow in multiple directions: founders gain growth capital and farmers gain access to inputs and markets; Gulf investors, for their part, gain a stake in future food supply infrastructure. But those benefits are not automatic. Platform design, pricing structures and export orientation all shape whether smallholders see real income gains or simply become inputs in a supply chain that extracts value upward.

African policymakers are increasingly attentive to this dynamic. Kenya, Ghana and Egypt have established or are developing regulatory frameworks for agritech operations that include provisions on data ownership, farmer contract terms and local content requirements. The African Development Bank, through its Feed Africa strategy, has advocated for financing models that blend private capital with public safeguards, aiming to ensure that foreign investment in agriculture reinforces rather than displaces domestic food systems.

The governance question extends to cross-border data management. As agritech platforms accumulate granular data on soil conditions, crop yields and farmer behaviour, how that data is stored and monetised, and with whom it is shared, becomes a legitimate policy concern. Frameworks for agricultural data governance, analogous to the open banking standards being developed in fintech, are beginning to surface in discussions at the African Union and within regional economic communities.

For Gulf investors and African entrepreneurs alike, the corridor is real and expanding. The deals being made today, whether a venture round into a Kenyan input marketplace or a supply agreement between a Ghanaian managed-farm platform and a UAE-based food distributor, will set precedents for how this partnership operates over the long term. Getting the terms right matters not only for individual companies, but for the food security of two regions that share a compelling mutual interest in making agriculture work better.
Read more

Africa and the Gulf Are Redrawing the Global Tourism Map

Comments (0) Business, Featured

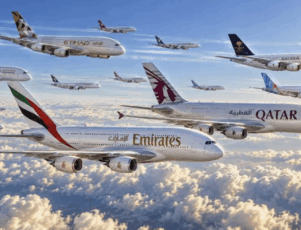
For most of the past two decades, the Africa-Gulf aviation relationship was largely a story of stopovers. Dubai, Doha and Abu Dhabi became indispensable hubs for passengers transiting between African cities and European or Asian destinations, with Gulf carriers building formidable networks across the continent. Emirates serves more than 20 African countries; Qatar Airways operates routes to over 30 African destinations. But the character of these flows is changing. Increasingly, African travelers and Gulf visitors make direct bilateral trips for purposes beyond transit: business, leisure, medical care or family visits within diaspora communities.

This shift reflects structural changes on both sides. Gulf states, particularly Saudi Arabia and the UAE, have invested heavily in domestic tourism infrastructure as part of broader economic transformation programs. Saudi Vision 2030 set an explicit target of attracting 150 million visitors annually by 2030, a figure cited by the Saudi Tourism Authority, and African source markets represent a largely untapped opportunity. The UAE has long drawn West and East African business communities to Dubai, and that foundation is now being extended to leisure and hospitality. On the African side, tourism ministers from Kenya to Morocco have recognized that Gulf visitors, who tend to record higher per-capita spending than many other source markets, merit deliberate policy attention.

Visa Reform and Route Openings as Strategic Moves

The clearest expression of this strategic intent is the wave of visa liberalization that has advanced across the continent. Kenya’s decision to abolish visa requirements for all nationalities, implemented in January 2024, is among the most sweeping examples. The Kenyan government framed the move as an explicit economic measure, anticipating higher tourist volumes and increased business travel. Rwanda’s policy of visa-free entry for all African nationals, in place since 2018, has contributed to positioning Kigali as a preferred conference and business travel destination, supported by investment in convention infrastructure and direct international services.

Airline route decisions track closely alongside these policy shifts. Low-cost Gulf carriers, including flydubai and Air Arabia, have extended their African footprints to cities beyond the established hubs of Lagos, Nairobi and Johannesburg. New or expanded services to Accra, Dar es Salaam, Kigali and other secondary cities reduce travel time and cost, broadening the pool of potential travelers in both directions. Ethiopian Airlines, Africa’s largest carrier by revenue and network, has simultaneously reinforced its Gulf services, using Addis Ababa as a competing hub. The result is a route map with more options and greater downward pressure on fares.

Gulf-based hospitality investment reinforces the same momentum. Regional sovereign wealth funds and hotel groups have gradually increased their exposure to African markets, from high-end lodges in East Africa to business hotels in North African capitals. Abu Dhabi’s ADQ holding company has built a portfolio of investments across African infrastructure and services, signaling a pattern that other Gulf vehicles are beginning to follow in the hospitality and real estate segments.

Local Entrepreneurs Navigate Opportunity and Concentration Risk

Behind the policy announcements and airline route maps, a more granular story is developing at the level of individual businesses and communities. African tour operators, hotel managers, restaurateurs and event organizers who serve international visitors are recalibrating their offerings to Gulf traveler habits, including language, dietary requirements and seasonal preferences. In Marrakech, Nairobi and Kigali, hospitality entrepreneurs report a measurable increase in Gulf visitors over the past two years and are adapting accordingly.

For local actors, the opportunity carries tangible economic weight. Tourism is a labor-intensive sector with documented multiplier effects across accommodation, food service, transport and cultural activities. The United Nations World Tourism Organization consistently ranks African tourism as one of the continent’s most accessible paths to foreign exchange earnings and formal employment. According to UNWTO data, Africa welcomed approximately 70 million international arrivals in 2019 before the pandemic disrupted travel; recovery has been uneven since then but generally stronger in markets that have combined visa liberalization with proactive marketing to new source countries.

The risks deserve clear-eyed attention. A high degree of dependence on a narrow set of source markets exposes destinations to volatility: a geopolitical rupture, a currency shift or a health crisis can rapidly suppress arrivals from a single country. African tourism boards and destination management organizations are increasingly aware of this, and many pursue multi-corridor strategies that treat Gulf visitor growth as a complement to intra-African and European demand rather than a replacement. Environmental sustainability and equitable benefit distribution remain live concerns, particularly in ecologically sensitive areas or wherever large hospitality investments bypass local ownership structures.

The Africa-Gulf Corridor at an Inflection Point

The Africa-Gulf tourism corridor is at an early but accelerating stage of development. Policy conditions are improving, aviation infrastructure is widening, and investment flows are beginning to reflect a genuinely bilateral logic rather than a one-way transit relationship. Whether these gains translate into broad-based economic benefit will depend on decisions made at national and local level: how governments reinvest tourism revenues and whether local businesses can position themselves to capture a meaningful share of visitor spending beyond the large hospitality groups. The potential of the corridor is real; its returns remain a matter of deliberate choice.

Read more

African and Arab climate negotiators push for a new carbon finance order

Comments (0) Featured, Politics

African Union and Arab League delegates at a climate finance multilateral session

A shared stake in rewriting the rules

For years, climate finance negotiations operated on a familiar transfer logic: wealthy nations would mobilize capital for developing countries to adapt to climate impacts and pursue lower-emissions development paths. The reality proved more complicated. The gap between pledged and delivered climate finance has been a persistent source of friction, with the African Development Bank estimating that the continent alone requires more than $1.3 trillion in climate-related investments annually by 2030, against a fraction of that currently flowing from multilateral and bilateral sources.

What has shifted in recent years is the nature of the African and Middle Eastern response. Rather than limiting themselves to calls for more capital, delegations from both regions are now intervening on the architecture of climate finance itself: how carbon markets are structured, what standards govern carbon credit quality, how loss-and-damage funds are capitalized and distributed, and how concessional lending is designed so as not to compound the debt burdens of climate-vulnerable states. This shift from quantity to quality represents a genuine strategic evolution.

The African Union’s Climate Change and Resilient Development Strategy and the Arab League‘s growing engagement at multilateral climate forums have provided institutional platforms for this repositioning. Regional bodies are increasingly working to coordinate negotiating positions before major sessions, so that African and Middle Eastern representatives arrive with a coherent agenda rather than fragmented national interests that external parties can address bilaterally and piecemeal.

From recipients to rule-setters: the carbon market debate

Nowhere is this shift more apparent than in the debate over international carbon markets, particularly under Article 6 of the Paris Agreement. African and Middle Eastern countries collectively hold a disproportionate share of global renewable energy potential, carbon sink capacity in forests and coastal ecosystems, and the critical minerals underpinning the global clean energy supply chain. This resource base gives them both a material stake in and a legitimate claim to influence how carbon credits are certified, priced and retired.

Concerns about the integrity of early voluntary carbon market projects, many of which delivered questionable emissions reductions, have pushed African and Middle Eastern negotiators to advocate for stronger verification standards. They have also sought a larger share of carbon revenues directed toward host communities and national development priorities, rather than allowing those revenues to function primarily as compliance tools for corporations based elsewhere. Institutions including the African Development Bank and the Arab Monetary Fund have backed calls for multilateral mechanisms that channel carbon proceeds into industrial diversification and green infrastructure.

Local climate-technology firms are increasingly part of this advocacy ecosystem. Startups developing satellite-based measurement, reporting and verification tools, as well as platforms aggregating smallholder carbon projects, are feeding data directly into national negotiating positions. By improving the credibility of African and Middle Eastern carbon projects, these companies expand the revenues available to host governments and communities, closing the loop between local innovation and global rule-setting in a way that rarely makes international headlines.

Capital flows, sovereignty and what comes next

The stakes extend well beyond the negotiating room. If African and Middle Eastern states succeed in shaping more favorable terms in carbon markets and climate finance facilities, the outcome could be substantially larger capital flows into clean energy, adaptation infrastructure and climate-smart agriculture. The African Development Bank has identified green and sustainability-linked bond issuances as one vehicle for mobilizing this capital at scale. Several African sovereigns have already issued such instruments, testing the appetite of international investors for debt tied to verifiable climate outcomes. Proceeds from some of these bonds have been earmarked for renewable energy projects and adaptation measures, demonstrating that the instrument can carry both financial and developmental logic.

For Gulf states pursuing large-scale solar capacity and green hydrogen development, the ability to shape carbon finance tools fitted to their specific transition contexts matters both economically and strategically. These countries are simultaneously managing hydrocarbon revenues and building post-oil industrial bases, while positioning themselves as hubs for global climate finance. Their priorities do not always align perfectly with those of Sub-Saharan African economies, but on the central question of securing Global South leverage over donor-country conditionalities, there is meaningful common ground.

The coming months will test how durable this coordination can be. Preparatory ministerial meetings ahead of major climate summits are the concrete moments where Africa and the Middle East can present joint positions and, where possible, unified language. Debt treatment for climate-vulnerable states, the operationalization of Article 6 carbon markets, and the design of the loss-and-damage fund all remain contested terrain. The deeper question, for investors and observers alike, is whether these regions can translate shared strategic interests into rules that direct real capital toward local actors: a smallholder farmer monetizing a carbon sink in Uganda or a climate-tech startup in Cairo building MRV tools, rather than simply registering symbolic gains in formal declarations.

Read more

Red Sea Crisis Reshapes African & Gulf Logistics

Comments (0) Featured, Politics

East African container port with cargo vessels at berth

The Red Sea corridor carries a substantial share of global container traffic between Asia, Europe and the Middle East. Since late 2023, security concerns around the Bab el-Mandeb strait have compelled carriers to divert vessels southward, with ripple effects extending far beyond the strait itself. Industry estimates suggest that rerouting around the Cape of Good Hope adds roughly two weeks to transit times and hundreds of thousands of dollars in additional fuel costs per voyage. Those costs translate into higher freight rates and steeper insurance premiums, ultimately squeezing food prices and industrial supply chains in economies along both coasts.

For ports in East Africa and the Gulf, the disruption has been simultaneously a pressure and a strategic opening. Facilities at Mombasa, Dar es Salaam and Djibouti have seen significant shifts in call patterns and cargo volumes as carriers reorganize their networks. Gulf hubs, particularly in the UAE, have had to adapt scheduling and warehousing capacity to accommodate new routing configurations. The question is no longer whether ports can absorb the shock. It is which ones can turn the reconfiguration into lasting competitive advantage.

The scale of the rerouting has been considerable. According to shipping analytics firms cited by Reuters, the share of Asia-Europe container traffic bypassing the Red Sea rose sharply from 2024, with several major liner operators suspending Red Sea transits indefinitely. That volume has to go somewhere, and the ports best positioned to capture it are those already investing in capacity and digital readiness.

How African and Gulf Port Operators Are Adapting

What distinguishes this period from previous disruptions is the pace at which port authorities and logistics firms across Africa and the Middle East have moved to innovate rather than simply react. Port management teams in East Africa have accelerated the digitalization of customs clearance, reducing dwell times and improving berth utilization to handle unpredictable call patterns. Several facilities have also expanded hinterland connectivity, investing in inland container depots and rail links to reduce congestion when vessel surges arrive.

In the Gulf, logistics operators have drawn on existing digital infrastructure to offer dynamic routing and cargo tracking services now in higher demand precisely because of the uncertainty that diversions introduce. Dubai’s position as a transshipment hub has given it particular flexibility: its port authority has adjusted scheduling windows and storage allocations to accommodate carriers rethinking their network designs. Saudi facilities at Jeddah and Dammam have similarly moved to enhance throughput capacity and speed up customs processing.

Logistics technology firms based in Nairobi, Lagos and Dubai are seeing growing interest in their products. Route optimization platforms and real-time cargo visibility tools have found new clients among freight forwarders and importers navigating cost and timeline uncertainty, according to reporting by Disrupt Africa and Wamda covering the regional startup space. This demand has accelerated both product development and fundraising for several of these companies, reinforcing a broader trend of logistics tech maturation across the Africa-Middle East corridor.

Insurance and trade finance present another dimension of the story. Maritime insurance premiums for Red Sea transit rose sharply after disruptions intensified, prompting some African traders to explore alternative risk-sharing arrangements. Regional development finance providers, including the African Development Bank, have examined how to support smaller traders most exposed to freight cost volatility, with some analysts calling for dedicated liquidity facilities linked to route disruption events. Carriers, meanwhile, have split between adding security surcharges and absorbing rerouting costs to retain long-term commercial relationships with African ports.

Long-Term Implications for the Africa-Middle East Corridor

The medium-term implications extend well beyond shipping timetables. African ports that adapt successfully stand to consolidate their roles as regional gateways and transshipment centers. The African Development Bank has argued in its infrastructure publications that port modernization can catalyze broader industrial growth by reducing logistics costs for manufacturers and agribusinesses. A sustained increase in traffic through East African facilities could therefore accelerate investment in adjacent activities such as cold chain logistics, warehousing and light processing.

For Gulf port operators, the disruptions have reinforced the strategic value of their geographic position as connectivity nodes between Asia, Africa and Europe. State-backed operators in the UAE and Saudi Arabia have used the period to deepen partnerships with African port authorities, including concession agreements and technical assistance arrangements that extend Gulf logistics expertise into Africa’s growing markets. These partnerships, when structured equitably, combine Gulf capital with African market access in ways that benefit both sides.

What the Red Sea episode has demonstrated is that the Africa-Middle East maritime corridor is not a passive conduit for global trade. It is a space where port executives, logistics entrepreneurs and trade finance professionals are actively shaping new patterns of connectivity. The disruption has accelerated cross-regional cooperation that calmer periods might have left unresolved, and the infrastructure investments now underway are unlikely to be reversed when the geopolitical situation eventually shifts.

Ports that have used the interval to build digital capacity, diversify their service offerings and lock in new commercial relationships are likely to emerge better positioned regardless of which route ultimately dominates global container flows. The Cape of Good Hope detour may prove temporary; the competitive reshaping of the Africa-Middle East logistics landscape is not.

Read more

After Canal+ Takes MultiChoice, African Creators and MENA Platforms Seize Their Moment

Comments (0) Business, Featured

On 10 July 2026, Canal+ officially completed its takeover of MultiChoice Group, bringing the operator of DStv, GOtv and Showmax under full French ownership after a process that stretched more than two years. The deal valued MultiChoice at roughly 55 billion South African rand, or approximately $3 billion, and came with public interest commitments of nearly R26 billion over three years to cover local content investment and support for historically disadvantaged businesses in the audiovisual sector, according to New African Magazine. Canal+ now holds a dominant pay-TV and streaming position across more than 50 African markets.

Yet the transition is already generating turbulence beneath the corporate headline. MultiChoice had launched Showmax in 2015 as an African-born competitor to Netflix, but the platform accumulated losses of $522 million between 2023 and 2025. Canal+ has signaled it will sunset Showmax as part of a broader plan to cut approximately $479 million in costs across the combined business by 2030, per Techpoint Africa. For Nigerian, South African and Kenyan producers who had relied on Showmax commissions, the practical question is immediate: where do their next financing and distribution deals come from?

The answer arrives from two directions at once: locally built streaming platforms and inbound commercial interest from Middle Eastern operators.

 Bets on Itself with Kava

The most visible homegrown response to the shifting landscape is Kava, a streaming platform launched in August 2025 by two of Nollywood’s most recognized institutions: Inkblot Studios, behind a string of Nigerian box office hits, and Filmhouse Group, West Africa’s largest cinema chain. The platform debuted with more than 30 premium Nollywood titles, offering subscribers exclusive post-theatrical releases and a schedule of weekly additions.

“Kava is more than a streaming service. It’s a bold new chapter for Nollywood, designed to meet the growing demand for premium, authentic African content,” the founders said in a statement reported by TechCabal. The ambition is to do what no African-led platform has yet managed: turn local storytelling into a globally sustainable streaming business.

The underlying numbers support that aspiration. Nigeria’s over-the-top video market is projected to reach $1.22 billion in 2025, according to data cited by TechCabal, while Africa’s broader subscription video-on-demand sector is forecast to grow from $2.71 billion in 2024 to $3.67 billion by 2027, according to Statista. The challenge Kava faces is that the platforms best placed to monetize that growth have historically been non-African: Netflix and Amazon Prime both poured resources into Nigerian content before scaling back acquisition budgets, citing low subscriber penetration. IrokoTV, an earlier attempt at a dedicated Nollywood platform, exited the Nigerian market entirely.

Kava’s founders argue their advantage lies in owning both production infrastructure and distribution, rather than licensing content from studios that retain leverage. Whether that vertical integration proves durable will be one of the sector’s defining tests over the next two years.

MENA Operators Look South for African Content

While African platforms push outward for global audiences, operators from the Middle East are moving in the opposite direction. Media World, a content aggregator and mobile services platform with client telecoms including Zain Iraq and Jawwal Palestine, has recently opened a Lagos office, its first in sub-Saharan Africa. Speaking at the Telemedia Johannesburg 2026 conference, the company’s content acquisition and partnership manager Samer Al Ramahi described the company as being “on the hunt for partnerships to integrate various services like games, esports, and streaming content” from African providers, with the goal of distributing them as white-label products across its MENA footprint, per Telemedia Magazine.

The broader context for that scouting trip is a MENA streaming market that is growing fast and competing fiercely for differentiated content. MBC Group’s Shahid platform reported a 28.2% year-on-year revenue rise in 2025, boosted partly by a first-of-its-kind bundling deal with Netflix in Saudi Arabia and the wider MENA region, according to Variety. As established MENA players scale up, African genres represent both a new content category and an access point to diaspora communities with purchasing power.

Music offers the clearest proof of that audience appetite. Afrobeats listeners grew 22% globally in 2025, according to Spotify’s annual Wrapped report, cited by Techpoint Africa, with Nigerian and South African artists dominating Africa’s most-streamed lists. Gulf touring and licensing activity by African artists has expanded in parallel, building the audience base that streaming and gaming platforms want to monetize.

Africa’s Cross-Regional Content Market Takes Shape

The convergence of these forces, Canal+’s restructuring of Africa’s legacy pay-TV market, the emergence of African-owned streaming platforms and the commercial scouting of MENA aggregators in Lagos and Johannesburg, points to a realignment that is real but still unresolved. The players are in motion; the rules of the new ecosystem are not yet written.

For African creators, the proliferation of potential distribution channels is genuine progress. For investors, the question of which platform model generates sustainable returns remains open. Fragmentation is a risk: multiple smaller platforms competing for overlapping catalog rights and the same subscriber budgets could dilute rather than build value. For MENA operators, Africa offers differentiation and scale, alongside regulatory complexity and the challenge of building content curation expertise far from home.

What is already clear is that Africa’s screen industry is no longer organized around a single dominant gatekeeper. From Kava’s Nollywood catalog to Media World’s Lagos outpost, the architecture of a new cross-regional content economy is being laid. How quickly it coheres, and whose terms it operates on, will shape the careers of African filmmakers, the strategies of Gulf platforms and the viewing habits of audiences from Accra to Riyadh over the coming decade.

Read more

African AI startups tap Gulf cloud and capital to scale regionally

Comments (0) Business, Featured

Africa’s AI Boom Runs Into a Compute Wall

Africa’s artificial intelligence sector has expanded sharply over the past five years. Startups in Nigeria, Kenya, South Africa and Egypt are applying machine learning to healthcare diagnostics, agricultural yield prediction, credit scoring and logistics optimization, reaching users across multiple African markets from relatively modest bases.

Yet growth has run into a practical ceiling: compute power. Training and deploying AI models demands access to graphics processing units and large-scale cloud infrastructure, which remains expensive, scarce or high-latency across most of the continent. A 2023 report by the International Finance Corporation noted that inadequate digital infrastructure, including unreliable power supply and limited local data center capacity, continues to be a primary constraint on the competitiveness of African technology firms. This is not a peripheral concern. It directly shapes what kinds of AI products are feasible to build, operate and scale locally.

The result is a gap that African founders know well. Their applications are often among the most contextually relevant anywhere, designed around smallholder farmers, informal traders and populations with no formal credit history. But many of the most compute-intensive workloads still run on infrastructure in Europe or North America, adding latency and cost while raising questions about where user data actually resides.

Gulf States Build the Infrastructure Africa Needs

While African AI companies have searched for alternatives, the Gulf has become one of the world’s most active builders of AI-ready infrastructure. The United Arab Emirates launched its National AI Strategy 2031, committing to becoming a global hub for AI talent, research and deployment. Abu Dhabi-based G42, one of the most prominent AI holding companies in the Global South, has secured major partnerships with Microsoft and OpenAI, while positioning itself as a bridge between Gulf capital and emerging-market applications. Saudi Arabia established its Saudi Data and Artificial Intelligence Authority, known as SDAIA, in 2019 as a cornerstone of Vision 2030, and the kingdom now hosts cloud regions from major hyperscalers including Amazon Web Services and Microsoft Azure.

The scale of these investments is substantial. Both the UAE and Saudi Arabia have committed or attracted tens of billions of dollars to AI and cloud infrastructure over the past three years, according to official government communications from their respective AI and investment authorities. Critically, neither government frames this purely as a domestic modernization project. Official strategies explicitly reference the broader Global South as a partner market, an acknowledgment that Gulf AI ambitions require use cases, data sets and talent ecosystems that extend well beyond their own relatively small domestic populations.

For African startups, this creates a genuine opening. Gulf cloud regions offer lower latency than European equivalents for workloads routed through East or North Africa. Gulf-based venture vehicles and sovereign funds are actively seeking exposure to high-growth but still under-served markets. And Gulf governments are establishing accelerator programs and co-investment frameworks that bring African founders into direct contact with regional infrastructure partners. The Africa-Gulf digital corridor, still in its early stages, is beginning to function as a practical alternative to the transatlantic infrastructure dependency that has defined African tech since the sector emerged.

Data Sovereignty and Investment Terms in the Africa-Gulf Corridor

The emergence of this corridor raises issues that African founders, regulators and civil society actors are only beginning to address. Data sovereignty is the most immediate. When an African healthtech company stores patient records in a data center in Abu Dhabi or Riyadh, it enters a different legal jurisdiction, one whose data protection frameworks may not align with the legislation being developed in Nigeria, Kenya or South Africa. Several African countries have passed or are drafting data protection laws inspired by the European Union’s General Data Protection Regulation, but cross-border enforcement mechanisms remain underdeveloped.

Equity in investment terms is another layer of complexity. Gulf capital is often patient and comes with strategic rather than purely financial objectives, which can suit African startups that struggle with the short exit timelines demanded by some venture funds. But it also introduces governance considerations around board composition, founder dilution and exit conditions that require careful negotiation. African startup associations have begun calling for standardized term sheets and greater investor education to ensure that cross-regional capital flows on balanced terms.

On the Gulf side, fund managers are learning to assess African market risks, regulatory complexity and currency dynamics. Knowledge that transfers readily within the Middle East does not always apply in Lagos, Nairobi or Accra. Several Gulf-based accelerators have responded by embedding Africa-focused programs and partnering with established African tech hubs to build this expertise from the ground up.

The underlying logic of the corridor is coherent: African markets supply use cases, talent and demographic reach, while Gulf partners bring infrastructure, institutional capital and access to global technology alliances. Translating that logic into durable, equitable commercial arrangements is the practical work now underway. How well African and Gulf actors manage it will shape not only the competitiveness of individual companies, but the terms on which both regions contribute to the global AI economy in the years ahead.

Read more

African Agritech Startups Reshape How the Gulf Secures Its Food Supply

Comments (0) Business, Featured

Kenyan smallholder farmer using mobile agritech platform in field

A Strategic Rethink of Food Import Dependency

Gulf states import between 80 and 90 percent of their food, according to the Food and Agriculture Organization of the United Nations, making them acutely sensitive to disruptions in global supply chains. The pressures of recent years, from the COVID-19 pandemic to the war in Ukraine and its cascading effects on grain exports, have pushed food security to the top of policy agendas in Riyadh, Abu Dhabi and Doha. Traditional responses centered on securing land abroad or locking in long-term commodity contracts with established agricultural exporters. That approach is now giving way to technology-driven partnerships with African agritech companies.

Sovereign investors and state food security agencies across the Gulf Cooperation Council are increasingly directing attention toward African agritech, where startups are building digital infrastructure for farm finance and supply-chain traceability. The African Development Bank estimates that the financing gap for smallholder farmers across Africa exceeds 100 billion dollars annually, a structural deficit that digital platforms are beginning to address by connecting producers to credit and direct market access. For Gulf importers seeking resilient supply chains, these platforms offer not just commodity access but embedded relationships with agricultural ecosystems that are still expanding.

How African Founders Are Positioning Their Companies

The agritech sector across sub-Saharan and North Africa has expanded substantially over the past decade. Startups operating in Kenya, Nigeria, Morocco and Ghana have built platforms that aggregate smallholder supply, deliver mobile-based advisory services, and link farmers directly to export buyers through digitized logistics. African Development Bank data on agricultural finance indicates that digital tools measurably improve access to credit and reduce post-harvest losses in the markets where they have scaled. These are precisely the metrics that attract Gulf food security planners looking for supply partners capable of guaranteeing volume and provenance.

What is changing now is the nature of the capital entering the sector. Gulf sovereign wealth funds have historically invested in African infrastructure, real estate and energy. Their move toward agritech represents a more nuanced calculation: rather than owning farmland outright, they are backing the digital layers that sit above it, funding platforms that improve productivity and logistics without requiring direct land management. For African founders, this shift carries measurable commercial consequences. Access to Gulf distribution networks and government procurement contracts can transform a regional platform into a continental export hub.

Morocco offers a useful illustration of how this dynamic plays out in practice. Its position as a net agricultural exporter with a developed agro-processing sector, anchored by the government’s long-running Green Morocco Plan, has made it an early point of engagement for Gulf food investors. Moroccan producer networks supplying citrus, tomatoes and olives to Gulf markets have progressively adopted traceability and quality management systems, partly in response to import standards set by Gulf state food agencies. The digital infrastructure underlying that compliance was largely built by domestic and pan-African technology firms, not external contractors.

Capital and Governance: Data Sovereignty in Africa-Gulf Agritech Partnerships

The economic logic of these partnerships is clear enough. Less obvious, but equally significant, are the governance questions they carry. When a Gulf sovereign fund takes a stake in an African agritech platform, it acquires both a financial interest and a degree of influence over how that platform develops its services, sets pricing and manages farmer data. African founders and cooperative leaders are increasingly aware of this dimension. Some are structuring deals with explicit protections for local decision-making and data sovereignty, framing those clauses not as obstacles to investment but as conditions for long-term sustainability.

The African Continental Free Trade Area, which entered its operational phase in 2021, adds another layer of opportunity to this equation. As intra-African trade in agricultural goods deepens, the agritech platforms being built today may serve as the connective tissue of a new regional food system, one that links producers in East Africa to processors in West Africa and export hubs in North Africa before reaching Gulf markets. Gulf investment that funds this infrastructure now could gain privileged access to supply chains considerably larger in scale within a decade.

For smallholder cooperatives, the value of these partnerships ultimately depends on terms. Price transparency and data access rights are as consequential as the headline investment figure. Several African agritech companies have publicly emphasized co-ownership models and revenue-sharing structures as a way to distinguish their approach from platforms that capture data without redistributing value. Whether Gulf investors accept those terms at scale will be a defining question for the sector over the next few years.

The trajectory of African agritech and Gulf food security is, in the end, a story about two sets of actors each managing structural vulnerabilities through technology and negotiated partnership. African founders and their farmer networks are building systems designed to outlast any single investor relationship. Gulf food security agencies are seeking supply-chain resilience that no single commodity contract can provide. Where those interests align with equitable terms, the partnerships forming now may prove among the most durable economic ties linking the two regions.

Read more

Gulf Capital Goes Green in Africa

Comments (0) Featured, Politics

African climate startup founders at a Gulf investment forum in Dubai

The adaptation finance gap at the heart of African development

Africa’s climate paradox is well documented, but its economic consequences remain underestimated outside the region. The continent produces less than 4 percent of global greenhouse gas emissions, according to the Intergovernmental Panel on Climate Change, yet it absorbs a disproportionate share of climate-related costs. Drought patterns in the Horn of Africa and recurrent flooding across West and Central Africa translate into direct losses in agricultural output and eroded infrastructure investment. The African Development Bank (AfDB) has estimated that Africa requires roughly $1.3 trillion in climate finance between 2020 and 2030, or about $130 billion annually, to adequately address adaptation and mitigation combined. Actual flows remain far below that figure.

This gap has defined African negotiating positions at successive UN climate conferences. Delegations at COP27 in Sharm el-Sheikh and COP28 in Dubai consistently argued that existing mechanisms favour mitigation over adaptation and that pledges from wealthier nations have not materialized on schedule. The loss-and-damage fund agreed at COP27 represents a partial response, but its initial capitalization is limited relative to need. For many African governments and innovators, the political conclusion is clear: depending solely on traditional development finance channels is not sufficient.

Gulf capital and African climate needs: a convergence under way

Gulf states, driven by large-scale economic diversification programs, are redirecting sovereign wealth toward sectors with long-term returns. Climate-relevant infrastructure and technology increasingly fit that profile. Saudi Arabia’s Public Investment Fund, which manages assets exceeding $700 billion, has stated public commitments to sustainability and clean energy. Abu Dhabi’s Mubadala Investment Company and ADQ have pursued Africa-facing strategies in infrastructure and food security, two areas directly intersected by climate risk. The Abu Dhabi Fund for Development, a bilateral development institution, has financed adaptation-related agricultural and water projects across the continent.

The UAE’s hosting of COP28 in Dubai in December 2023 added institutional weight to this orientation. The conference produced a pledge of $30 billion for the ALTÉRRA climate fund, anchored in Abu Dhabi, with a stated aim of mobilizing up to $250 billion in global climate finance by 2030. A portion of ALTÉRRA’s mandate explicitly targets investments in climate solutions in emerging markets, Africa included. While full deployment depends on deal flow and institutional capacity, the fund’s creation is a concrete new vehicle through which Gulf resources could reach African climate innovators, rather than simply circulating within established Northern finance networks.

The African side is not passive. The AfDB and the Global Center on Adaptation jointly launched the Africa Adaptation Acceleration Program, targeting $25 billion by 2025. Startups working in climate-smart agriculture and off-grid renewable energy have grown across hubs in Nairobi and Lagos. Several are not executing donor-funded pilots but building revenue-generating businesses that need growth capital, not grants.

What South-South finance means in practice

The convergence of Gulf capital and African adaptation demand does not happen automatically. It requires institutional intermediaries and governance frameworks attuned to local conditions, as well as tools to bridge very different expectations about risk and return.

Blended finance structures, in which a development institution de-risks an initial tranche to attract private capital, have become a standard tool in this space. Gulf and African development banks are collaborating on such facilities in agriculture and water infrastructure. Co-investment between Gulf family offices and African venture funds is also growing in agritech and climate data services, driven partly by diaspora networks connecting the two regions. Dubai and Abu Dhabi, which have attracted a significant number of African startup founders and executives, serve as informal nodes where relationships form before they become formal transactions.

The logic of this South-South axis differs from that of traditional Western climate donors. Gulf investors are commercial actors with explicit return expectations, which means African climate startups must demonstrate revenue models and scalability rather than simply qualifying under humanitarian criteria. That pressure can sharpen business thinking. It also risks sidelining adaptation projects whose returns are social and systemic rather than directly financial, a tension that African policymakers and regional institutions will need to manage deliberately.

Building durable structures for Africa-Gulf climate finance

The Africa-Gulf climate finance relationship is still being structured, and several governance questions remain open. How will African governments and civil society shape the allocation of Gulf-backed climate capital? What norms will govern procurement and local employment? How will technology transfer be structured so that domestic private sectors capture lasting economic value?

These questions carry particular weight given the scale of sovereign assets involved. African regional institutions, from the AfDB to bodies under the African Union’s development agenda, have a role in setting frameworks that maximize local benefit. Without that architecture, even substantial capital flows can pass through without building the adaptation capacity the continent needs.

For African climate innovators, the opportunity is tangible. The combination of Gulf capital and growing diaspora networks creates a genuine opening that did not exist a decade ago. Whether it consolidates into a durable South-South finance axis or remains a series of disconnected deals will depend on the institutional bridges that African and Gulf stakeholders are prepared to build together, and on who holds the pen when those frameworks are written.

Read more

Gulf Capital Reshapes Africa’s Alliances

Comments (0) Business, Featured

Africa’s Debt Mountain and the Gulf’s Growing Role

Over the past decade, African sovereign debt expanded significantly. Public debt ratios climbed above 60 percent of GDP in a number of sub-Saharan countries by the early 2020s, according to IMF Regional Economic Outlook data, driven by infrastructure borrowing, pandemic response spending, and the rising cost of refinancing older loans. Several countries found themselves in debt distress or at high risk of it.

Ghana suspended external debt payments in late 2022 and entered formal restructuring; Zambia had defaulted in 2020, the first African country to do so during the pandemic; Ethiopia followed in 2023. Each case triggered negotiations under the G20’s Common Framework, a mechanism designed to coordinate debt treatment across official bilateral creditors, including Chinese policy banks and Gulf development funds, alongside multilateral lenders such as the IMF and World Bank.

What distinguishes the current cycle from earlier African debt crises is the breadth of the creditor base. Traditional Paris Club lenders now sit alongside Gulf development funds and private bondholders at the same negotiating tables. This fragmentation has slowed restructuring timelines considerably. The Zambian process took several years to reach a preliminary creditor agreement, partly because aligning Chinese and Western creditors on comparable terms proved far more complex than previous rounds of Club negotiations.

Gulf States as Creditors and Strategic Investors in Africa

Gulf involvement in African sovereign finance takes multiple forms. The Saudi Fund for Development and the Abu Dhabi Fund for Development have extended bilateral loans to African governments for infrastructure projects, energy installations, and budget support. These loans, while often concessional, do not always fall under the Common Framework’s umbrella, creating ambiguity about how they factor into restructuring scenarios. More recently, Gulf sovereign wealth funds, including the Abu Dhabi Investment Authority and Saudi Arabia’s Public Investment Fund, have moved into equity-style investments, acquiring stakes in African ports, energy projects, and agribusiness assets.

This dual role, as both creditor and investor, gives Gulf states a distinctive position in African debt diplomacy. When an African government seeks a debt standstill or reduced repayment schedule, it must negotiate not only with private bond committees and the IMF but also with bilateral partners whose cooperation can unlock or block a deal. Gulf states, meanwhile, have an interest in maintaining access to African markets and strategic infrastructure, which means they often prefer restructuring over default. The result is a calculus in which debt relief and new investment become intertwined: a restructuring agreement may arrive packaged with a fresh infrastructure commitment or a port concession, effectively converting debt exposure into long-term physical presence.

This pattern was documented across several African countries by 2024, as reported by The Africa Report and Reuters Africa. For African governments, such arrangements can mobilize capital that domestic budgets are unable to provide. The trade-offs involve questions of transparency, governance quality, and the long-term terms under which strategic assets are managed.

African Negotiators Building Leverage in Debt Talks

A common misconception frames these negotiations as inherently one-sided. Research by economists at the African Development Bank and the Overseas Development Institute points to a more layered reality. African finance ministries have built substantial technical capacity over the past decade, supported by IMF technical assistance and regional peer learning. Countries like Ghana and Zambia entered restructuring with clearly stated fiscal targets, domestic debt exchange programs, and structured public communications designed to manage market expectations while maintaining political legitimacy at home.

The growth of local-currency bond markets adds another dimension of leverage. Several African countries have deepened domestic debt markets, issuing bonds purchased largely by domestic banks and pension funds. This reduces, though does not eliminate, exposure to external creditor pressure. The African Development Bank’s 2023 African Economic Outlook noted that domestic resource mobilization was gaining traction in markets from Kenya to Côte d’Ivoire, as governments sought to diversify away from expensive Eurobond issuances subject to global rate volatility.

At the multilateral level, African governments have increasingly coordinated positions through the African Union and regional economic communities. Calls for accelerated Common Framework timelines and clearer rules on comparability of treatment across creditor classes have come directly from African finance ministers, who have pointed to the economic cost of prolonged restructuring uncertainty. This assertiveness signals a broader shift: a move from reactive accommodation toward deliberate positioning in global financial governance debates.

Development Stakes and the Long-Term Regional Balance

The resolution, or prolonged absence of resolution, of Africa’s sovereign debt challenges has direct consequences for the continent’s development capacity. With more than 60 percent of Africa’s population under the age of 25, according to African Union data, the need for public investment in education, health, and transport infrastructure is pressing. The IMF has documented cases in which African countries spend more on external debt servicing than on health budgets, a fiscal reality that limits governments’ ability to act as engines of social investment and long-term growth.

For Gulf states, the stakes run differently. Their African debt and investment portfolios are embedded in broader strategic visions: Saudi Arabia’s Vision 2030 and the UAE’s economic diversification roadmap both treat African markets as significant long-term frontiers for capital. Maintaining a reputation as credible, transparent partners is not merely a reputational consideration; it is a precondition for the commercial access and political relationships those visions require.

The architecture of African debt diplomacy now taking shape, in which Gulf capital, Chinese lending, multilateral conditionality, and African negotiating capacity all interact, will likely influence the continent’s development trajectory well into the 2030s. For investors, policymakers, and citizens across both regions, understanding who holds leverage, how it is exercised, and how African leaders navigate the resulting constraints is a practical question. It shapes what infrastructure gets financed, what fiscal space governments retain, and how resilient economies prove when the next global shock arrives.

Photo : modeldiplomat.com

Read more

Kinshasa to host a major GSAD Africa session in August 2026

Comments (0) Business, Featured

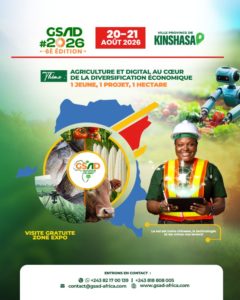
Africa’s agricultural sector is undergoing a profound transformation. Digital tools, innovative startups and new investment models are changing how farmers produce, manage and sell their crops. In this context, the Grand Salon de l’Agribusiness et du Digital en Afrique (GSAD Africa) has become a key platform bringing together the actors shaping the future of agriculture on the continent.

The next major session will take place 20–21 August 2026 in Kinshasa, Democratic Republic of Congo. This edition is expected to attract a wide range of participants from across Africa and beyond, including entrepreneurs, farmers, agribusiness companies, investors, policymakers, researchers and technology experts.

Kinshasa, one of Africa’s largest cities and an important economic hub in Central Africa, provides a strategic location for discussions on agricultural development and digital transformation. The event aims to highlight the opportunities offered by technology to improve agricultural productivity, strengthen food security and develop competitive agricultural value chains.

The GSAD Africa sessions are known for their strong focus on collaboration. By bringing together public institutions, private companies and startups, the event creates a space where ideas, partnerships and investment opportunities can emerge. Young innovators developing AgriTech solutions will have the opportunity to present their projects alongside established agribusiness leaders.

International organizations, development institutions and financial actors are also expected to participate, reflecting the growing global interest in African agriculture as a sector with enormous economic potential.

A dynamic program for innovation, startups and investment

Over two days, the Kinshasa edition of GSAD Africa will feature a rich and dynamic program designed to encourage dialogue and collaboration.

The event will include conferences and roundtable discussions focused on major themes shaping the future of agriculture. Topics are expected to include digital platforms for agricultural markets, the role of artificial intelligence and satellite data in crop monitoring, climate-resilient agriculture, and innovative financing models for farmers and agricultural entrepreneurs.

Another highlight of the program will be the startup and innovation sessions. These sessions will showcase young African entrepreneurs developing technological solutions for agriculture, from mobile applications providing market information to digital tools for farm management, traceability and logistics.

Pitch sessions will give startups the opportunity to present their projects to investors, accelerators and potential partners. For many early-stage companies, this type of exposure can be crucial for securing funding and building strategic collaborations.

The exhibition space will also allow companies and organizations to present new agricultural technologies, digital services and innovative equipment. Participants will be able to discover tools designed to improve productivity, reduce post-harvest losses and strengthen agricultural supply chains.

Networking will play a central role throughout the event. Informal meetings, business sessions and collaborative workshops will help participants connect, exchange ideas and explore potential partnerships.

How to participate

Participation in the GSAD Africa Kinshasa session (20–21 August 2026) is open to entrepreneurs, investors, farmers, researchers, students and professionals interested in agribusiness and digital innovation.

Registration details, partnership opportunities and program updates are available through the official GSAD Africa platform and event organizers. Early registration is recommended, as the event is expected to attract a large number of participants from across the African agribusiness ecosystem.

With its focus on innovation, entrepreneurship and investment, the Kinshasa session of GSAD Africa promises to be one of the key gatherings for anyone interested in the future of agriculture on the continent.

Photos : facebook.com/GSAD2024

Read more