Business
Category

AfCFTA’s digital trade protocol: how African and MENA startups are shaping the rules

Comments (0) Business

AfCFTA Phase II: From Guided Trade to a Digital Framework

AfCFTA entered into force in May 2019 and launched its first Guided Trade Initiative in October 2022, when eight pioneer countries, including Ghana, Kenya, Rwanda and Tanzania, began exchanging goods under preferential tariff arrangements. That milestone, overseen by the AfCFTA Secretariat in Accra under Secretary-General Wamkele Mene, demonstrated that the agreement could move from text to practice. The harder negotiation was just beginning: the Phase II protocols covering services, investment, intellectual property, competition policy and digital trade.

Of these, the digital trade protocol has attracted the most sustained attention from tech entrepreneurs and investors. AfCFTA spans 54 African Union member states, a combined GDP of roughly $3.4 trillion and a population of 1.3 billion people. If the protocol delivers a coherent regulatory framework for cross-border digital services, it could transform the operating environment for fintechs, e-commerce platforms, enterprise software vendors and cloud providers across the continent. The alternative, a continued patchwork of national rules, keeps transaction costs elevated and forces startups to navigate 54 separate licensing regimes before reaching a pan-African customer base.

The provisions under discussion address deeply practical concerns: data flows and localization requirements, the legal validity of electronic contracts, consumer protection standards for online transactions, cybersecurity cooperation and mutual recognition of digital service licenses. For a Lagos-based payment platform seeking to operate in Dakar, or a Casablanca SaaS firm expanding into Abidjan, these provisions determine the actual cost and feasibility of cross-border growth.

How AfCFTA’s Digital Protocol Would Reshape Startup Operations

The stakes appear clearly in day-to-day business decisions. A mobile-money operator licensed in one AfCFTA country that wants to enable transfers to users in a neighboring state typically faces separate licensing requirements, distinct know-your-customer rules and differing data-residency obligations in each jurisdiction. A harmonized protocol could replace that burden with mutual recognition arrangements or unified compliance standards, substantially cutting the cost of serving multiple markets from a single regulatory base.

Similar logic applies across the digital economy. E-commerce platforms managing cross-border payments and returns, SaaS companies billing corporate clients in multiple African countries, and streaming services distributing content across the continent all share a direct interest in predictable, interoperable rules. A 2020 report by Google and the International Finance Corporation estimated that Africa’s internet economy could reach $180 billion by 2025, roughly 5.2 percent of continental GDP, provided that enabling regulatory conditions were in place. Regulatory coherence for digital services was a central enabling condition that report identified.

African startup associations and continental industry bodies have been feeding into AfCFTA’s technical working groups. Afrilabs, which connects tech hubs in over 50 African countries, and the AfCFTA Business Network have each submitted position papers calling for harmonized licensing for digital financial services, clear data portability standards and consumer protection rules that do not impose disproportionate compliance costs on early-stage companies. How much of that input finds its way into the final text will signal whether AfCFTA genuinely serves the commercial logic of its intended beneficiaries.

Gulf Capital and MENA Investors in AfCFTA Digital Negotiations

AfCFTA’s digital trade negotiations are not purely an intra-African affair. Investors and platforms from the Middle East and North Africa have become significant actors in African tech ecosystems, and the rules that emerge from Accra will shape the conditions under which their capital and products operate.

Gulf-based venture funds active in African tech, including Saudi Arabia’s STV and several UAE-based early-stage investors, have backed startups in fintech, logistics and enterprise software whose value propositions depend on cross-border scalability within Africa. For these investors, AfCFTA’s digital protocol functions as a macro variable in portfolio strategy: a harmonized continental market supports higher valuations and more ambitious growth targets; regulatory fragmentation does the opposite.

Egypt occupies a particularly significant position in this dynamic. As both an African Union member and a major MENA tech hub, Cairo-based startups are natural candidates for pan-African expansion under AfCFTA, while also serving as conduits for Gulf capital entering sub-Saharan markets. Egypt’s engagement in Phase II negotiations may carry outsized influence on whether MENA-oriented commercial interests are reflected in the final digital trade framework.

There is also a regulatory-model dimension worth tracking. The UAE has built sandbox and licensing frameworks for digital finance that African regulators frequently reference as benchmarks. If AfCFTA’s emerging digital rules align with frameworks familiar to Gulf-based companies, it will reduce friction for cross-regional commerce. Significant divergence risks fragmenting the South-South digital corridor that investors on both sides are actively trying to build.

AfCFTA Digital Protocol: Implementation Pace and the Tech Growth Stakes

AfCFTA’s digital protocol is emerging as a central institutional test for Africa’s tech economy over the next several years. The Secretariat has identified digital trade as a stated priority for Phase II, and the growing involvement of private-sector bodies in technical consultations reflects an openness to commercial input that was less visible in the agreement’s foundational stages.

The open question is pace. AfCFTA’s implementation record shows a persistent gap between the ambition of signed texts and the operational reality of enacted rules. Translating the digital protocol from a negotiated agreement into ratified, domestically implemented legislation will require not only political will but also significant capacity-building for national regulators, many of whom lack dedicated digital trade expertise. For African founders and MENA investors watching closely, the question is whether the protocol will arrive in time to shape the continent’s next generation of tech growth, or whether companies will have already engineered their own workarounds long before the rules come into force.
Read more

From PAPSS to Buna: How Afro-Arab payment rails are redrawing the regional finance map

Comments (0) Business

How PAPSS and Buna are building Africa-Arab payment infrastructure

Two regional payment platforms are building the rails for a new financial geography connecting Africa and the Arab world. On the African side, the Pan-African Payment and Settlement System (PAPSS), launched by Afreximbank, enables cross-border transactions in local African currencies, bypassing the correspondent banking routes that typically run through New York or London. On the Arab side, the Buna platform, operated by the Arab Monetary Fund, functions as a multi-currency payment and settlement system designed to serve Arab and neighboring markets.

Each platform was built independently to address similar structural problems: high transaction costs, slow settlement, and dependence on external financial infrastructure. But as trade and remittance flows between Africa and the Gulf deepen, the case for connecting these two systems grows more pressing. The question is no longer whether integration is desirable, but how fast institutional momentum can build.

Remittance costs and the Africa-Gulf integration case

The economic stakes are substantial. According to World Bank data, remittance inflows to Sub-Saharan Africa amount to tens of billions of dollars each year. Egypt alone, one of the region’s largest recipients, has historically received tens of billions in annual remittances, with a major share originating from workers in Saudi Arabia, the UAE, and Kuwait. A significant portion of these flows still travels through costly legacy channels.

The World Bank has documented that Sub-Saharan Africa consistently pays the highest remittance transaction costs of any global region, often exceeding 7 to 8 percent per transaction on certain corridors. Reducing those costs by even a few percentage points would translate into hundreds of millions of dollars annually returned to African households rather than absorbed by intermediaries. For migrant workers in the Gulf, many employed in construction and domestic services, the difference registers directly on monthly budgets.

Cross-border trade compounds this dynamic. Analyses from UNCTAD and regional development banks have consistently shown that GCC-Africa trade volumes grew throughout the decade preceding 2024, spanning food imports, energy, construction materials, and manufactured goods. As volumes rise, businesses on both sides increasingly demand faster, cheaper settlement options. The current architecture, which typically routes payments through third-country correspondent banks, adds both cost and time that erodes competitiveness.

Mobile money growth and the financial sovereignty case for integration

The convergence of technology trends on both sides of the corridor creates a distinctive opening. African mobile money ecosystems have reached real scale: Kenya and Ghana, among others, report that a majority of adults now hold mobile money accounts, with transaction volumes in some markets representing a significant share of GDP. Across the Gulf, digital payment adoption has accelerated under national payment modernization programs, and consumer expectations for speed and frictionless access have risen sharply.

This technical maturity shifts the conversation about Afro-Arab payment integration from aspiration toward implementation. PAPSS gives African central banks a mechanism to settle transactions in local currencies, reducing exposure to dollar fluctuations and the geopolitical risks tied to Western-controlled clearinghouses. Buna offers Arab economies an analogous layer of sovereignty over regional settlement. Connecting the two would extend this logic to cross-regional trade: a Senegalese exporter and an Emirati importer could, in principle, settle in their own currencies without routing through a third-country bank.

The sovereignty argument resonates in both regions for reasons that extend beyond fintech. Discussions about reducing dollar dependence in trade, reforming the global financial architecture, and building regional alternatives to correspondent banking have been active in both African and Arab policy circles. Payments integration sits at the practical core of these ambitions, giving technical projects a political weight that helps sustain institutional support.

Private fintech companies in Africa-Gulf payment corridors

While institutional platforms develop their frameworks, private fintech companies are already operating in the corridors that PAPSS and Buna aim to serve. Startups across West and East Africa facilitate remittances from the Gulf, competing on speed, mobile-first design, and lower fees compared to traditional money transfer operators. Middle Eastern payment gateways have begun targeting African merchant traffic as e-commerce volumes expand.

These private actors have a dual relationship with regional institutional rails. On one hand, platforms like PAPSS can provide settlement infrastructure that lowers the cost and complexity of running cross-border payment services, potentially enabling smaller fintechs to compete more effectively against incumbents. On the other hand, connecting private and institutional systems requires regulatory alignment. Central banks in both regions must establish frameworks governing how licensed fintechs access regional settlement layers, and how consumer protections apply across jurisdictions.

For entrepreneurs building in this space, the regulatory landscape matters at least as much as the technology stack. Founders of remittance platforms serving Gulf-to-Africa corridors consistently cite licensing complexity and currency controls as the primary constraints on growth, often more limiting than technical challenges. Progress on harmonized regulatory frameworks between African and Arab central banks would therefore have direct and immediate commercial consequences for the companies building in these corridors.

The long-term stakes of Afro-Arab payment integration

The long-term significance of Afro-Arab payment integration extends beyond efficiency gains for individual transactions. It represents a structural shift in how two regions with deep demographic and commercial ties manage financial sovereignty, and in how much value local actors can capture from cross-border flows rather than ceding it to external intermediaries.

Whether PAPSS and Buna converge formally, through a bilateral interoperability agreement between Afreximbank and the Arab Monetary Fund, or more gradually through shared technical standards and private-sector bridges, the direction of travel is clear. Each new corridor agreement, regulatory alignment, or commercial partnership narrows the distance between two platforms that were designed for distinct regions but increasingly serve the same flows.

For entrepreneurs, central bankers, and institutional architects building on these rails, the opportunity is real and the infrastructure is still taking shape. The actors who define the interoperability layer today will hold an outsized position in the regional payments economy for years to come.

Read more

African and Gulf Airlines Quietly Forge a New South-South Aviation Corridor

Comments (0) Business, Non classé

A network taking shape across the Indian Ocean corridor

Addis Ababa’s Bole International Airport has become the clearest emblem of this shift. Ethiopian Airlines, sub-Saharan Africa’s largest carrier by network reach, operates direct services to Dubai, Abu Dhabi, Jeddah and Riyadh, and carried more than ten million passengers annually in the years before the pandemic, according to the airline’s published performance data. Its recovery since 2021 has been brisk, and its Gulf routes rank among the most commercially significant in its network.

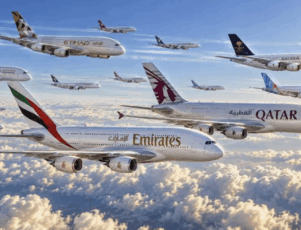
On the Gulf side, Emirates operates services to more than twenty African destinations, a figure confirmed by the carrier’s own route maps. Flydubai, its low-cost affiliate, has added secondary African cities, extending connectivity to markets that full-service carriers previously bypassed. Qatar Airways has historically maintained services to at least a dozen African cities, with East and West Africa both featuring prominently in its expansion plans. Collectively, these networks have materially changed the direct travel options available from Kigali, Harare or Zanzibar over the course of a decade.

The corridor is not uniform. East Africa’s connection to the Gulf is the most developed, built on decades of labor migration and trade flows linked to GCC states. West Africa has historically relied on European hubs, but carriers like Air Senegal, alongside Gulf entrants such as Flydubai and Air Arabia, are beginning to alter this balance. North Africa occupies a distinct position: Cairo serves simultaneously as an African and an Arab hub, while Morocco’s growing aviation sector has attracted Gulf investor attention alongside expanded direct services.

RwandAir illustrates the ambition of smaller African carriers in this space. By positioning Kigali as a continental transit hub with Gulf-facing routes, the airline has secured partnerships and codeshares that amplify its network well beyond what its home market alone could sustain. Air Senegal is pursuing a comparable logic from West Africa.

Cargo as a driver of Africa-Gulf corridor growth

Passenger numbers tend to dominate aviation headlines, but freight is an equally significant driver of corridor expansion. East Africa’s fresh flower and vegetable export economy depends almost entirely on reliable air freight, with Kenyan roses destined for Gulf retailers transiting through Nairobi’s Jomo Kenyatta International Airport on daily schedules. Ethiopian Airlines Cargo, one of the continent’s largest freight operators, has expanded its dedicated freighter capacity precisely to serve these high-value, time-sensitive flows.

The pandemic years reinforced cargo’s centrality in an unexpected way. When passenger planes were grounded, airlines discovered that dedicating freighters to medical supplies and essential goods on Africa-Gulf routes was both operationally necessary and commercially viable. That experience accelerated investment in cold-chain logistics, cargo terminal upgrades and direct freight partnerships. Gulf logistics operators, including those connected to Abu Dhabi’s and Dubai’s free-zone ecosystems, have since entered anchor agreements with African airport operators to handle growing volumes.

The direction of flow is not one-sided. Pharmaceuticals and manufactured goods moving from Gulf distribution hubs into African consumer markets are also reshaping cargo patterns. As African e-commerce platforms scale and regional supply chains tighten, demand for reliable direct air freight between Gulf distribution centers and African capitals is forecast to increase further, according to IATA’s regional aviation outlook for Africa.

Open skies policy and the regulatory gap

The commercial dynamism of this corridor exists in tension with regulatory fragmentation. Africa’s Single African Air Transport Market, known as SAATM, was launched under African Union auspices in 2018 to liberalize intra-African air travel and strengthen the continent’s competitive position. Progress has been uneven: as of recent AU assessments, fewer than forty of the fifty-five member states had formally acceded to the agreement, and practical implementation of open-skies provisions has lagged considerably behind the initial timetable.

Bilateral air service agreements between African states and Gulf counterparts add a further layer of complexity. Traffic rights and flight frequencies remain subject to negotiation, sometimes reflecting protections for national carriers rather than the interests of consumers or exporters. Where these constraints have eased, route expansion has followed quickly. Rwanda’s relatively liberal aviation policy has helped Kigali attract Gulf-facing services disproportionate to its population size, a lesson that other governments are now studying carefully.

Visa regimes compound the friction. For Gulf-based business travelers seeking to access multiple African markets in a single trip, the patchwork of visa-on-arrival policies and traditional embassy requirements remains a genuine barrier. Several African governments have simplified entry procedures in recent years, but continent-wide harmonization remains a medium-term aspiration rather than a present reality.

The stakes extend beyond traveler convenience. Aviation connectivity functions as infrastructure: it underpins deal-making and supports export-dependent industries from floriculture to pharmaceutical distribution. Investment flows between Africa and the Gulf are, in part, shaped by how accessible cities are to one another. Civil aviation authorities that push for open-skies provisions alongside airport investment are positioning their countries as genuine nodes in a reconfiguring South-South economic geography.

The commercial momentum behind this corridor is reflected in every new route launch and cargo terminal agreement. Whether institutional reform can move at the pace that airlines, exporters and investors now require is the question pressing hardest on policymakers at both ends of the route.

Read more

Red Sea Disruptions Push Gulf Operators to Commit Billions to African Port Infrastructure

Comments (0) Business

Container ships docked at Jebel Ali port, Dubai, with cranes overhead

A Crisis That Became a Catalyst

Three years after Houthi attacks on commercial shipping triggered a mass rerouting of vessels away from the Red Sea, the scale of the structural change is becoming measurable. According to data from BIMCO cited by Trade Finance Global, container ship transits through the Red Sea and the Suez Canal fell by more than 60% from their 2023 levels. The vessels that chose the Cape of Good Hope route added roughly one to two weeks of voyage time and approximately one million dollars in extra fuel costs per trip. Daily commercial vessel traffic around the Cape averaged 20 ships between March and late April 2026, up from just six in 2023, according to IMF data cited in ACCA’s AB Magazine.

For Egypt, the impact was direct and severe. Suez Canal revenues, a critical source of foreign exchange, collapsed as traffic dried up. For ports along Africa’s southern and eastern coastlines, the sudden surge in vessel calls exposed structural bottlenecks that existing capacity could not absorb.

A partial normalization is now underway. Maersk, Hapag-Lloyd, and MSC have each announced that select services will return to Red Sea transits as security conditions partially stabilize. The Suez Canal Authority recorded a 54% year-on-year rise in net tonnage for the first eight months of 2026. But as Ecofin Agency reported in October 2026, Lloyd’s List Intelligence counted just 184 container-ship transits through Suez in August 2026, against 549 in August 2023. The crisis lasted long enough to redirect investment capital into African port infrastructure at a pace that will outlast the security situation that triggered it.

Gulf Operators Lock In Long-Term Positions Across African Ports

DP World, the Dubai state-linked logistics operator, launched a direct shipping route between Jebel Ali and Berbera in Somaliland in October 2025. Operating on a nine-day cycle with stops at Aden and Djibouti, the service connects the UAE’s flagship hub directly to the Gulf of Aden and opens a faster corridor into landlocked Ethiopia, an economy of more than 130 million people. Beyond East Africa, DP World is developing a deep-sea port at Ndayane in Senegal and a major terminal at Banana in the Democratic Republic of Congo, as part of a commitment to invest three billion dollars in African port and logistics infrastructure over the next three to five years, according to Trade Finance Global.

Abu Dhabi’s AD Ports Group is building its African portfolio through a parallel strategy. The group secured an 81% ownership stake in Luanda’s multipurpose terminal under a 20-year concession and holds a 30% stake in the Dar es Salaam container terminal in Tanzania through a joint venture with Adani Ports and East Harbour Terminals. In August 2025, AD Ports also signed an agreement with Angola’s trade regulator, ARCCLA, to develop a digital Single Logistics Trade Window, alongside a six-million-dollar expansion of its local truck fleet under the Noatum Unicargas Logistics subsidiary. For 2026, the group has budgeted AED 2.45 billion (approximately 667 million dollars) in port infrastructure capital expenditure, according to its own investor presentations.

The investment logic extends well beyond the current security situation. Concessions running 20 to 30 years give Gulf operators direct control over terminal operations, replacing a model built on short-term agreements. Gulf states are no longer just acquiring stakes in African assets: they are assuming operational responsibility for the corridors that link African producers to global markets.

The Efficiency Gap African Ports Must Now Close

The scale of Gulf investment is not matched by uniform port performance across the continent. Wait times for vessels to offload cargo at Dar es Salaam can stretch to five days, compared to 1.25 days at Kenya’s Port of Mombasa, according to Trade Finance Global. That differential matters to shippers calculating total logistics costs and limits how much traffic a port can retain once the Red Sea becomes viable again.

Sameer Bhatnagar, global head of ports at KPMG, outlined the risk in ACCA’s AB Magazine in May 2026: “Without addressing these constraints, increased shipping volumes risk translating into congestion and higher logistics costs rather than economic benefit.” His list of urgent investment priorities included deep-water berths, port rail corridors, and digital upgrades to reduce cargo dwell times.

Ebrima Sawaneh, group COO and CFO at Arise Ports and Logistics, which manages concessions across West Africa, gave a candid sector-wide assessment: “A few African ports are clearly world class or close to it, but many others are still constrained.” If efficiency gaps persist, the traffic diverted from the Red Sea becomes a temporary windfall rather than a platform for lasting competitiveness.

The potential upside of closing those gaps is substantial. Trade Finance Global estimated that efficiency improvements across African port infrastructure could yield up to 5.3 billion dollars in total logistics-chain savings.

Infrastructure Arriving Before the Institutions

The corridors, terminals, and digital customs systems now under construction will be operational long after current Red Sea security dynamics have resolved. The Jebel Ali-Berbera route, the Ndayane deep-sea terminal, the Banana port in the DRC, and the Angola digital trade window are commitments locked in by operators working on generational time horizons.

For African coastal states and their regional bodies, the pressing question is whether institutional frameworks can be upgraded to match the capital now arriving. Customs harmonization between neighboring port states, accelerated port authority reform, and investment in port-adjacent rail infrastructure would all help domestic economies capture more of the value moving through their waters. The private capital is in place. The governance architecture to make full use of it is still being assembled, and the window to do so is not indefinite.

Read more

From Lagos to Riyadh: The Rise of a New Afro-Arab Creative Powerhouse

Comments (0) Business, Featured

Africa has the stories. The Gulf has growing ambitions to finance and distribute them. From Nigeria’s prolific film industry to Saudi Arabia’s expanding cinema ecosystem, a new network of cultural and commercial partnerships is taking shape. Film festivals, investment funds and streaming platforms are bringing African filmmakers closer to Arab audiences, opening opportunities for an industry long constrained by limited financing and fragmented distribution.

The numbers illustrate the potential. According to UNESCO’s 2021 report on the African film industry, Nollywood produces approximately 2,500 films annually, making Nigeria one of the world’s most prolific film-producing countries. Across Africa, the film and audiovisual sector generates an estimated $5 billion in annual revenue, according to figures cited by UNESCO, despite persistent challenges involving piracy, infrastructure and access to capital.

Meanwhile, Gulf countries are investing heavily in entertainment as part of broader economic diversification strategies. Saudi Arabia reopened commercial cinemas in 2018 after a decades-long prohibition, while its Red Sea International Film Festival, established in Jeddah in 2021, has developed into a meeting point for filmmakers, producers and investors from the Arab world, Africa and beyond.

The relationship is increasingly moving beyond film screenings and distribution agreements. Financing initiatives, production grants and international project markets are creating opportunities for African filmmakers to develop projects with partners in the Gulf.

Capital meets creativity: the Gulf’s growing interest in African cinema

Saudi Arabia’s entertainment ambitions are closely tied to Vision 2030, the kingdom’s economic diversification programme. Beyond expanding domestic cinema infrastructure, the country is positioning itself as a financing and networking hub for international film production.

The Red Sea Film Foundation provides one of the clearest examples of this strategy. Through its Red Sea Fund, the organisation supports film projects at different stages of development, production and post-production, including works by African and Arab filmmakers.

By 2025, the foundation reported supporting more than 340 projects from over 66 countries across the Arab world, Africa and Asia. Its activities extend beyond grants to include training programmes, industry networking and the Red Sea Souk, a project market designed to facilitate international partnerships.

The results are increasingly visible at major film festivals. In February 2025, nine projects supported by the foundation were presented at the Berlin International Film Festival or its associated industry market. They included The Heart Is a Muscle, a South African drama directed by Imran Hamdulay, and Ancestral Visions of the Future, a documentary by Lesotho-born filmmaker Lemohang Jeremiah Mosese.

These examples demonstrate how Gulf-based institutions are helping African productions gain access to financing and international visibility. However, financial support does not automatically constitute a formal coproduction: the distinction depends on the contractual and production arrangements of each project.

Some projects already illustrate deeper cross-regional involvement. The Mother of All Lies, directed by Morocco’s Asmae El Moudir, lists Morocco, Egypt, Saudi Arabia and Qatar among its production countries. Tunisian filmmaker Kaouther Ben Hania’s Four Daughters similarly brought together production partners from Tunisia, Saudi Arabia and Europe.

Such collaborations provide a more concrete picture of the emerging Afro-Arab audiovisual ecosystem than investment announcements alone.

Beyond cinema: streaming, music and new audiences

Digital distribution is another important factor in the relationship between African and Arab creative industries.

Streaming platforms have reduced some of the geographical barriers that previously limited the circulation of films, television series and music. Services such as Shahid, operated by MBC Group, have helped expand digital entertainment distribution across the Middle East and North Africa, while international platforms have made African productions accessible to wider audiences.

However, reaching viewers across both regions remains a commercial challenge. Language, licensing arrangements, subscription affordability and audience preferences all influence whether a production can succeed beyond its domestic market.

Music offers another avenue for cultural exchange. Nigerian Afrobeats and South African amapiano have gained international recognition, creating opportunities for African artists, promoters and music companies to reach audiences in the Gulf.

Anghami illustrates the development of the region’s digital music infrastructure. Founded in Lebanon in 2012, the streaming company established its headquarters in Abu Dhabi and became publicly traded on Nasdaq in February 2022. Its expansion reflects the growing importance of regional platforms in music licensing, digital distribution and artist promotion.

Yet the commercial relationship between African music industries and Gulf entertainment businesses remains less documented than the global popularity of African genres. Concert appearances and streaming availability demonstrate audience interest, but should not be confused with evidence of large-scale joint investment or production.

Institutional support and the economics of collaboration

The expansion of Africa’s creative economy is also attracting greater attention from development finance institutions.

One of the most significant initiatives is Creative Africa Nexus (CANEX), launched in 2020 by the African Export-Import Bank (Afreximbank). The programme aims to support African creative industries through financing, infrastructure development, capacity building and international market access.

In October 2024, Afreximbank announced plans to increase its CANEX financing facility from $1 billion to $2 billion over the following three years. The initiative covers sectors including film, music, fashion and sports, reflecting growing institutional recognition of creative industries as potential sources of employment, investment and export revenue.

On the Gulf side, the Red Sea Souk has become a platform for connecting filmmakers with potential financiers and production partners. Its 2025 project market selected 40 film and television projects, including 24 projects in development or production, eight works in progress and eight episodic projects.

Together, these initiatives address complementary needs. African producers frequently face financing and distribution constraints, while Gulf-based institutions are seeking to develop international partnerships, strengthen production capabilities and expand their cultural influence.

Egypt and North Africa also occupy an important position in this evolving landscape. Their established film industries, Arabic-language markets and connections with both African and Middle Eastern production networks create opportunities for collaboration. The involvement of Egyptian, Moroccan and Tunisian partners in internationally financed films illustrates how these relationships can operate across several countries rather than through a simple Lagos-to-Riyadh corridor.

A promising market, but significant barriers remain

Despite these developments, Afro-Arab creative partnerships face considerable structural challenges.

Film and television coproductions require agreements covering financing, intellectual property, creative control, revenue sharing and distribution rights. Differences in national regulations, content restrictions and production standards can complicate negotiations, particularly for independent producers without extensive legal or commercial resources.

Language presents another challenge. Nigeria’s film industry produces content in English and several local languages, while much of the Gulf’s mainstream television market is Arabic-speaking. Subtitling, dubbing and culturally adapted marketing therefore remain essential to reaching audiences across both regions.

There is also a difference between supporting African films and building sustainable African production industries. International grants can help individual projects reach completion, but long-term growth requires stronger local financing systems, technical training, production infrastructure and reliable distribution networks.

For Gulf investors, commercial success will depend on identifying projects with viable audiences and distribution strategies rather than assuming that cultural proximity automatically translates into demand.

Nevertheless, the foundations of a broader partnership are becoming more visible. Saudi film funds are supporting African directors, international project markets are bringing producers together, and African financial institutions are expanding their commitments to the creative economy.

The next stage will depend on whether these initiatives produce sustained investment, recurring partnerships and films that succeed commercially across multiple markets.

From Lagos to Jeddah, Cairo and Riyadh, the opportunity is no longer simply to export African stories. It is to build the financing, production and distribution networks that allow African and Arab creative industries to grow together.

Read more

Gulf investors anchor Morocco’s $35 billion green hydrogen drive

Comments (0) Business

ACWA Power Khalladi wind farm turbines, northern Morocco

The ‘Morocco Offer’: A State-Led Bet on Clean Energy Export

Morocco has been developing a national green hydrogen strategy since 2021, positioning the kingdom as a future exporter of hydrogen derivatives to European markets. The strategy rests on the country’s considerable solar and wind resources: according to the International Renewable Energy Agency (IRENA), Morocco is on course to achieve the third lowest green hydrogen production costs in the world by 2050, with projected costs ranging between roughly $0.7 and $1.4 per kilogram, placing it alongside a handful of resource-rich nations in the most competitive tier.

The centrepiece of that strategy is what Rabat calls the ‘Morocco Offer,’ a state-led initiative launched in 2024 to channel large-scale foreign investment into hydrogen production and derivative industries, offering preferential access to public land and associated infrastructure. In March 2025, Prime Minister Aziz Akhannouch chaired a steering committee that selected five investor groups for six specific projects, together valued at approximately $32 to $35 billion, according to AGBI and Morocco World News. The selected projects target production of green ammonia, e-fuels and clean steel, all within the kingdom’s southern provinces.

By February 2026, the programme moved from project selection to concrete land commitments. On 5 February, Akhannouch met in Rabat with representatives of all five investor groups to sign preliminary land reservation agreements. Each project gained access to up to 30,000 hectares, according to Ecofin Agency, enabling consortia to formally launch feasibility studies and move into active development.

Gulf Energy Companies Make Their Commitments Concrete

Two of the five selected investor groups carry direct Gulf capital, and their participation illustrates how the programme has become a practical Africa-Gulf energy partnership.

TAQA Morocco,  a subsidiary of Abu Dhabi National Energy Company, joined forces with Spain’s Moeve in a consortium focused on green ammonia and industrial e-fuels. Under the arrangement, TAQA Morocco is responsible for renewable energy generation underpinning the project, while Moeve leads e-fuels production and marketing. In its initial phase, the consortium expects to produce around 100,000 tonnes of hydrogen per year, converting that output into approximately 560,000 tonnes of green ammonia for both domestic use and export, according to a Moeve press release issued in February 2026.

Saudi Arabia’s ACWA Power entered the programme with its ‘Green Pearl’ project. The company is not a newcomer to Morocco: its total investments in the kingdom’s renewable energy sector already stand at close to $3 billion, making it one of the country’s largest foreign energy investors. As of late June 2026, ACWA Power’s management in Morocco confirmed to Asharq Business that the company is actively seeking to expand into green hydrogen, seawater desalination and energy storage, per Morocco World News. That statement, made during a visit to its Khalladi wind farm, signals a deepening commercial relationship rather than a one-off transaction.

The logic driving Gulf participation is strategic as well as financial. Saudi Arabia and the UAE are both diversifying their portfolios into clean-energy value chains expected to define the post-oil economy. Morocco, positioned at the western edge of North Africa with Atlantic deep-water ports and close proximity to European markets, offers geography well suited to that ambition. For Gulf energy majors, co-developing projects in Morocco is also a way to secure off-take relationships and supply chain positions before competitors do.

Local Stakes and the Industrialisation Imperative

The scale of the programme raises a question that runs through nearly every large infrastructure initiative on the continent: who captures the value?

Morocco’s government has framed the ‘Morocco Offer’ as more than an export platform. The kingdom’s hydrogen strategy envisions a domestic market of 4 terawatt hours alongside an export market of 10 TWh by 2030, requiring the construction of 6 gigawatts of new renewable capacity, as outlined by the Green Hydrogen Organisation. That production base is intended to feed domestic industries: green ammonia substituting for costly fertiliser imports, and clean hydrogen eventually feeding emerging steelmaking capacity. Morocco’s target of reaching 52% renewable electricity by 2030 adds domestic demand that reduces the risk of projects becoming purely export-oriented enclaves.

The feasibility study phase now under way will be critical in determining whether local industrialisation ambitions are written into binding contractual terms, including local content requirements, workforce development obligations and technology transfer commitments. Morocco’s Ministry of Energy Transition, led by Leïla Benali, has consistently stressed these conditions in parliamentary statements, though the detailed terms of individual project agreements remain commercially confidential.

The timeline is also demanding. Most projects target first exports by the late 2020s or early 2030s, coinciding with when the European Union’s hydrogen import strategy is expected to generate significant commercial pull. For Gulf investors experienced in financing long-horizon energy infrastructure in complex regulatory environments, such timelines are familiar terrain. For Morocco, the stakes reach further: the programme’s credibility as a global investment destination depends on whether the first projects are delivered on schedule and on the terms originally promised to investors and citizens alike.

What has changed in 2026 is that ambitions long confined to policy documents have been backed by signed land agreements, launched feasibility studies and companies committing capital on the record. ACWA Power’s latest signal of expanded ambitions in Morocco suggests that the Africa-Gulf green hydrogen axis is moving beyond the era of strategic announcements into one of practical implementation.

Read more

African GovTech Crosses Borders: Digital ID Systems Eye MENA Markets

Comments (0) Business

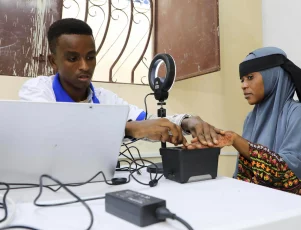
Biometric ID enrollment process at an African government service centre

The scale of Africa’s digital identity infrastructure push is often underestimated outside the continent. Nigeria’s National Identity Management Commission had enrolled more than 100 million citizens in its National Identification Number (NIN) system by 2023, according to official government statements. Ghana’s biometric national identity card scheme, managed by the National Identification Authority, has reached near-universal coverage among adults in the country’s urban centres. Rwanda, consistently cited in World Bank and African Development Bank assessments as a regional benchmark for e-government, has integrated its national ID system with the Irembo platform, which allows citizens to access over a hundred public services online.

Morocco sits at the geographic and institutional intersection of this story. Its electronic national identity card (CNIE) has been operational since 2008 and progressively upgraded to function as an authentication layer for digital services. That track record of deployment and refinement places Morocco at the crossroads between sub-Saharan innovation and MENA market realities.

Underpinning many of these national efforts is sustained international institutional support. The World Bank’s Identification for Development (ID4D) initiative, launched in 2014, has committed over one billion dollars across more than forty countries, with a significant share directed at African and Middle Eastern states, according to the initiative’s own reporting. The African Development Bank’s Digital Infrastructure for Africa program similarly finances connectivity and digital public goods projects across the continent. Their involvement has helped establish technical standards around biometric formats, cryptographic security and data interoperability that align African national systems with globally recognized practices.

MENA Governments Turn to African GovTech for Digital Infrastructure

The idea that a Nigerian, Rwandan or Ghanaian GovTech provider could supply digital identity infrastructure to a Gulf or Levantine government would have seemed improbable a decade ago. Today it reflects a convergence of practical pressures.

Several MENA governments face variants of the same challenge that drove African countries to build their own systems: large informal or underserved populations, fragmented legacy databases, and the need to integrate social protection, tax administration and financial services into a single identity layer. The engineering requirements often overlap more than the surface differences in income level or institutional context might suggest. African platforms, designed to handle unreliable connectivity, diverse linguistic contexts and high transaction volumes in resource-constrained environments, offer a kind of practical flexibility that generic Western enterprise software rarely provides.

Cost is also a material factor. International software vendors typically price GovTech solutions for governments with large procurement budgets. African providers, whose platforms were frequently co-developed with donor co-funding and priced for emerging-market clients, can present more competitive terms. Smile Identity, the Nigeria-and-Kenya-rooted identity verification company founded in 2017 and now operating across more than thirty African markets, has publicly described its pricing model as designed for high-volume, low-margin environments that global incumbents are not set up to serve efficiently.

Beyond pricing, there is the logic of shared institutional experience. African nations that have navigated the political complexity of population registration, biometric governance and civil registration reform have developed direct operational expertise that Gulf states pursuing rapid e-government transformations can draw on. The African Union’s Digital Transformation Strategy for Africa, adopted in 2020 with a horizon to 2030, explicitly frames digital public infrastructure as an exportable asset and calls for partnerships extending beyond the continent’s borders.

Data Sovereignty and Interoperability: Obstacles to Cross-Regional Scale

The structural opportunity is real. The obstacles are, too. Cross-border deployment of identity systems raises immediate questions about data sovereignty: which jurisdiction retains custody of the biometric data, and under what legal framework can it be shared or accessed? Without a clear bilateral or multilateral legal architecture, governments on both sides face legitimate governance risks that can delay or block partnerships, regardless of their technical merits. This is not a hypothetical concern: several African digital ID rollouts have already faced domestic legal challenges over data storage and access rights, providing cautionary precedent for cross-border arrangements.

Interoperability  presents a second challenge. African national ID systems vary in underlying architecture, data models and security protocols. A platform built for Nigeria’s scale and federal structure does not translate automatically into one suited to a smaller, centrally governed Gulf state. Successful cross-regional deployments require investment in adaptation layers and, typically, sustained technical assistance well beyond the initial contract period.

These obstacles explain why the World Bank’s ID4D initiative and the African Development Bank have been exploring common technical standards and model legal frameworks applicable across Africa and MENA. Sub-regional discussions at the COMESA and ECOWAS levels around mutual recognition of digital credentials offer one potential template for a wider Africa-MENA framework, though translating sub-regional precedents into cross-continental arrangements requires political will alongside technical alignment.

The commercial and institutional momentum behind African GovTech shows no sign of reversing. African identity technology companies have attracted growing venture capital, and governments across the continent have invested steadily in the public-sector infrastructure that underpins private digital services. As these systems mature, the primary barrier to cross-regional deployment will be less about whether the technology performs and more about whether policymakers in Addis Ababa, Cairo, Riyadh and Nairobi can build the legal and diplomatic scaffolding to support it. That is a task for institutions as much as for the engineers and founders who built the platforms themselves.

Read more

From Cairo to Nairobi, Gulf Wealth Fuels Africa’s Urban Boom

Comments (0) Business

Africa50 infrastructure project site, urban transit corridor in an African city

Cities in need of capital

Africa is urbanizing at a pace few regions have experienced in modern history. The United Nations projects that the continent’s urban population will nearly double by 2050, with hundreds of millions of people moving into cities that already strain under inadequate transport networks, housing shortages and unreliable public services. For municipal authorities in Nairobi, Lagos, Casablanca, Kigali or Dakar, the fiscal arithmetic rarely works: budgets are constrained, creditworthiness is often insufficient to access international bond markets on viable terms, and official development assistance comes with timelines and conditionalities that do not always match project realities.

Into this gap, a new category of investor has been stepping in. Sovereign wealth funds and public development banks, from both Africa and the Gulf, have begun targeting city-scale assets as a strategic priority. The pattern represents a departure from earlier Africa-Gulf capital narratives, which concentrated on energy megaprojects and agribusiness, and more recently on critical minerals. Urban assets, from bus rapid transit corridors to affordable housing and port-adjacent logistics parks, are now actively drawing sovereign capital.

How Gulf and African institutional mandates are converging

On the Gulf side, large sovereign wealth funds face a clear imperative to diversify beyond hydrocarbon-linked returns. Saudi Arabia’s Public Investment Fund (PIF), which manages assets estimated at over 700 billion US dollars, has expanded its international infrastructure portfolio steadily over the past five years. Abu Dhabi’s ADQ and Mubadala have both made commitments to African assets across several sectors, while the Qatar Investment Authority has pursued long-horizon opportunities in emerging markets. Urban infrastructure, with its inflation-linked revenue streams from tolls, fares and lease income, fits well within the mandates of funds designed to think across generations.

On the African side, the institutional architecture for attracting such capital has grown more sophisticated. Africa50, the pan-African infrastructure investment platform backed by African governments and the African Development Bank, has built a portfolio that includes urban transport and toll road projects across multiple countries. It has positioned itself explicitly as a co-investment vehicle capable of working alongside Gulf and other international sovereign partners. Egypt’s Sovereign Fund, Morocco’s development investment institutions and newer public vehicles in Rwanda and Senegal have similarly articulated strategies that welcome foreign co-investors as catalytic partners rather than as lenders of last resort.

The combination works because each side brings different capabilities. African public funds and development banks hold regulatory knowledge, community relationships and political legitimacy that Gulf funds do not possess locally. Gulf sovereign funds bring capital at a scale that African institutions cannot match on their own. Africa50 projects have been structured through blended equity and long-term debt arrangements that distribute risk between public and private investors, with African institutions retaining governance stakes, according to the platform’s own published documentation.

From Cairo to Casablanca: deals taking shape

Several projects illustrate how this co-investment model is materializing. Egypt’s New Administrative Capital, one of the largest urban infrastructure undertakings in Africa or the Middle East in recent years, has drawn on Egyptian state resources alongside Gulf sovereign participation to finance transport networks, digital infrastructure and public buildings across a new city built to relieve pressure on Greater Cairo.

In Morocco, state-backed investment platforms have co-developed urban regeneration and waterfront projects with Gulf partners, drawing on Casablanca’s established position as a financial intermediary between Europe, sub-Saharan Africa and the Middle East. These are not isolated episodes. The African Development Bank, in its infrastructure needs assessments, has estimated the continent’s annual financing gap at between 130 and 170 billion US dollars, a figure that explains why sovereign capital is being actively pursued rather than merely welcomed.

Africa50’s own disclosed portfolio confirms multi-hundred-million-dollar commitments in road and transit projects across several African countries, typically structured so that performance benchmarks are tied to service delivery outcomes. In practical terms, that means financial return for investors is at least partly linked to whether the infrastructure actually functions for its users.

Transparency, land rights and affordability concerns

The shift toward sovereign-fund-led urban financing also introduces governance questions that practitioners and civil society have begun to raise. Unlike multilateral lending, which typically involves established safeguard frameworks and mandatory disclosure requirements, sovereign fund investments are often channeled through private vehicles that carry more limited transparency obligations. Questions about procurement processes, land rights and fare-setting authority have surfaced in several African cities where large infrastructure deals involving foreign capital are under negotiation.

The concerns are substantive. Transit systems that rely on private fare revenue to service debt can generate affordability pressures for low-income residents. Real estate bundled with infrastructure can drive up land values in ways that displace communities adjacent to new corridors. Both the African Development Bank and Africa50 have published social inclusion and environmental frameworks, and both institutions have argued publicly that deals in which African public bodies hold genuine governance stakes, not merely minority financial interests, are better placed to enforce those standards over the life of a project.

The road ahead for African urban co-investment

The trajectory points toward more sovereign-fund involvement in African urban infrastructure, not less. Urbanization pressures are not easing, and the financing gap documented by the African Development Bank will not close through official assistance alone. Gulf sovereign funds, able to deploy meaningful capital into individual city projects while staying within normal risk parameters, represent a structural fit for a structural problem.

What the model still needs is the institutional scaffolding to make deals faster and more accountable to the residents they are meant to serve. Regulatory alignment between African and Gulf financial frameworks, along with clearer public reporting norms for sovereign co-investments, are practical priorities that the African Union and the African Development Bank are working to advance. How quickly that work progresses will determine whether the next generation of African city dwellers benefits from this capital shift, or simply witnesses it from a distance.

Read more

Africa and the Gulf Are Redrawing the Global Tourism Map

Comments (0) Business, Featured

For most of the past two decades, the Africa-Gulf aviation relationship was largely a story of stopovers. Dubai, Doha and Abu Dhabi became indispensable hubs for passengers transiting between African cities and European or Asian destinations, with Gulf carriers building formidable networks across the continent. Emirates serves more than 20 African countries; Qatar Airways operates routes to over 30 African destinations. But the character of these flows is changing. Increasingly, African travelers and Gulf visitors make direct bilateral trips for purposes beyond transit: business, leisure, medical care or family visits within diaspora communities.

This shift reflects structural changes on both sides. Gulf states, particularly Saudi Arabia and the UAE, have invested heavily in domestic tourism infrastructure as part of broader economic transformation programs. Saudi Vision 2030 set an explicit target of attracting 150 million visitors annually by 2030, a figure cited by the Saudi Tourism Authority, and African source markets represent a largely untapped opportunity. The UAE has long drawn West and East African business communities to Dubai, and that foundation is now being extended to leisure and hospitality. On the African side, tourism ministers from Kenya to Morocco have recognized that Gulf visitors, who tend to record higher per-capita spending than many other source markets, merit deliberate policy attention.

Visa Reform and Route Openings as Strategic Moves

The clearest expression of this strategic intent is the wave of visa liberalization that has advanced across the continent. Kenya’s decision to abolish visa requirements for all nationalities, implemented in January 2024, is among the most sweeping examples. The Kenyan government framed the move as an explicit economic measure, anticipating higher tourist volumes and increased business travel. Rwanda’s policy of visa-free entry for all African nationals, in place since 2018, has contributed to positioning Kigali as a preferred conference and business travel destination, supported by investment in convention infrastructure and direct international services.

Airline route decisions track closely alongside these policy shifts. Low-cost Gulf carriers, including flydubai and Air Arabia, have extended their African footprints to cities beyond the established hubs of Lagos, Nairobi and Johannesburg. New or expanded services to Accra, Dar es Salaam, Kigali and other secondary cities reduce travel time and cost, broadening the pool of potential travelers in both directions. Ethiopian Airlines, Africa’s largest carrier by revenue and network, has simultaneously reinforced its Gulf services, using Addis Ababa as a competing hub. The result is a route map with more options and greater downward pressure on fares.

Gulf-based hospitality investment reinforces the same momentum. Regional sovereign wealth funds and hotel groups have gradually increased their exposure to African markets, from high-end lodges in East Africa to business hotels in North African capitals. Abu Dhabi’s ADQ holding company has built a portfolio of investments across African infrastructure and services, signaling a pattern that other Gulf vehicles are beginning to follow in the hospitality and real estate segments.

Local Entrepreneurs Navigate Opportunity and Concentration Risk

Behind the policy announcements and airline route maps, a more granular story is developing at the level of individual businesses and communities. African tour operators, hotel managers, restaurateurs and event organizers who serve international visitors are recalibrating their offerings to Gulf traveler habits, including language, dietary requirements and seasonal preferences. In Marrakech, Nairobi and Kigali, hospitality entrepreneurs report a measurable increase in Gulf visitors over the past two years and are adapting accordingly.

For local actors, the opportunity carries tangible economic weight. Tourism is a labor-intensive sector with documented multiplier effects across accommodation, food service, transport and cultural activities. The United Nations World Tourism Organization consistently ranks African tourism as one of the continent’s most accessible paths to foreign exchange earnings and formal employment. According to UNWTO data, Africa welcomed approximately 70 million international arrivals in 2019 before the pandemic disrupted travel; recovery has been uneven since then but generally stronger in markets that have combined visa liberalization with proactive marketing to new source countries.

The risks deserve clear-eyed attention. A high degree of dependence on a narrow set of source markets exposes destinations to volatility: a geopolitical rupture, a currency shift or a health crisis can rapidly suppress arrivals from a single country. African tourism boards and destination management organizations are increasingly aware of this, and many pursue multi-corridor strategies that treat Gulf visitor growth as a complement to intra-African and European demand rather than a replacement. Environmental sustainability and equitable benefit distribution remain live concerns, particularly in ecologically sensitive areas or wherever large hospitality investments bypass local ownership structures.

The Africa-Gulf Corridor at an Inflection Point

The Africa-Gulf tourism corridor is at an early but accelerating stage of development. Policy conditions are improving, aviation infrastructure is widening, and investment flows are beginning to reflect a genuinely bilateral logic rather than a one-way transit relationship. Whether these gains translate into broad-based economic benefit will depend on decisions made at national and local level: how governments reinvest tourism revenues and whether local businesses can position themselves to capture a meaningful share of visitor spending beyond the large hospitality groups. The potential of the corridor is real; its returns remain a matter of deliberate choice.

Read more

Africa–Gulf: The New Payment Corridors Transforming Remittances

Comments (0) Business

Mobile money transfer app on smartphone, Nairobi, Kenya

For the millions of African workers employed across Gulf Cooperation Council states, the act of sending money home is a routine but costly exercise. According to the World Bank’s Remittance Prices Worldwide database, the average cost of sending 200 dollars from a Gulf country to sub-Saharan Africa has consistently exceeded 7 percent of the transaction value, more than double the 3 percent target set under the UN Sustainable Development Goals. For a domestic worker in Riyadh or a construction technician in Dubai, those fees translate directly into less money reaching a family in Nairobi, Accra, or Lagos.

That cost structure is now under sustained pressure. Over the past several years, a growing cohort of African fintech firms and Gulf-based digital payment platforms have begun constructing interoperable rails that bypass the slow, expensive correspondent banking chains which have long dominated these corridors. The result is a structurally significant reconfiguration of how Africa and the Middle East exchange value, driven not by multilateral mandate but by the commercial logic of founders and regulators on both sides of the corridor.

Mobile money meets Gulf financial modernization

Africa’s mobile money infrastructure is one of the more consequential financial developments of the past two decades. In Kenya, Tanzania, and Ghana, adult population penetration rates for mobile money wallets have surpassed 70 percent in some markets, according to the GSMA’s annual State of the Industry reports. Transaction volumes have grown at double-digit rates year-on-year across multiple markets. This domestic digitalization created an ecosystem capable of receiving international flows cheaply and near-instantly, provided the sending side could connect to it.

The Gulf has, in parallel, been modernizing its own financial infrastructure. Central banks in Saudi Arabia, the UAE, Bahrain, and Qatar have invested in real-time gross settlement systems and open banking frameworks that lower barriers for fintech entrants. Some Gulf central banks have reported more than 100 percent growth in contactless and instant transfer volumes within single-year periods. The combination of Africa’s mobile-first depth and the Gulf’s regulatory ambition creates the structural conditions for cross-border interoperability.

The operational mechanism is typically an API-based connection linking an African mobile wallet to a Gulf bank account or digital wallet. When an African fintech secures a payment license in a Gulf jurisdiction, it can offer customers the ability to load a wallet in dirhams or riyals and push funds to a mobile money account in Kenyan shillings or Ghanaian cedis within minutes. Several pan-African payment companies have pursued precisely this licensing strategy, seeking regulatory approval in the UAE and Saudi Arabia to serve large African diaspora communities. Gulf-based neobanks, meanwhile, have begun targeting African workers as a core customer segment, given the volume and regularity of their outbound transfers.

Beyond remittances: SME trade and strategic autonomy

The significance of this infrastructure extends well beyond personal remittances. African small and medium enterprises importing goods from Gulf trading hubs, particularly from Dubai’s re-export markets, have historically relied on international wire transfers that can take several days to settle and carry fees that erode already thin margins. Digital payment rails enabling near-instant settlement change the economics of cross-border trade in concrete ways. The African Development Bank has repeatedly emphasized the importance of payment efficiency in enabling intra-regional and South-South commerce, noting persistent gaps that formal banking has been slow to fill.

There is also a geopolitical dimension that analysts are beginning to discuss. Historically, remittance routes between the Gulf and Africa have run through Western correspondent banks or global money transfer operators, which have held considerable pricing power and data visibility over these flows. As African and Gulf actors build their own rails, they gain operational autonomy over fees and routing decisions. This represents a gradual diversification of the financial connective tissue linking the two regions, with African and Gulf actors exercising greater agency than before.

The Islamic Development Bank and the Arab-Africa Trade Bridges program have signaled interest in formalizing such corridors further, linking payment infrastructure to trade finance and development objectives. Regulatory coordination between Gulf and African central banks, while still at an early stage, is beginning to surface as a topic in bilateral and multilateral financial diplomacy.

A corridor still under construction

The buildout of Africa-Gulf digital payment infrastructure remains a work in progress. Regulatory fragmentation across Africa’s 54 jurisdictions means that a license secured in Nigeria does not automatically confer access in Senegal or Ethiopia. Currency volatility in several African markets adds foreign exchange risk that technology alone cannot absorb. Consumer trust in new digital products, particularly among older or less digitally literate migrant workers, requires sustained investment in agent networks and customer education.

None of these obstacles is insurmountable. The trajectory of the sector, measured in licensing milestones and expanding transaction volumes, points clearly toward continued integration. What distinguishes this moment is that the architects of these corridors are not waiting for a global institution to hand them a blueprint. African fintech founders expanding into Gulf markets, Gulf payment operators targeting African diasporas and regulators in both regions adjusting their frameworks are collectively building a financial layer that serves hundreds of millions of people in ways the legacy system never prioritized.

Read more