Non classé
Category

Oil hits 6-week high after OPEC deal, sterling jumps

Comments (0) Non classé

By Jamie McGeever

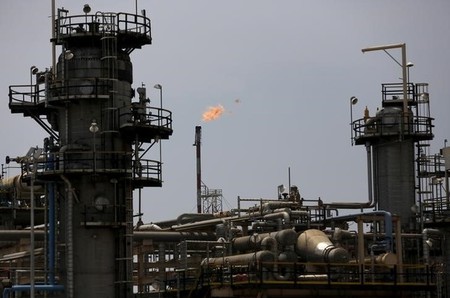
LONDON (Reuters) – Oil swept to a six-week high on Thursday after OPEC agreed to cut crude output to help clear a glut, while sterling hit a three-month peak after traders interpreted comments from a senior UK official as a crack in the government’s “hard Brexit” line.

Global bond yields rose on prospects that resulting inflationary pressures from oil’s surge will lead to higher interest rates, with the benchmark 10-year U.S. Treasury yield matching November’s 16-month high.

European stocks dived, shrugging off the bounce in Asian shares and following the S&P 500’s fall the previous day instead. U.S. futures pointed to another slight decline at the open on Wall Street.

The Organization of the Petroleum Exporting Countries on Wednesday agreed to its first output cut since 2008, finally taking action after global oil prices fell by more than half in the last two years.

Non-OPEC Russia will also join output reductions for the first time in 15 years. [nL8N1DV1UH]

U.S. crude oil added to overnight gains of 9 percent to reach $50.00 a barrel for the first time since October. Brent crude, which soared $4 overnight, touched a six-week peak of $52.73 a barrel.

The jump in oil prices added to inflation expectations in the United States, which were already rising on prospects that President-elect Donald Trump would adopt reflationary policies using a large fiscal stimulus.

“We’ve had a spike in oil prices plus better data, so we’re seeing the reflation trade come back,” said Martin van Vliet, senior rates strategist at ING.

As a result the rout in U.S. Treasuries resumed, with yields pushing higher, especially on longer-dated bonds. The yield on 10-year and 30-year bonds <US10YT=RR<, which are most sensitive to inflation eroding their value, rose 5 basis points to 2.417 percent and 3.077 percent, respectively.


STERLING EFFORT

The 30-year yield has climbed more than 40 basis points since the Nov. 8 presidential election, heading back towards a 14-month peak of 3.09 percent marked last week.

The 10-year yield had its biggest monthly rise in November since 2009. Bonds across the world have lost about $2 trillion in market value since the Nov. 8 U.S. election, according to Bank of America Merrill Lynch data.

Sterling grabbed the limelight in currencies, jumping to a three-month high against the euro and on a trade-weighted basis after Britain’s Brexit minister David Davis said London would consider paying into the EU budget for market access.

The pound had slumped to historic lows following June’s vote to leave the European Union on fears of a “hard Brexit”, which would see Britain give up full access to the single market and the EU customs union in favour of retaining full control over its borders.

“These headlines suggesting Britain may be able to access the single market are generating substantial sterling demand from traders and investors looking to reduce their short positions and unwind hedges,” said Neil Jones, head of FX hedge fund sales at Mizuho.

The Bank of England’s trade-weighted broader measure of sterling rose to 78.8 and the pound was at its strongest against the euro for three months at 83.96 pence per euro. It hit a three-week high of $1.2650 against the dollar after Davis’ comments.

The dollar advanced to a 9-1/2-month high of 114.83 yen before pulling back to 114.30 and the euro recovered from the previous day’s slide to trade back above $1.06 after shedding 0.6 percent the previous day.

Europe’s index of leading 300 shares was down 0.8 percent at 1,340 points, Germany’s DAX was down 1 percent and sterling’s strength drove Britain’s FTSE 100 down 1.3 percent.

Energy and resources stocks in Europe shares outperformed the broader indices, which snapped a two-day winning run. The STOXX Europe 600 Oil and Gas index was up 1.5 percent, while the basic resources index was up 2.1 percent.

MSCI’s index of Asian shares ex-Japan rose 0.4 percent, lifted by stronger-than-expected Chinese manufacturing data, and Japan’s Nikkei 225 rose 1.1 percent after the yen fell to its lowest since February close to 115 per dollar.

Spot gold touched a 10-month low of $1,163.45. Bullion fell 8 percent in November, its worst month in three years.


(Editing by Hugh Lawson)
tagreuters.com2016binary_LYNXMPECB02IP-VIEWIMAGE

Read more

OPEC begins debate on oil cuts amid deep disagreement

Comments (0) Non classé

By Rania El Gamal and Alex Lawler

VIENNA (Reuters) – OPEC began on Wednesday debating a deal to curtail oil production and prop up the price of crude, with Iran and Iraq resisting pressure from Saudi Arabia to participate fully in any action.

Ministers from the Organization of the Petroleum Exporting Countries started an informal meeting at 0700 GMT at the Vienna Park Hyatt hotel and were due to begin a formal gathering at OPEC headquarters at 0900 GMT.

“There will be an agreement today,” an Iraqi delegate said as he entered the hotel.

“I’m optimistic,” said Iranian Oil Minister Bijan Zanganeh, adding there had been no request for Iran to cut output.

On Tuesday, Iran wrote to OPEC saying it wanted Saudi Arabia to cut production by as much as 1 million barrels per day (bpd), much more than Riyadh is willing to offer, OPEC sources who saw the letter told Reuters.

The 14-country group, which accounts for a third of global oil production, made a preliminary agreement in Algiers in September to cap output at around 32.5-33 million bpd versus the current 33.64 million bpd to prop up oil prices, which have halved since mid-2014.

OPEC said it would exempt Iran, Libya and Nigeria from cuts as their output has been crimped by unrest and sanctions.

The deal was seen as a victory for Iran. Tehran has long argued it wants to raise production to regain market share lost under Western sanctions, when its political arch-rival Saudi Arabia increased output.

In recent weeks, Riyadh changed its stance and offered to cut its output by 0.5 million bpd, according to OPEC sources, while suggesting Iran limit production at around 3.8 million bpd – in line with or slightly above the country’s current output.

Tehran has sent mixed signals, saying it wanted to produce as much as 4.2 million bpd. Iran’s letter to OPEC suggested Saudi Arabia should cut output to 9.5 million bpd.

Iraq has also been pressing for higher output limits, saying it needs more money to fight the militant group Islamic State. Iran and Iraq together produce over 8 million bpd, only slightly behind long-time leader Saudi with 10.5 million bpd.

The argument between Iraq and Saudi Arabia mainly focuses on whether Baghdad should use its own output estimates to limit production or rely on lower figures from OPEC’s experts.

Brent crude rose 1.5 percent on Wednesday to more than $47 a barrel after heavy losses a day earlier. [O/R]

Some analysts including Morgan Stanley and Macquarie have said oil prices will correct sharply if OPEC fails to reach a deal, potentially going as low as $35 per barrel.


(Additional reporting by Vladimir Soldatkin, Shadia Nasralla and Lisa Barrington; Writing by Dmitry Zhdannikov; Editing by Dale Hudson)

tagreuters.com2016binary_LYNXMPECAT0DI-VIEWIMAGE

Read more

Nigeria signs agreements to add more than 500 megawatts to national grid

Comments (0) Latest Updates from Reuters, Non classé

LAGOS (Reuters) – Nigeria has signed agreements to add more than 500 megawatts of capacity to its national grid, the office of the vice president said on Thursday.

Africa’s most populous nation produces less than 4,000 megawatts (MW) but requires around 10 times that amount to guarantee power for its 180 million inhabitants.

Chronic power shortages have hindered the country’s development for decades and are one of the biggest constraints on investment and growth in Africa’s largest economy, which is in recession for the first time in more than 20 years.

The vice president’s office said a number of agreements had been signed including ones with the World Bank and Niger Delta Power Holding Company (NDPHC).

“Vice President Yemi Osinbajo at the signing ceremony described the agreements as significant, enabling the consistent additional generation of more than 500 MW of electricity to the national grid,” said his spokesman Laolu Akande.

The vice president said the agreements would open up new opportunities for investments in Nigeria’s gas and power sectors.

He suggested that the West African country could potentially attract investment into the power sector.

Osinbajo’s office said Nigerian gas supplier Seven Energy was investing around $500 million in the construction of a gas processing facility at the Uquo Field in the southern state of Akwa Ibom.

And a Partial Risk Guarantee between the World Bank and NDPHC was signed to secure the supply of some 130 million cubic feet per day of gas to a power plant in the southern city of Calabar by Seven Energy.

The agreement covers private debt in the event of a government’s failure to meet specific obligations to a project.


(Reporting by Alexis Akwagyiram; Editing by James Dalgleish)

tagreuters.com2016binary_LYNXMPECA30HD-VIEWIMAGE

Read more

Ethiopia looks to Islamic finance to tap domestic savings

Comments (0) Latest Updates from Reuters, Non classé

(Reuters) – Ethiopia’s central bank aims to develop Islamic finance to help expand financial access and inclusion, part of wider government efforts to mobilize domestic resources to diversify its economy, a central bank official said.

The landlocked country has one of the highest economic growth rates in Africa, but relies heavily on an agricultural sector that employs three-quarters of the workforce and contributes to around 80 percent of exports.

The government wants to industrialize its economy but this requires sustaining investment rates of almost 40 percent of GDP over the next five years, said Getahun Nana, Vice Governor of the National Bank of Ethiopia.

“This can only be achieved if the financial sector, particularly the banking industry, can play significant role in mobilizing desperately needed savings from domestic sources.”

Islamic finance could help in this endeavor, so the central bank is conducting a study to determine the demand for sharia compliant financial products in a country where around a third of the population of 100 million is Muslim.

The study would help determine what proportion of Muslims are excluded from the financial sector, Nana said in a speech during an Islamic finance conference held this week in neighboring Djibouti.

“If this is identified to be a barrier, a specific and enabling regulatory framework will be developed so as no one is excluded from obtaining financial services because of religious reasons.”

Islamic finance is still new in Ethiopia, despite the government allowing financial institutions to offer such products back in 2008.

Currently eight out of 18 financial institutions offer sharia compliant products via Islamic windows but they have so far mobilized less than 1 percent of total deposits, Nana said.

“Sharia compliant financing facilities that these banks provided to their customers are even very much insignificant.”


(Reporting by Bernardo Vizcaino; Editing by Simon Cameron-Moore; Editing by)

Read more

European Union to ready sanctions over Congo vote delay, violence

Comments (0) Non classé

By Robin Emmott

LUXEMBOURG (Reuters) – The European Union will prepare economic sanctions on the Democratic Republic of Congo unless its ruling coalition, which has delayed next month’s elections, holds a fresh vote early next year, diplomats say.

President Joseph Kabila was due to leave at the end of his mandate in December but authorities have postponed it until April 2018, citing logistical problems.

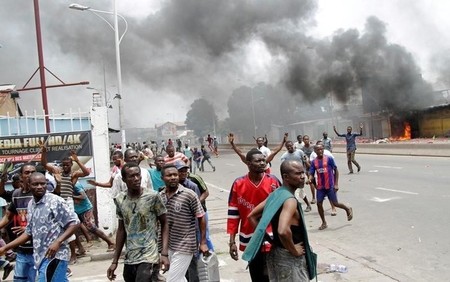
The vote delay sparked two days of protests in the capital Kinshasa last month that killed dozens of people.

“Elections must take place as early as possible, and no later than in 2017,” said an EU diplomat involved in the talks. “Given the situation, we are prepared to consider sanctions and work is already under way,” the diplomat said.

European Union foreign minister meeting in Luxembourg on Monday are expected to agree a statement in which they will make clear that travel bans and asset freezes are a genuine threat.

“The EU will use all the means at its disposal, including individual restrictive measures,” said a draft statement seen by Reuters that would target “those responsible for serious human rights violations, those who promote violence.”

Foreign ministers are expected to task EU foreign policy chief Federica Mogherini to draw up sanctions, which could be on senior police and other members of the security forces, potentially broadened to government officials at a later stage if there is no progress on an electoral agenda.

The European Union, a major donor of foreign aid as well as a big foreign investor and trade partner, is also seeking an independent inquiry into the violence last month and wants talks on a new timetable for presidential and parliamentary elections.

Former colonial power Belgium is pushing EU governments to reduce the duration of diplomatic visas issued to officials, having cut its own visas to six months, one diplomat said.

Kabila, who came to power in 2001 when his father was assassinated, says he will respect the country’s constitution but has yet to rule out attempting to change laws to enable him to run for a fresh term.

The presidents of neighbouring Rwanda and Congo Republic changed their constitutions last year to allow themselves to stand for a third term. Kabila’s opponents say they fear he will do the same.

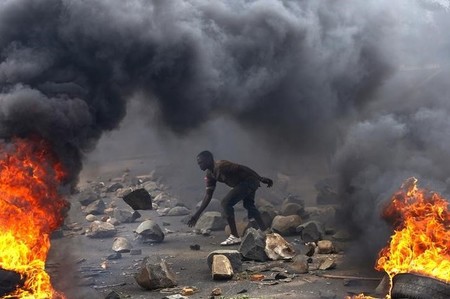
Hundreds of people have also died since last year in Burundi, where the EU has also imposed sanctions, after its president Pierre Nkurunziza pursued and won a third term in office that his opponents say is unconstitutional.

The head of the U.N. mission in Congo warned last week that the political impasse poses an “extreme risk” to stability. Millions died in regional conflicts between 1996 and 2003 and Congo has never had a peaceful transition of power.


(Reporting by Robin Emmott; Editing by Tom Heneghan)

tagreuters.com2016binary_LYNXMPEC9G08Q-VIEWIMAGE

Read more

Gabon cuts 2017 budget again as oil output falls

Comments (0) Non classé

(Reuters) – Gabon’s cabinet has cut its 2017 budget by over 5 percent as persistently low crude prices and falling output pressure the oil-producing Central African economy, it said in a statement on Thursday.

Next year’s budget will drop to 2.478 trillion CFA francs ($4.23 billion) in 2017 from 2.626 trillion CFA francs this year, the statement said, citing a drop in oil prices and production in the OPEC member.

It comes after a small budget drop in 2016 and a 14 percent drop in 2015, both due to a steep drop in crude prices since 2014 and depleting oil fields.

Gabon is Africa’s fourth largest oil producer with an output of around 220,000 barrels per day, dominated by international oil majors Total and Royal Dutch Shell.

President Ali Bongo has said that he plans to diversify the Gabon economy away from oil, but a falling budget will likely apply further political pressure after his razor thin victory in a presidential election in August that the opposition said was rigged. Violent protests ensued in which at least 6 were killed.

Bongo’s victory by less than 6,000 votes over opposition leader Jean Ping has drawn unwelcome scrutiny of the president, whose family has ruled the oil-producing state in Central Africa for 49 years. Many in Gabon complain that the oil wealth is not distributed, leaving most poor and out of work.

Bongo’s international reputation has taken a hit since the election and just a handful of African leaders attended his inauguration.

($1 = 585.6200 CFA francs)


(Reporting by Edward McAllister; Editing by Sandra Maler)

Read more

UN rights forum sets up inquiry into grave crimes in Burundi

Comments (0) Non classé

GENEVA (Reuters) – The top U.N. human rights forum agreed on Friday to set up a commission of inquiry to identify perpetrators of alleged international crimes in Burundi, including killings and torture, and ensure that they are brought to justice.

The 47-member state forum adopted a resolution submitted by the European Union by a vote of 19 states in favour and 7 against with 21 abstentions.

Burundi’s delegation took the floor after the vote to reject the resolution as containing “a lot of lies” about the situation in the central African country which it said had stabilised.


(Reporting by Stephanie Nebehay, editing by Tom Miles)

tagreuters.com2016binary_LYNXNPEC8T15E-VIEWIMAGE

Read more

Kenya secures deal to keep duty-free access to EU market

Comments (0) Non classé

By Duncan Miriri

NAIROBI (Reuters) – Kenya will retain duty-free access to the European Union for its products, its trade minister said on Thursday, reassuring exporters who feared problems in clinching a deal between the EU and the East African Community could lead to tariffs.

Kenyan businesses have been alarmed by delays in signing the trade pact, known as the Economic Partnership Agreement (EPA), between the EU and five-nation East African Community (EAC), after reservations raised by Tanzania.

Kenya stood to lose most as it would have lost duty- and quota-free access, whereas other EAC member states are categorised as poorer nations who keep that access whether or not the more comprehensive trade deal is signed.

The deadline for the EAC to finalise the agreement was Oct. 1 and there were fears that Kenyan goods could be locked out or become subject to tariffs.

“Come next week Kenyan exports will still have access to the EU market without paying any duties, as it was before,” Aden Mohamed, the Kenyan minister for trade and industrialisation, told Reuters.

Kenya, which exports coffee, tea and horticultural products to Europe, secured the continued free access to EU markets after it signed the deal with the EU, despite Tanzania holding back.

Kenya has also already ratified the pact in parliament and it presented a copy to the EU in Brussels on Wednesday.

EAC heads of state are scheduled to discuss the EPA with the EU in January but Mohamed said Kenyan goods would maintain their access regardless of the outcome.

“We are hopeful everybody will come on board and then rather than just having a window of access into the EU, we will enjoy a much more comprehensive agreement that has some benefits of development infrastructure that will come as a result of that agreement being signed,” he said.

Mohamed also said on Thursday that the government had revoked a rule in the 2015 companies law demanding that foreigners investing in Kenya offer a 30 percent stake to a Kenyan party. Foreign investors had criticised the new rule.

“The spirit of what we want to do in the country is to have an economy that is open for business and doesn’t want to impose pressure,” he said.


(Editing by Edmund Blair and Gareth Jones)

Read more

Moody’s may downgrade five South African state-owned firms

Comments (0) Non classé

JOHANNESBURG (Reuters) – Moody’s may cut the ratings of five South African state-owned firms, including utility Eskom, it said on Wednesday, citing funding risks after some local institutional investors said they had stopped lending to some parastatals.

Asset manager Futuregrowth, which manages client assets of about $12 billion, and rival Abax Investments said this month they had reduced or stopped lending to several state-run firms due to political uncertainty and governance issues.

Moody’s said in a statement it was putting Eskom’s Ba1 rating on review for downgrade on the grounds that its funding needs were exacerbated by the rising cost of buying power from independent producers, as well as its spending to revamp and build new power stations.

Eskom is building new plants and transmission lines to augment a power grid that nearly collapsed in 2008 and forced the company to implement controlled blackouts, or load shedding, early last year that dented economic growth.

Chief Financial Officer Anoj Singh called the review “unfortunate” and said Eskom would meet Moody’s to resolve its concerns.

“The review by Moody’s is unfortunate given the progress made towards improving the company’s financial profile, successful implementation of the operations turnaround plan and Eskom’s healthy liquidity position,” Singh said in a statement.

Moody’s is also reviewing the ratings of four other state-controlled entities: the Development Bank of Southern Africa, the Industrial Development Corporation, the South African National Roads Agency (SANRAL) and Land Bank.

“Today’s review for downgrade … primarily reflects the increased risk of funding and liquidity challenges, following some signals of increased risk aversion by funding counterparties owing to market concerns regarding the governance of South African state-owned enterprises,” Moody’s said.

Many of South Africa’s 300-odd state-owned companies, including South African Airways, are a drain on the government’s purse and rating agencies have singled out some as threat to the country’s investment grade rating.

South Africa’s President Jacob Zuma last month defended plans to give his office supervision over state-controlled companies after allies of under-fire Finance Minister Pravin Gordhan said it was a tool to limit his control.

Analysts have said Zuma’s team and the Treasury under Gordhan have disagreed about government spending, including on loss-making state firms, such as South African Airways.

Gordhan has pledged to rein in government spending to limit rising inflation, narrow a gaping budget deficit and appease ratings agencies considering cutting South Africa to “junk” status in reviews expected by December.


(Reporting by Tiisetso Motsoeneng; Editing by David Clarke and Catherine Evans)

tagreuters.com2016binary_LYNXNPEC8E0BF-VIEWIMAGE

Read more

South Africa’s rand tumbles from two-week peak as uncertainty saps momentum

Comments (0) Latest Updates from Reuters, Non classé

JOHANNESBURG (Reuters) – South Africa’s rand extended losses against the dollar to more than 1 percent on Friday, weighed down in part by fears over an ongoing investigation into Finance Minister Pravin Gordhan which exacerbated the impact of a decline in global risk appetite.

Stocks were up slightly, buoyed by resource firms Anglo American and BHP Billiton. The JSE’s benchmark Top-40 index was up 0.4 percent by 1110 GMT.

At 1110 GMT the rand had weakened 1.22 percent to 14.3180 per dollar, its weakest in three sessions.

The unit had touched its firmest in two weeks on Thursday before it began backtracking as doubts over Gordhan’s tenure and uncertainty in global markets over the path of interests rates in the United States and Europe stalled the currency’s progress.

Gordhan, at two separate events on Thursday, questioned the motive of a police investigation into his role in setting up a surveillance unit at the tax service.

“It seems like the rand is rebalancing after over-extending in the previous sessions and traders are waiting for some definitive direction,” said head of foreign exchange at Capilis Asset Management Giacomo Bonavera.

“Around 14.20 or 14.30 might be nice place for it to settle in the medium term. But any bad news from the political side would weaken the currency.”

The rand slipped nearly 10 percent in the wake of police unit the Hawks issuing Finance Minister Gordhan with a summons on Aug. 23 to answer questions about a spy unit in the revenue service during his time as commissioner.

Opposition parties have called the investigation a witch-hunt and a veiled attack on the independence of the treasury.

Government bonds were also weaker, with the yield on the 2026 benchmark issue climbing 14 basis points to 8.74 percent.

A decision on Thursday by the European Central Bank to keep interest rates at record lows received a mixed reaction from emerging markets.

Appetite globally for the high-yielding assets waned as the length that rates would remain low in Europe and in the United States remained uncertain.


(Reporting by Mfuneko Toyana and TJ Strydom; Editing by Robin Pomeroy)

tagreuters.com2016binary_LYNXNPEC880B4-VIEWIMAGE

Read more